Charting a Path to Retirement Success: Financial Planning and Management for Seniors
Glenview-GlenCare-Premier Place- Parent
For more information about the author, click to view their website: The Glenview
Aug 02, 2023
Florida - Southwest

Email US
Click to Email Us
Planning and managing your finances throughout life is like navigating the open seas. You first set sail with youthful vigor, guided by a compass of ambition while bravely exploring uncharted territories and taking calculated risks. As you get older, however, you want to navigate with precision and caution toward the calmer waters of retirement and financial security.
Financial planning and management shift from short-term goals and higher-risk investments, to focusing on saving money for your future. While the winds may change, having well-honed strategies and carefully adjusted sails helps you transition gracefully into retirement on a steady course. When comparing financial planning during different phases of your life, consider these factors:
- Income sources: When we’re younger, our primary income sources are typically employment and potential investments. As we age, income sources may include retirement savings, pension plans, Social Security benefits, and possibly part-time work or passive income from investments.
- Risk tolerance: Generally, younger people have a higher risk tolerance and can afford to invest in riskier assets with the potential for higher returns. In contrast, older adults tend to have a lower risk tolerance and may prioritize preserving wealth and protecting themselves from potential financial setbacks.
- Healthcare expenses: Medical costs increase as people age. Financial planning must account for potential medical emergencies and health care needs.
- Estate planning: Planning for the distribution of assets, creating wills, setting up trusts and considering legacy goals have become more prominent in financial management.
- Social Security and Medicare: Understanding and optimizing government programs is essential to ensure maximum benefits and effective budgeting.
TIPS FOR FINANCIAL PLANNING AND SAVING FOR RETIREMENT
Retirement savings vary widely depending on income, lifestyle, and individual circumstances. Older adults should adopt strategies that address the changing needs and priorities that come with aging while maximizing the value of your hard-earned assets.
Preparing for retirement requires dedication and consistency in your savings approach. Time is a crucial ally, so start saving as early as possible. Consider consulting with a financial advisor who specializes in retirement planning, can provide personalized guidance, and help optimize your savings strategy.
“The unknown can be overwhelming and finances certainly fall into this category,” says Kim Ciccarelli Kantor, CFP, CAP and president of Ciccarelli Advisory Services. “Knowing the questions to ask is an important first step to educating yourself on the principles of money management. Take time to educate yourself, build confidence by learning financial terms, and discuss with your advisor on how they might apply to you.”
Here are some best practices and guidelines to bolster your chances of building a solid foundation for long-term financial well-being.
- Define goals to guide your efforts—whether saving for a house, funding education, paying off debts, or establishing a retirement nest egg.
- Develop a comprehensive budget that tracks your income and expenses. Understand where your money is going and identify areas where you can cut back or save.
- Establish an emergency fund to cover unexpected expenses. Aim to save three to six months’ worth of living expenses.
- Prioritize high-interest debts and consider consolidating or refinancing to lower interest rates.
- Evaluate health, life, disability, and property insurance to ensure adequate coverage and protect yourself and your family.
- Embrace diversification by spreading your retirement savings across various assets, such as stocks, bonds, and mutual funds to manage risk and enhance potential returns.
- Explore strategies to minimize taxes legally, such as contributing to retirement accounts, taking advantage of tax deductions, and optimizing investment holdings for tax efficiency.
- Make the most of retirement accounts like 401(k)s or IRAs, and seize pension plans and any employer matching contributions offered.
- Automate your savings by setting up automatic contributions, ensuring a consistent flow without the temptation to divert funds elsewhere.
- Consider increasing your retirement contributions when your income grows or you receive a raise.
- Pay attention to the fees associated with your retirement accounts and investment options, opting for low-cost alternatives to preserve your returns over time.
- Monitor your progress and adapt your savings strategy to align with your goals and changing circumstances. Financial planning is not a one-time activity.
- Document your financial journey yearly at a specific time by capturing your net worth picture, incorporating all assets and liabilities. Identify how and where assets are held and the value as of a given date. Review trends to assist in your financial planning and decision-making.
“Note financial success is as much the result of your decision-making process as it is about savings, investing, tax management and living within your means,” says Kantor.
TAKE ADVANTAGE OF GOLDEN DEALS AND HIDDEN SAVINGS
Older adults also may not realize the wealth of discounts available to them. Many establishments don’t openly advertise their deals, so it’s worth asking about special offers wherever you go. Additionally, member organizations like the American Association of Retired Persons (AARP) offer a range of exclusive discounts and perks.
By taking the initiative to inquire and explore, you can unlock savings and enjoy the advantages of aging. Here are some opportunities and places where older adults may score discounted deals and other benefits: retail stores, restaurants and cafes, cultural and entertainment venues, public transportation systems, prescription medications, travel, fitness and wellness centers, recreational facilities, cell phone providers, and financial service organizations.
EQUITY OWNERSHIP IN THE GLENVIEW AT PELICAN BAY OFFERS ULTIMATE CONTROL
Many older adults dream of aging gracefully and independently in their own home, a place where they can remain active and stay connected to what they love most. The Glenview at Pelican Bay is a unique, nonprofit, equity-owned LifeCare community in Naples, Fla. that delivers a lifestyle of health, wellness, activity, and much more.
As a controlling member and equity holder, you participate in community decision-making, have the opportunity for your home to appreciate in value, and have access to a continuum of care—a welcome relief for residents and their families throughout all stages of life. Premier Place, our 5-star health center, and GlenCare Home Care services operate right on-site so you’ll never have to worry about where to turn for health care.
A monthly fee covers resort-style services and amenities and exceptional personal services to support a retirement lifestyle inspired by stunning community living spaces for socializing, fitness centers, fine dining, housekeeping, maintenance, scheduled transportation, activities, social events, lifelong learning opportunities, and live entertainment.
Residents at The Glenview continue homeownership along with all the perks and privileges of owning a home in Pelican Bay. They include membership to the Pelican Bay Foundation, private access to Pelican Bay Beach and membership to the 25,000-square-foot Pelican Bay Community Center.
Setting sail to worry-free living at our LifeCare community provides true peace of mind and ultimate control in a gorgeous setting. Discover what your life could look like at The Glenview.
- To view the original version of this article visit glenviewnaples.com/blog/retirement-success-financial-planning-and-management-for-seniors/
- Seniors Blue Book was not involved in the creation of this content.
Other Articles You May Like
Financial Services in Vestavia Hills, AL
A parent may know exactly which purchases would improve a loved ones life, which routines bring comfort, and whom to call when something changes. The harder question is who will carry that knowledge forward.Choosing a trustee involves thinking about both financial administration and continuity. Families need to understand who will manage the arrangement, how information will be shared, and how the beneficiarys needs will remain visible over time.For families in Vestavia Hills, AL, Alabama Family Trust is one resource to explore when the planning need involves a special needs trust. The conversation should address the practical experience of working with a trustee as carefully as the initial paperwork.What Does Choosing a Trustee Involve?A trustee administers a trust under its terms and applicable requirements. Before selecting someone, families should identify the responsibilities the arrangement will require.These may include communication, recordkeeping, review of financial requests, coordination with professionals, and continuing administration through changes in family circumstances.Who Should Be Part of the Discussion?Consider including: The beneficiary, when appropriate. Family members who understand daily needs. The attorney advising on the arrangement. The proposed trust representative. Relevant tax and financial professionals. Keep the conversation manageable by assigning one person to collect questions and document answers.Alabama Family Trust as an Administrative ResourceAlabama Family Trust provides information for trust representatives as well as families and attorneys. Its website identifies support for representatives carrying out their responsibilities. Ask How the Relationship WorksA family should understand how it will interact with the administrator after the account is established.Ask: Who will be our main contact? Which matters require written requests? What information should we keep current? How do we report a change in the beneficiarys circumstances? What happens if our designated contact becomes unavailable? How are questions escalated when additional review is needed? The answers should give the family a realistic picture of ongoing participation.Review the Setup ProcessAlabama Family Trusts current document collection includes materials for different trust arrangements. Its third-party setup documents include confidential information, investment selection, and other supporting forms. Ask which packet applies after obtaining appropriate legal advice. Then request a checklist showing what must be completed, signed, and submitted.Avoid rushing through forms simply because some questions appear repetitive. Consistent information helps everyone understand the same arrangement.Understand Reporting and Investment InformationAlabama Family Trusts investment materials identify professional money management through Waverly Advisors and options with varying levels of risk. For trustee selection, the practical question is how the family will understand and monitor the arrangement.Ask who can access statements, how to request an explanation, and how a change in expected expenses should be communicated.Review Costs Before Making a DecisionAsk for the full current schedule rather than comparing only the opening fee.Discuss how costs may affect the anticipated account and which services are included. Request an explanation of any separate administrative, investment, or tax-related charges.The goal is a clear understanding of the ongoing relationship.Preserving Knowledge About the BeneficiaryFinancial records tell only part of the story. Families should also document the persons preferences and daily circumstances.Create a Personal Information SummaryInclude: Preferred communication methods. Important relationships. Typical routines. Interests and activities. Relevant care contacts. Transportation arrangements. Goals the person wants help pursuing. Explain where the current version will be kept and who will update it.This summary should support professional communication. It should not be treated as a substitute for legal documents or formal instructions.Plan for Changes in Family AvailabilityAn arrangement should remain understandable if the primary caregiver becomes ill, moves, or can no longer participate.Identify a backup contact and ask how a representative change would be documented. Make sure important records are accessible to authorized people.Why This Matters Locally in Vestavia HillsFamilies in Vestavia Hills may have longstanding relationships with local professionals and care providers. That knowledge can support continuity when it is documented clearly.At the same time, relatives may live outside Alabama or have different levels of involvement. A shared process reduces dependence on one persons memory.A local provider meeting is an opportunity to discuss how communication will work across distance, schedules, and changing responsibilities.How to Get Started1. Define the Role You Need FilledExplain whether the need concerns special needs trust administration, a future arrangement, or review of an existing plan.2. Prepare a Question ListInclude communication, requests, reporting, fees, investment coordination, and representative changes.3. Speak With an AttorneyReview the proposed structure and the responsibilities of everyone involved.4. Contact Alabama Family TrustCall 205-883-8333 to discuss its process and request current information.5. Document the Agreed ResponsibilitiesKeep a concise record of contacts, procedures, and follow-up tasks.Expert TipAsk someone who was not involved in the meetings to read your responsibility sheet. If they cannot tell whom to contact or where records are kept, revise it before relying on it.Related Categories Fiduciary Services Special Needs Trusts Estate Planning
Financial & Payment FAQs for Seniors
1. How Do Seniors Pay for Long-Term Care?Seniors pay for long-term care through personal savings and income, long-term care insurance, Medicaid, Veterans benefits, home equity, and family support. Medicare does not cover most long-term custodial care, so planning early matters.Common Ways to Pay Personal savings and income: Retirement accounts, pensions, Social Security, and investments. This is the most common source of payment. Long-term care insurance: Policies that reimburse care costs after a waiting period. Medicaid: A joint federal and state program for people with limited income and assets. Veterans benefits: Programs such as Aid and Attendance for eligible veterans and surviving spouses. Home equity: Selling the home, renting it out, or using a reverse mortgage. Life insurance and annuities: Some policies can be converted, sold, or paired with long-term care riders. Family contributions: Informal care or shared costs, ideally documented in a care agreement. Why Planning Early HelpsInsurance is cheaper and easier to qualify for in your 50s and early 60s. Medicaid planning also involves a five-year look-back on asset transfers in most states, so last-minute moves can trigger penalties. 2. What Does Medicare Cover for Senior Care?Medicare covers short-term skilled nursing after a qualifying hospital stay, part-time home health care, hospice, and medically necessary services. It does not cover long-term custodial care such as help with bathing, dressing, or assisted living room and board.What Medicare Covers Skilled nursing facility care: Up to 100 days per benefit period after a qualifying hospital stay of at least three days. Days 1 to 20 are fully covered; days 21 to 100 require a daily copayment. Home health care: Part-time skilled nursing and therapy for people who are homebound and under a doctor's care. Hospice: Comfort-focused care for those with a terminal illness and a life expectancy of six months or less. Medical equipment: Items such as walkers and hospital beds when medically necessary. What Medicare Does Not Cover Long-term custodial care in a nursing home Assisted living costs Non-medical, ongoing home care such as housekeeping and personal care Most adult day care Medicare Advantage PlansSome Medicare Advantage (Part C) plans add limited benefits such as meal delivery, transportation, or in-home support. Coverage varies by plan, so review the details. 3. Does Medicaid Cover Assisted Living or Home Care?Medicaid covers nursing home care in every state, and many states also help pay for home care and some assisted living services through waiver programs. It usually does not pay for room and board in assisted living, and availability varies by state.How Medicaid Helps Nursing homes: Covered nationwide for eligible individuals. Home and community-based services (HCBS) waivers: Help with personal care, adult day services, and in some states assisted living services. State plan personal care: Some states offer in-home help through regular Medicaid. Assisted Living and Room and BoardEven when a state covers assisted living services, residents typically pay for room and board from their own income. Waiver slots can be limited, and waiting lists are common. 4. What Is Long-Term Care Insurance, and Is It Worth It?Long-term care insurance pays for services like home care, assisted living, and nursing homes once you cannot perform certain daily activities or have cognitive impairment. It can be worth it for people with moderate assets who want to protect savings, but premiums can be high and may rise.How It Works Benefit trigger: Typically needing help with two or more activities of daily living, or having cognitive impairment. Daily or monthly benefit: The maximum the policy pays. Benefit period: How long payments last, such as two to five years. Elimination period: A waiting period, often 30 to 90 days, before benefits begin. Inflation protection: An option that helps benefits keep pace with rising care costs. Traditional vs. Hybrid PoliciesTraditional policies are stand-alone and pay only for care, and premiums can increase. Hybrid policies combine life insurance or an annuity with a long-term care benefit, often with fixed premiums and a death benefit if care is never needed. 5. How Much Should I Budget Monthly for Senior Care?Monthly senior care costs vary widely by location and level of care. As a rough guide, home care can run a few thousand dollars, assisted living about $5,000 or more, and nursing home care $9,000 to $11,000 or more. Always get local quotes.Typical Monthly Cost Ranges (U.S., Approximate) Type of care Rough monthly cost Adult day program $1,500 to $2,500 Home health aide or homemaker (44 hours a week) $5,000 to $6,500 Assisted living $5,000 to $6,000 Memory care $6,000 to $8,000 or more Nursing home (semi-private to private) $9,000 to $11,000 Figures are approximate and drawn from industry cost surveys; local prices can differ significantly.How to Build Your Budget Assess care needs: Ask a doctor or care manager what level of help is required. Get local quotes: Call several providers and ask exactly what is included. List all income: Social Security, pensions, retirement withdrawals, and benefits. Add hidden costs: Medications, supplies, transportation, entrance or community fees, and annual rate increases. Plan for increases: Care needs and prices tend to rise over time. Build a cushion: Set aside an emergency fund for unexpected changes. 6. Are There Financial Assistance Programs Available?Yes. Seniors may qualify for Medicaid, PACE, Veterans benefits, Medicare Savings Programs, SSI, food and energy assistance, and local Area Agency on Aging services. Eligibility depends on income, assets, location, and care needs.Programs to Explore Medicaid: Covers long-term care for those who meet income and asset rules. PACE (Program of All-Inclusive Care for the Elderly): Combines medical care and support services for eligible adults who qualify for nursing home level care and live in a service area. VA Aid and Attendance: An added monthly benefit for eligible veterans and surviving spouses who need help with daily activities. Medicare Savings Programs: Help pay Medicare premiums and sometimes cost-sharing. Supplemental Security Income (SSI): Monthly payments for people with very limited income and resources. SNAP and LIHEAP: Help with food and home energy bills. Area Agencies on Aging: Local meals, transportation, respite, and caregiver support. National Family Caregiver Support Program: Counseling, training, and respite for family caregivers. Application Tips Gather ID, income statements, bank records, and medical documentation. Apply to several programs at once. Ask about waiting lists and re-apply or follow up regularly. Disclaimer: This content is for educational purposes and is not legal or financial advice. Consult an elder law attorney, financial planner, or benefits counselor about your situation.
Assets Under Management Strategies in Lancaster, PA
As you amass assets during the course of a lifetime, its easy to forget about how much you have and what its worth. Art in the attic, classic cars in storage, retirement accounts across multiple employers: if youre not aware of it all, your portfolio can lose value quickly. A financial advisor who offers assets under management services does so to protect your portfolio from the inevitable changes that your assets can undergo over time.Assets Under Management Strategies in Lancaster, Pa.The first asset you acquire in life, whether its a beatup car or a few shares of a brandnew company, is usually a gamechanging event. Its the first step on what is hopefully a journey toward a lucrative portfolio. Leveraging your assets to build your wealth is more than just financial jargon, its a path that can increase your wealth over time, so you can accomplish everything on your list.A financial advisor at a boutique retirement firm can take the time to get to know who you are and how you invest. At Bodnar Financial Group, Len Bodnar, RICP (R), is there to help his clients get a handle on their assets, so he can help you strategize them for better margins.For instance, a failing asset may need to be either sold or converted, depending on details behind the investment. A middlerange asset may need to be adjusted to optimize its performance. Finally, your strongest assets may need to be carefully watched, so a financial advisor can capitalize during the best of times and protect your wealth if and when it bottoms out.Theres a lot to be said for how assets change while you own them, and its not always easy to know when to cut and run from a property or when to stick with it. If you dont have the time or the inclination to spend on managing it all, the right financial advisor can help mitigate the stress. Its just one less thing to worry about as you get closer to your last day on the job.
Local Services By This Author
The Glenview at Pelican Bay
Independent Living 100 Glenview Place, Naples, Florida, 34108The Glenview at Pelican Bay offers the best coastal living in Naples, Florida. Nestled along a nature preserve, our senior living community blends small-town warmth and big-city vibrancy.Enjoy easy access to luxurious coastal amenities, including beachfront restaurants, world-class golf courses, tennis facilities, upscale shopping centers, beautiful parks, and cultural venues like the Naples Artis and Sugden Community Theatre.As an equity owner, you'll have exclusive access to Pelican Bay Beach via a short tram ride through the mangrove forest. Relax on the white sands, walk along the shore of a 3-mile private beach, stroll scenic boulevards, or enjoy a picnic while taking in the stunning sunsets. Have lunch or dinner in one of the four beach restaurants. The Glenview is Florida's only equity-ownership Lifecare senior lifestyle community. Come join us for the best of retirement living. Explore the nearby Pelican Bay Community Center, Waterside Shops, 5th Avenue & Historic 3rd Street, and the Ritz Carlton-Naples. With so much to offer, The Glenview at Pelican Bay is the perfect place to enjoy the coastal lifestyle in Naples.We look forward to helping you experience the ultimate luxury in coastal living.
GlenCare Home Care
Non-Medical 100 Glenview Place, Naples, Florida, 34108GlenCare Home Care, a division of The Glenview at Pelican Bay, provides personalized in-home care throughout Collier and Lee Counties. Whether you need a helping hand with daily activities or more advanced clinical support, our goal is to help you or your loved one remain safely and comfortably at home.GlenCare offers four levels of care: Companion Care, Home Health Aide Care, Skilled Nursing Care and Memory Care. Every client is supported by a dedicated Nurse Case Manager who helps oversee care, coordinate services and provide an added level of clinical oversight.For those with more complex needs, GlenCare offers up to 24-hour nursing care, along with a nurse on call 24/7. All caregivers undergo a Level 2 background check, and clients benefit from a consistent care team they can get to know and rely on.GlenCare has been recognized as a Best of Florida Regional Winner for five consecutive years and has earned a 100% Deficiency-Free Rating from the State of Florida.A change in health doesnt have to mean a change in address. Call GlenCare Home Care today at 239-977-8017 to schedule a complimentary in-home consultation.
The Glenview at Pelican Bay
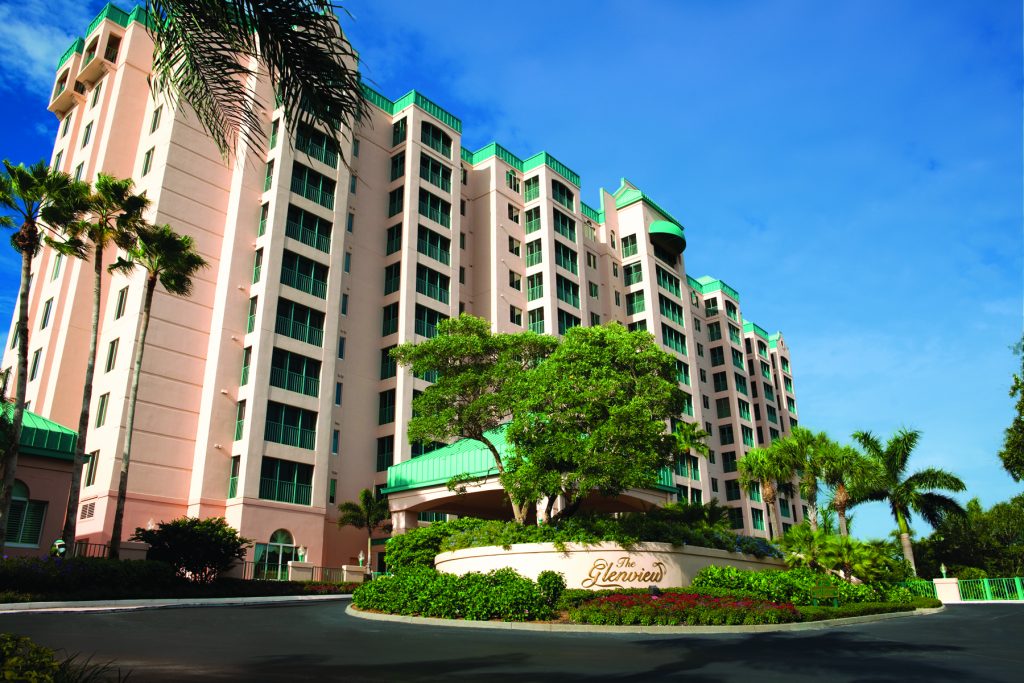
Housing - Other Types 100 Glenview Place, Naples, Florida, 34108The Glenview at Pelican Bay offers the best coastal living in Naples, Florida. Nestled along a nature preserve, our senior living community blends small-town warmth and big-city vibrancy.Enjoy easy access to luxurious coastal amenities, including beachfront restaurants, world-class golf courses, tennis facilities, upscale shopping centers, beautiful parks, and cultural venues like the Naples Artis and Sugden Community Theatre.As an equity owner, you'll have exclusive access to Pelican Bay Beach via a short tram ride through the mangrove forest. Relax on the white sands, walk along the shore of a 3-mile private beach, stroll scenic boulevards, or enjoy a picnic while taking in the stunning sunsets. Have lunch or dinner in one of the four beach restaurants. The Glenview is Florida's only equity-ownership Lifecare senior lifestyle community. Come join us for the best of retirement living. Explore the nearby Pelican Bay Community Center, Waterside Shops, 5th Avenue & Historic 3rd Street, and the Ritz Carlton-Naples. With so much to offer, The Glenview at Pelican Bay is the perfect place to enjoy the coastal lifestyle in Naples.We look forward to helping you experience the ultimate luxury in coastal living.