Medicare Minute: Medicare and Immigration
Area Agency on Aging
For more information about the author, click to view their website: Area Agency on Aging
Nov 12, 2024

Email US
Click to Email Us
You don’t have to be a U.S. citizen to be eligible for Medicare. If you are not a U.S. citizen, but are lawfully present, you may be able to get Medicare coverage, depending on your situation. There are two ways non-citizens can be eligible for Medicare. Let’s learn how.
Do you qualify for Federal Disability or Retirement benefits?
You will qualify for Medicare if you qualify to receive or currently receive:
- Social Security retirement benefits
- Railroad Retirement Benefits (RRB)
- Social Security Disability Insurance (SSDI)
Regardless of your citizenship or how long you have lived in the U.S., if you qualify for these benefits, you qualify for Medicare.
These benefits are tied to your U.S. work history, or the work history of a spouse or sometimes family member. Even if you have not been in the U.S. long or have not worked long enough, you may still qualify based on your spouse’s work history or benefits.
If you aren’t sure if you qualify for these benefits or have enough work history, contact the Social Security Administration (SSA).
*If you’re eligible and ready to enroll, or have questions about Medicare eligibility and enrollment, you should contact SSA. You can call the national helpline (800-772-1213), go to www.ssa.gov, or visit your local branch to enroll.
Are you a lawful permanent resident who has lived in the U.S. for 5+ years?
If you meet both of these requirements—you are a lawful permanent resident and have been in the
U.S. for 5 years prior to enrolling in Medicare—you are eligible for Medicare:
- Lawful Permanent Residents (LPRs) – LPRs are non-citizens who are allowed to live in the U.S. indefinitely. To get LPR status and a “green card,” you must apply with the U.S. Citizenship and Immigration Services.
- Five-Year Residency Requirement – The five years begins the day someone arrives in the U.S. with the intention of establishing a home, not just visiting. You can still leave the U.S. temporarily, meaning for no more than six months.
*Use the National Immigration Legal Services Directory to find immigration service providers in your area. You can find the directory at www.immigrationadvocates.org/legaldirectory/.
Be aware of people trying to steal your Medicare number
Medical identity theft happens when someone steals your personal information and uses it to get medical treatment or equipment and bills your insurance for it. Healthcare companies can try to reach people in various ways, like television commercials, radio ads, events, mailings, phone calls, and text messages. Some of them may be legitimate, but some could potentially be scammers trying to steal your personal and/or medical identity information.
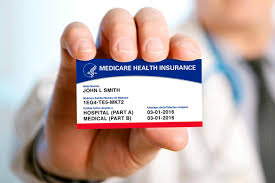
- Protect your Medicare and/or health ID number and only share it with your health care provider or trusted person. Protect your Medicare card like you would a credit card. Scammers have various ways of stealing someone’s Medicare number and other personal information.
- Detect medical identity theft by reading your Medicare statements often. If you see services or prescriptions that you didn’t know about or receive, your Medicare and/or health ID number could be considered “compromised.”
- Report potential medical identity theft to your local SMP. It can affect your medical and health insurance records, and your ability to receive services or equipment in the future when it is medically needed. It can also lead to incorrect costs for both you and the Medicare program. Reasons to report:
- You gave out your Medicare and/or health ID number:
- Over the phone or internet to someone offering additional benefits, durable medical equipment, genetic testing, COVID-19 testing/supplies, back braces, etc.
- At a fair or other gathering as a check-in or to receive free services
- In response to a television or radio commercial, Facebook ad, postcard, or print ad requesting a Medicare number
- You are contacted by a debt collection company for a provider bill you do not owe
- You received boxes of bracers, testing kits, or other medical supplies in the mail that you did not request
- A Medicare and/or a Medicare Advantage plan denies or limits your coverage or benefit because of a medical condition you do not have
- You gave out your Medicare and/or health ID number:
Download the full handout with local SHIP/SMP contact information to resources and directories (pdf).
For more information call 866-413-5337 or email [email protected] for assistance in Southwest Florida.
The Medicare Rights Center is the author of portions of the content in these materials but is not responsible for any content not authored by the Medicare Rights Center. This document was supported, in part, by grant numbers 90SATC0002 and 90MPRC0002 from the Administration for Community Living (ACL), Department of Health and Human Services, Washington, D.C. 20201. Grantees undertaking projects under government sponsorship are encouraged to express freely their findings and conclusions. Points of view or opinions do not, therefore, necessarily represent official Administration for Community Living policy.
Other Articles You May Like
What If Your Senior Client Owns a Luxury Home?
For professionals serving seniors, a home can sometimes be the biggest piece of the transition puzzle.But what happens when that home isn't an ordinary property?What if your client owns a $1 million, $2 million or multimillion-dollar luxury or waterfront home?A senior may be downsizing, transitioning to independent or assisted living, moving closer to family, settling an estate, or simply deciding that maintaining a large property no longer makes sense.For senior living professionals, elder law attorneys, estate planners, financial advisors, care managers, move managers and other professionals helping with that transition, there is an important option worth knowing about:The homeowner may be able to sell a luxury property privately and directly, without first putting it on the public market.Why Can Selling a Senior's Luxury Home Be Different?Luxury and waterfront properties can present challenges that aren't always present in a typical home sale.The property may be a waterfront estate on Casey Key, a residence on Bird Key, a condominium overlooking Sarasota Bay, or a distinctive home on Siesta Key or Longboat Key.The owner may have lived there for decades.The home may contain valuable possessions, artwork and deeply personal belongings. It may need updating. Adult children may live hundreds of miles away. And the family may already be coordinating a significant life transition.For some homeowners, maximum exposure to the real estate market is the priority. In that situation, publicly marketing the property may make sense.But other seniors have very different priorities:Privacy. Simplicity. Certainty. Flexibility.They may not want strangers repeatedly touring their home.They may not want photographs of their home's interior and possessions published online.They may not want to renovate, stage or prepare the property for the luxury market.And they may not want their move dependent upon months of marketing, inspections and a buyer obtaining financing.For those homeowners, a private direct sale may be another option worth considering.Can a Senior Sell a Luxury Home Without Publicly Listing It?Yes.A luxury homeowner can explore a direct sale without first broadly marketing the property.Private Luxury Home Sales considers select luxury, waterfront and distinctive properties throughout Sarasota and Florida's Gulf Coast for direct purchase. A homeowner can request a confidential property review before deciding whether a private sale or broader market exposure better fits their objectives.This can allow an owner to explore an offer without first going through the traditional process of preparing and publicly marketing the property.Why Might Privacy Matter to an Older Luxury Homeowner?For some affluent seniors, privacy isn't simply a preference.It can be an important part of the selling decision.Imagine a homeowner who has spent 25 or 30 years in the same waterfront residence.Inside may be family photographs, artwork, collections, jewelry, antiques and other personal possessions.A traditional luxury marketing campaign can involve professional photography, video, aerial photography, online advertising and numerous people entering the property.Some homeowners are completely comfortable with that exposure.Others aren't.A private direct sale provides another route. When Private Luxury Home Sales evaluates a property for potential direct purchase, broad public marketing isn't necessary merely to consider the home. For a senior who values discretion, that difference can matter.Does the Luxury Home Need to Be Renovated First?Not necessarily.One of the biggest misconceptions surrounding high-value real estate is that every luxury property must be extensively updated before it can be sold.A longtime owner may have an exceptional property in an exceptional location while the kitchen, bathrooms, flooring or other features are dated.Preparing that property for the retail luxury market could potentially involve substantial renovations, contractors, staging and months of work.A direct buyer evaluates the property differently.Private Luxury Home Sales considers properties as-is, including residences requiring updates or significant renovation. That can be particularly relevant when an older homeowner or the homeowner's family doesn't want to oversee a major renovation before selling.Which Senior Clients Might Benefit From Knowing About This Option?You don't need to determine whether a private sale is right for your client.You simply need to recognize situations where having another option could be valuable.Consider the homeowner who is:Downsizing from a large luxury residence. Transitioning into independent or assisted living. Moving closer to adult children. Managing a home after the death of a spouse. Selling an inherited luxury or waterfront property. Handling a property through an estate or trust. Living out of state while responsible for a parent's Florida property. Facing substantial deferred maintenance or renovation. Concerned about privacy and public exposure. Looking for greater certainty about the timing of the sale. Those are situations where understanding both the public-market and private-sale alternatives can help a family make a more informed decision.What's the Most Important Question to Ask Your Client?There is one question professionals can ask that may reveal a great deal:What matters most to you when the home is sold?Listen carefully to the answer.Is it achieving maximum exposure to the marketplace?Maintaining privacy?Avoiding repairs?Controlling the closing date?Avoiding repeated showings?Reducing uncertainty?Making the transition as simple as possible?There isn't one correct answer.The homeowner's priorities should help determine which selling strategy deserves consideration.Private Sale vs. Traditional Luxury ListingA private direct sale and a traditional luxury listing serve different objectives.Traditional public marketing provides broader exposure to potential buyers and may create greater price discovery and competition.A private direct sale can emphasize privacy, simplicity, convenience, an as-is transaction and greater certainty about the process.Neither approach should automatically be assumed to be right for every senior homeowner.The value to your client comes from understanding that there is more than one option.One More Resource for Your Professional ToolboxProfessionals serving seniors don't need to become real estate experts.But they are frequently the first people to recognize a problem.A senior living advisor may hear:Mom is ready to move, but we don't know what to do with the house.An elder law attorney may be helping a family deal with an estate containing a multimillion-dollar residence.A move manager may discover that preparing a 4,000-square-foot waterfront home for the market is becoming overwhelming.A financial advisor may have a client whose largest single asset is a luxury property.Knowing that a confidential direct-sale option exists gives you another resource to share with the family.Private Luxury Home Sales specializes in select luxury, waterfront and distinctive properties throughout Sarasota and Florida's Gulf Coast. Its Seniors Blue Book profile specifically includes waterfront estates, Gulf and bayfront homes, boating properties, inherited luxury homes, second homes and properties requiring substantial updating. When You Encounter the Right ClientIf you're working with a senior or family who owns a luxury or waterfront property, consider asking one additional question:Would they like to understand their private-sale option before deciding how to sell the property?There is no obligation to accept an offer simply because the property is evaluated.Sometimes the homeowner will determine that traditional market exposure is the better choice.Sometimes privacy, simplicity and certainty will matter more.Either way, knowing the options before making the decision is valuable.Private Luxury Home SalesSarasota & Florida Gulf CoastPrivate Direct As-Is Close on Your Timeline For more information, please contact Jeff Nemeth at 941-202-6957
When to Consider Knee Replacement Surgery
Life can take you anywhere until knee arthritis pain slows you down. Whether its walking, golfing, traveling, or playing with your grandkids, the activities you love shouldnt be limited by chronic knee pain. So, whats the solution?For many, knee replacement surgery is an effective option to reduce pain from arthritis and continue to live an active life. The great news is that there are several different types of knee replacement surgery, as well as advanced surgical techniques that can even speed up your healing.Whether you're just beginning to explore treatment options or preparing for surgery, our board-certified orthopedic surgeons at AdventHealth can help you understand the different types of knee replacement procedures and what to expect throughout your recovery journey.Who Needs Knee Replacement SurgeryThe leading cause of knee replacement surgery is osteoarthritis, a degenerative condition that gradually wears down the cartilage in the knee joint. As the damage progresses, pain and stiffness can worsen over time, making everyday activities increasingly difficult.Common symptoms of knee osteoarthritis include:Gradual knee pain that worsens with activityKnee stiffnessKnee swellingPain after extended sitting or restingKnee pain that continues to get worseIf you have osteoarthritis, your doctor will start by offering the most conservative treatments to alleviate your pain.Some initial treatments for knee osteoarthritis might include:Weight lossPhysical therapyAnti-inflammatory medicationsCortisone injectionsViscosupplementation or gel injectionsIf these strategies are not helpful and your condition worsens, your doctor might offer knee replacement surgery as a promising option to reduce pain and return to the active life you love again.Types of Knee Replacement SurgeryNot every knee replacement is the same. While a total knee replacement restores the entire joint with an artificial implant, some patients may qualify for a partial knee replacement, which replaces only the damaged portion of the knee and preserves more of the natural joint.What to Expect Before Knee Replacement SurgeryOnce you and your surgeon have worked together to decide the right treatment plan for you, youll likely need to make an appointment with your primary care doctor to assess your general health and clear you for surgery. You may also need an evaluation and clearance from your dentist.Once this step is completed, youll be able to schedule your knee replacement surgery appointment. You may also need a CT scan of your knee so your surgeon can more precisely customize your replacement to most naturally fit your knee anatomy and movement.In preparation, make sure you have someone who can take you to your surgery appointment and be there as your caregiver after the procedure. This person will be able to drive you home, get any prescribed medications and help maintain your comfort after surgery.Your medical team might also advise you to stop taking certain medications (such as blood thinners, NSAIDs like aspirin or other supplements) up to a week before your surgery date. Youll also be advised to fast prior to surgery. In most cases, you cant have anything to eat or drink (including water) after midnight on the night before your surgery.Some other ways to prepare your home ahead of time include:Setting up your comfortable space for resting and elevating your legClearing the floor and pathways of fall and trip risks such as rugsHaving ice packs frozen and ready for when you return homeWhat to Expect During Knee Replacement SurgeryYour exact recovery will depend on exactly what type of procedure you are having as well as your overall health. Some patients may have outpatient knee replacement surgery and go home the same day. This is especially true for minimally invasive surgical procedures. Other knee replacement procedures may require you to stay in the hospital from one to four days.On the day of surgery, you'll be prepped for the procedure and given anesthesia. Most knee replacement surgeries take about one to two hours to complete. Afterward, you'll recover under close observation before receiving instructions on pain management, medications, physical therapy and follow-up care. To help you safely regain mobility, you'll likely use crutches or a walker during the early stages of recovery.What to Expect After Knee Replacement SurgeryYour surgeon will provide you with a follow-up appointment and a prescription for physical therapy. Physical therapy after surgery is essential to regain your strength and get optimal results from your knee replacement. Physical therapy usually begins immediately after surgery and may continue for up to six weeks.After roughly six weeks, most knee replacements are up to 80% healed. After three months, most achieve 90% healing and by one year, most patients are back to their active lifestyle with nearly complete knee function and comfort.Whole-Person Orthopedic CareOur orthopedic experts offer advanced knee replacement options that put your whole-health first. To learn more about the services we offer, visit AdventHealthPortCharlotte.com.
2027 Medicare Annual Enrollment is here!
VERY IMPORTANT: Regarding Medicare it is illegal for an insurance agent to call, text, e-mail, knock on your door, hang anything on your door or vehicle or approach you without your consent. If they do ask for their National Producer Number NPN, and you will hear a click and removed from their list. If they dont hang up, get their number and report them to Medicare. There is so much fraud where people are being switched to plans that they never approved or they were miss led. Shop local, do background checks before you give anyone your personal information. You can google them, google reviews, check their Facebook, etc. Make sure that if you are working with someone you can call them personally if you have any questions or concerns. Medicare Annual Enrollment is October 15-December 7th for January 1st, 2027, effective. What can be changed at this time is Medicare Part D Drug Plans and Medicare Part C (Advantage Plans). You should have received your Notification of Change from your current insurance plan. This outlines the current year to the new year changes, as an example if your specialist provider costs $20 now it might say $35 in 2027 (no correlation just an example). Medicare Part C / Advantage Plans, most carriers have raised out of pocket limits and copays along with decreased extra value benefits for 2027. Annually Medicare Advantage Plans make changes. They must all include the same features as Original Medicare but not at the same cost share. They can have a premium, Medical and or Prescription deductible, copays and coinsurance can change. Extra Value such as Vision, Dental, Over the Counter, Part B Give Back, transportation, etc. can all change or be eliminated. Medicare sets the annual in-network out of pocket maximum; in 2026 it is $9,250 for in-network and $13,900 out-of-network services combined (2027 this will increase). However, individual insurance plans may set lower limits. The old saying if it is not broken do not fix it DOES NOT apply to Annual Enrollment. Every year I see many people that have not checked/compared their current plan to what is new. I have saved so many people hundreds and in many cases thousands of dollars. You should be working with a broker that represents many insurance companies. Make sure you check them out, especially if you are going to allow someone in your house. I recommend meeting in their office. For me we represent most insurance carriers in our area and carrying all their literature with me is almost impossible. We use three large screens so that our clients can clearly see and compare the differences between the plans. The minimum information always needed is all your doctors, medications: names, milligrams, and dosage. We load your current plan and then compare it to all the other companies in your area. What companies have all your doctors, the price for your medication normally makes a significant difference. Then the Extra Value is what is most important to you. We do NOT CHARGE for your review and if warranted to change your insurance plan. Ethics is most important and if you are on the best plan we will tell you, plus you can see for yourself. If your plan was CANCELLED/DROPPED for 2027, you have a guaranteed issue into a Medigap/Medicare Supplement. This is huge and very important, know your options!Medicare Seminars they are good for general information. A one-to-one appointment where you can dive into your doctors and medication is best, plus you can then compare other companies in one place. Medicare Part D most insurance carriers have taken away insurance agents ability to help you with your Part D Only drug plans this does not apply to most Advantage plans, standalone drug plans as well as Advantage Plans, you wont have to pay more than $2,400 in out-of-pocket drug costs, which include deductibles, co-pays, coinsurance. It is especially important to check your plans formulary as medication must be in formulary to be capped. 2027 RX deductible will be capped at $715.00. As a reminder the cost of the plan is not as important as the cost plus your medications, that is what you look at, the total cost. It is important to know what the medication is used for to determine if it is covered by the plan. Example Wycovy may be covered but to be covered it must be used for certain heart conditions or diabetes, Medicare does not cover weight lose medications at this time. As a reminder if you choose NOT to ENROLL in a Part D drug plan and in later years you want one you will have to wait for Annual Enrollment and then you will assed a penalty for every month you did not have a drug plan, that penalty will last for the REST OF YOUR LIFE! When you turn 65 you are eligible for Medicare, once you have worked 40 quarters roughly 10 years there is no cost for Medicare Part A. Part A covers Hospitals, Skilled Nursing, Home Health & Hospice. Medicare Part B you can choose to take at 65, or you can hold off if you are still working and have credible coverage. If you do not have group health insurance that is considered qualified, and then you want Medicare you would have a late enrollment penalty for each month you did not have Part B & Part D, and that penalty will last for the rest of your life. Part B covers doctors, imaging, blood work, ambulance, durable medical equipment, etc. Part D is a Medicare Drug Plan and covers medications. During your initial enrollment period it is especially important to understand your options! Medicare Supplements/Medigap Plans are NOT guaranteed issues; you may need to medically qualify. You can purchase a Medigap Plan during your 1st 6 months on Medicare Part B without medical underwriting. There are a lot of things you need to know. Again, work with an agent you can trust! Especially important: when you move you need to know your options. Can you keep the same plan? Do you need to make a change and what does that look like? Logical Insurance Solutions is a SWFL Insurance Broker that works with most of the insurance carriers in your area, we are happy to help you through the maze. We offer Free Medicare Seminars, Personal Appointments & Virtual appointments. Please e-mail [email protected] to register or call 239-362-0855 for dates. Medicares website is www.Medicare.gov. www.Logicalinsurance.com 239-362-0855 [email protected] Ulla-Undine Merritt (Dee) National Producer Number (NPN) 8853366
Local Services By This Author

Area Agency on Aging for Southwest Florida
Food Resources 2830 Winkler Avenue, Suite 112, Fort Myers, Florida, 33916The Area Agency on Aging for Southwest Florida (AAASWFL) is a nonprofit organization serving older adults (age 60-up) and adults with disabilities. We serve Charlotte, Collier, DeSoto, Glades, Hendry, Lee and Sarasota counties. AAASWFL is committed to connecting older adults and adults with disabilities to resources and assistance for living safely with independence and dignity.AAASWFL is also the states designated Aging and Disability Resource Center for Southwest Florida. We provide information and resources for seniors and adults with disabilities. We also help their families and caregivers. AAASWFL can connect you with local resources like elder care, adult day care, housing assistance, home care, meals, housekeeping, legal assistance, personal care, and even volunteer opportunities.Providing Long-Term Care (LTC) services to Floridas most vulnerable citizens is a multi-agency effort. The Agency for Health Care Administration (AHCA) administers the Statewide Medicaid Managed Care (SMMC) Long-Term Care program, sets coverage policy, and gets those eligible for services enrolled in a LTC plan. The Department of Elder Affairs (DOEA) is responsible for determining medical eligibility and level of care needed. We are one of eleven regional Area Agencies on Aging in the state of Florida. Nationwide, there are more than 600 Area Agencies on Aging serving elders and adults with disabilities.Please contact the Area Agency on Aging for Southwest Florida if we can be of assistance to you, a friend or a family member!The AAASWFL Elder Helpline is available between 8:00 am-5:00 pm Monday through Friday: 866-413-5337 (866-41-ELDER)Contact Phones:Telephone: 239-652-6900FAX: 239-652-6989Toll Free: 866-413-5337 (in the State of Florida)Postal address:Area Agency on Aging for Southwest Florida2830 Winkler Avenue, Suite 112Fort Myers, FL 33916Hours of Operation:Monday-Friday: 8am 5pm
Elder Helpline- Fort Myers
Elder Abuse Prevention 15201 N Cleveland Ave, Ste 1100, N Fort Myers, Florida, 33903Area Agency on Aging for Southwest Florida
Senior Organizations & Services 2830 Winkler Avenue, Suite 112, Fort Myers, Florida, 33916The Area Agency on Aging for Southwest Florida (AAASWFL) is a nonprofit organization serving older adults (age 60-up) and adults with disabilities. We serve Charlotte, Collier, DeSoto, Glades, Hendry, Lee and Sarasota counties. AAASWFL is committed to connecting older adults and adults with disabilities to resources and assistance for living safely with independence and dignity.AAASWFL is also the states designated Aging and Disability Resource Center for Southwest Florida. We provide information and resources for seniors and adults with disabilities. We also help their families and caregivers. AAASWFL can connect you with local resources like elder care, adult day care, housing assistance, home care, meals, housekeeping, legal assistance, personal care, and even volunteer opportunities.Providing Long-Term Care (LTC) services to Floridas most vulnerable citizens is a multi-agency effort. The Agency for Health Care Administration (AHCA) administers the Statewide Medicaid Managed Care (SMMC) Long-Term Care program, sets coverage policy, and gets those eligible for services enrolled in a LTC plan. The Department of Elder Affairs (DOEA) is responsible for determining medical eligibility and level of care needed. We are one of eleven regional Area Agencies on Aging in the state of Florida. Nationwide, there are more than 600 Area Agencies on Aging serving elders and adults with disabilities.Please contact the Area Agency on Aging for Southwest Florida if we can be of assistance to you, a friend or a family member!The AAASWFL Elder Helpline is available between 8:00 am-5:00 pm Monday through Friday: 866-413-5337 (866-41-ELDER)Contact Phones:Telephone: 239-652-6900FAX: 239-652-6989Toll Free: 866-413-5337 (in the State of Florida)Postal address:Area Agency on Aging for Southwest Florida2830 Winkler Avenue, Suite 112Fort Myers, FL 33916Hours of Operation:Monday-Friday: 8am 5pm