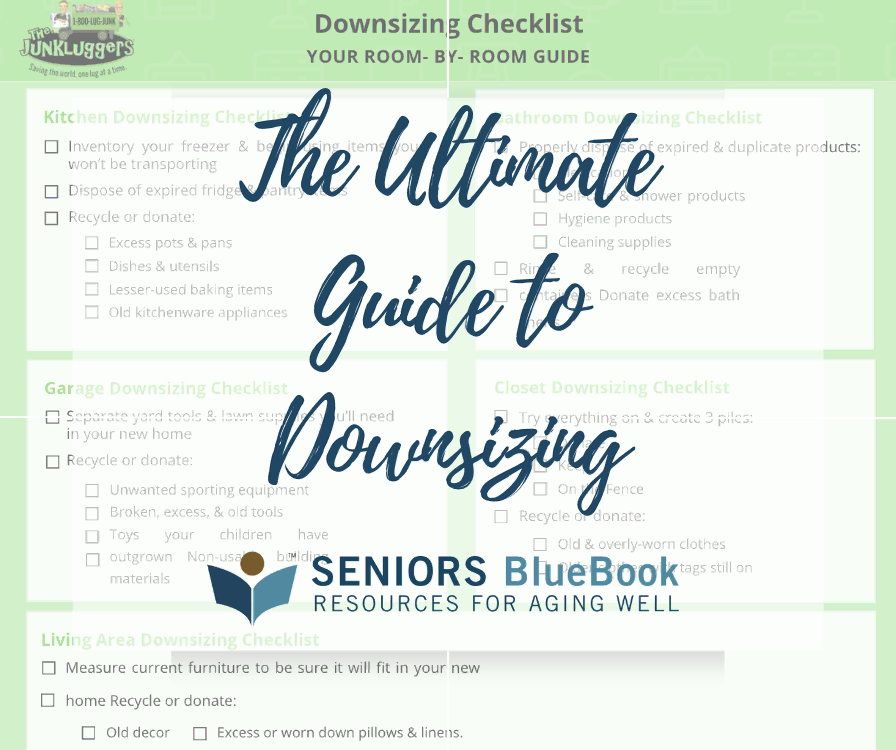
The Ultimate Guide to Downsizing & The Downsizing Checklist
The Junkluggers
For more information about the author, click to view their website: The Junkluggers DFW
Jul 05, 2022

Email US
Click to Email Us
Check out The Junkluggers Ultimate Guide to Downsizing! We'll guide you through the process.
Are you looking to downsize your home but you’re not sure where to start? We’ve created this helpful guide full of successful downsizing strategies to keep you focused and organized.
Here at The Junkluggers, we specialize in downsize and declutter projects and we’re here to offer our services to help you discard the items you’ve decided you no longer need. Give us a call, and be greeted with top-notch customer service that often offers same or next-day appointments.

Questions to Prepare for a Move or Downsize
When moving, you can understand your new space by asking all the right questions. It will become easier to make decisions about what to keep and what to donate! Your new space should represent you but also feel like a fresh start. Be sure to keep the following things in mind when moving:
How many bedrooms will you have?
If you currently have three bedrooms that act as your room, a guest room, and an office but your new space will only leave you with two bedrooms, you should consider what room you would like to downsize. If you would rather keep your office and not the guest bedroom, then it becomes the perfect opportunity to get rid of the bulky guest bedroom furniture that you’ll no longer need. Furniture and mattress removal just happens to be our specialty.
What is the square footage?
Optimizing your space is important when moving. If your new space is smaller than your current one, it may benefit you to keep your shelving and storage for your books or knick-knacks. Additionally, you might want to consider swapping out your large sectional, 8 person dining room table, or other large furniture for smaller items that suit both you and your space better.
Is there any built-in storage?
When looking at your next new space, be mindful of the storage that comes with it. If you have limited kitchen storage but a large bedroom closet, consider what types of items you’ll need to trim down. Storage will become a key factor in downsizing
Do you have any extra space?
Having a garage, shed, attic, or any additional space will play an important part when deciding what will go and what will stay. If you currently have a garage that you keep all your outdoor stuff in, but no garage in your new place, you might consider sifting through equipment to determine if you’ve used it recently or if you’ll use it soon in the future.
Top 7 Downsizing & Decluttering Tips
1. Create a timeline
A helpful way to stay on task and organized is to create a timeline of when you would like to be done and important milestones that may guide you on your way. Mark when you want certain areas of the house to be decluttered and when you would like the stuff you no longer need either donated or thrown away. For example, if you choose to downsize your closet in one month, here’s how you can set timely goals for each week.
Week 1:
- Sort through all outside spaces (garage, shed, etc)
- Try on all clothes and donate 25%
- Create your 3 piles of keep, throw away and donate
Week 2:
- Get rid of duplicates in kitchen (spatulas, ladles, etc)
- Eliminate old and stained sheets, pillow cases, and expired products
- Schedule an appointment with The Junkluggers to remove bulky items, donations, and furniture
Week 3:
- Throw away or scan old paperwork, school projects, and other paper items
- Pack items for new house
Week 4:
- Removal of bulky items, donations, furniture
- Moving day
2. What to keep, what to toss
If you’re having trouble looking through things and throwing them away, do the 6 and 3 rule. If you haven’t used the item in the last 6 months and won't use it in the next 3 months, discard it or donate it. This excludes seasonal things such as a lawnmower or winter jackets, unless you’re moving into a place that does not have a yard or winter! Have sorting boxes or piles that designate what will be donated, what will be thrown away, and then pack the rest of what you’re choosing to keep.
3. Go through expired products
Expired products in the bathroom, kitchen, or hallway closet will always take up unwanted space in your new home! Sort through lotions, cleaning products, spices, facial products, and other items. You must remember you cannot donate these products if they are expired or open, and it’s best to responsibly dispose of them.
4. Start in lesser-used places
Don’t forget about spaces that you don’t see or use every day! Your garage, attic, and storage shed can accumulate things quickly and be forgotten just as fast. If you have storage bins of sporting goods that haven’t been used in years, it’s time to donate.
Pro Tip: Momentos from old school projects might be hard to get rid of but a good rule of thumb to keep in mind is to only save one or two things from each collection or year.
5. Sort through furniture and large items
We all have that piece of furniture that is rarely used and takes up space. Is it an entryway table that collects old mail and paperwork? A hutch that holds nothing more than a vase? You may even consider getting rid of the guest bed that has only been used once or twice. Whatever it may be, finding the pieces of furniture that you don’t use or will no longer need is a great way to freshen your space and declutter your home.
6. Refresh your kitchen space
The kitchen can be one of the most difficult areas to declutter as you can almost always find a reason to keep something. However, this can also be a golden area to get rid of the most stuff. If you only use 2 pots but have 4 in your cabinet space, or have a bread pan sitting in the corner that has never been used, these are an example of items to donate. Think about what you use daily and what is rarely used.
7. Closet Declutter
Depending on who you are, your closet might be jam-packed with clothes, shoes, belts, and other accessories that have only been worn once or twice. When downsizing your closet think about the items of clothing and accessories that stand out to you. The 6 and 3 rule can also apply here. If you haven’t worn it in 6 months and don’t plan to wear it in the next 3 months (excluding weather-specific items) then it’s time to donate.
Downsizing Tips For Seniors
There will come a time in your life where, as you grow older, you may inevitably have to downsize for a myriad of reasons that may happen slowly or all at once. With The Junkluggers, you won’t have to lift a finger in disposing of unwanted items, hauling things off, or donating your possessions.
- Start with small rooms and items
You will find it helpful to start in smaller areas of your home that hold fewer momentos attached to it such as the hallway closet or the office. Spaces like attics or garages that hold old projects, decorations, and other things can be difficult to sort through.
- Eliminate rooms you won’t have in your new home
If you find yourself moving into a one-bedroom home, getting rid of the excess belongings in the guest bedrooms and office will help you adjust quickly to your new space. Go through tools and landscaping items you may not need or won’t have storage for. If you can, visit where you will be living to help you visualize what you can and cannot keep.
- Preserve Your Collections
The hardest part about moving into a smaller space may be reducing years worth of collections and other hobby items. To downsize these things, pick out a few pieces that are your favorite and keep only a few from the entire collection. If you find that you will have to donate all of these items, take photos of them first and print them out. You can then place these in a photo album to display in your new home.
- Allow time for memory lane
Start early in your process of decluttering and downsizing. Getting rid of your possession is hard and you’ll likely be going through many different things that have memories attached. Allow yourself to experience memory lane and reminisce about those times.
Advantages of Downsizing Your Home
Now that you’ve decluttered your home, you can sit back and relax! Cleaning will become easier with minimal things to dust and spray down. You’ll feel the weight off your shoulders of having to maintain a large home with many things to sort and keep track of.
Allowing yourself to keep up with a lifestyle of minimal things that you may not need will help you refrain from buying excess things. Be mindful of your new space and enjoy the benefits of a decluttered and downsized home.
Hacks to organizing your home aren’t always straightforward and simple but the rewards to downsizing can make all the difference in your space. Remember that you aren’t alone in this process and Junkluggers is here to help. We’ll offer a stress-free experience to take away what you want to get rid of. Give us a call today to book your free onsite estimate! Mention code: 25BLUEBOOK
Other Articles You May Like
Downsizing or Selling Your Home in Retirement: Tax Implications to Kno
Downsizing or Selling Your Home in Retirement: Tax Implications to KnowSelling the family home is one of the biggest financial decisions many people make in retirement whether you're downsizing something smaller, moving closer to family, or relocating somewhere warmer. Before you list the house, it's worth understanding how the sale could affect your taxes.The Good News: Most Home Sellers Owe Little or No TaxUnder federal tax law, homeowners can exclude a significant amount of profit from capital gains tax when they sell a primary residence: Up to $250,000 in gain excluded for single filers Up to $500,000 in gain excluded for married couples filing jointly These limits have stayed the same since 1997 they aren't adjusted for inflation but for most sellers, especially those who haven't owned an especially high-value home for decades, they're enough to eliminate the tax bill entirely.Do You Qualify for the Full Exclusion?To claim the exclusion, you generally need to pass two tests: Ownership test: You owned the home for at least 2 years during the 5-year period before the sale. Use test: You lived in the home as your primary residence for at least 2 years during that same 5-year period. For married couples claiming the full $500,000 exclusion, both spouses need to meet the use test, though only one spouse needs to meet the ownership test. If only one spouse meets the use test, the exclusion drops to $250,000.If you don't fully meet the two-year requirements but had to sell due to a job change, health issue, divorce, or similar unforeseen circumstance, you may still qualify for a partial exclusion.How Your Gain Is Actually CalculatedThis is where record-keeping pays off. Your taxable gain isn't your sale price it's your sale price minus your cost basis, which includes: What you originally paid for the home The cost of qualifying capital improvements over the years (a new roof, an addition, major renovations not routine repairs or maintenance) Selling costs, such as agent commissions Every dollar documented improvement raises your basis and lowers your taxable gain. If you've owned your home for decades, digging up old receipts and records for major projects can make a meaningful difference sometimes the difference between owing tax and owing nothing at all.What Happens If Your Gain Exceeds the ExclusionIf your profit is larger than your exclusion amount, the excess is taxed as a long-term capital gain (assuming you owned the home more than a year), generally at 0%, 15%, or 20% depending on your overall taxable income. For higher-income sellers, an additional 3.8% Net Investment Income Tax may also apply above certain income thresholds. This is more common than it used to be for retirees who've owned a home for many years in an area where property values have risen substantially.A Few Other Situations Worth Knowing Home office deductions: If you claimed depreciation on a home office in past years, that portion is generally "recaptured" and taxed differently when you sell, separate from the main exclusion. Selling a second home or rental property: The primary residence exclusion generally doesn't apply to vacation homes or rental properties. Different rules, including possible depreciation recapture, come into play. Inherited homes: If you're selling a home you inherited, the property typically receives a stepped-up basis to its fair market value at the time of the original owner's death which can significantly reduce or eliminate taxable gain compared to using the original purchase price. Using the exclusion more than once: The exclusion isn't a one-time benefit. You can generally use it again for a future home sale, as long as you meet the ownership and use tests again and haven't claimed it on another sale within the prior two years. Why Planning Ahead MattersThe tax side of selling a home is often simpler than people expect, especially with the exclusion in play but assumptions can be costly in either direction. Some retirees overestimate their tax exposure and hesitate to sell when they'd actually owe little or nothing. Others underestimate it, especially with a long-held, appreciated home, and are surprised by a gain above the exclusion. Reviewing your specific numbers before you list the home, rather than after the sale closes, gives you room to plan.Thinking about downsizing or selling a home in retirement? Contact Zunic Advisory Services to walk through what the sale could mean for your taxes.
Paying for Senior Care When One Spouse Moves
Few transitions in life feel as difficult as the moment when one spouse needs to move to a care community while the other remains at home. Perhaps one partner is living with advanced dementia and needs the security of memory care, while the other is still active and independent. Or maybe a stroke or chronic illness has created care needs that can no longer be safely managed at home, despite the spouses best efforts.These situations bring a complicated mix of emotions, including grief over changing roles, worry about separation, and uncertainty about the future. Layered on top of these feelings is a pressing financial concern: How do we approach funding senior care without leaving the spouse who lives at home unable to afford basic living expenses?The good news is that financial protections exist specifically to address this scenario, particularly when Medicaid is involved. Understanding how income and assets are evaluated when only one spouse needs care, and knowing which funding options may be available, can provide both practical direction and much-needed peace of mind during an already stressful time.Medicaid rules that protect the spouse at homeWhen one spouse needs to move to a nursing home or, in some states, to assisted living through a Medicaid waiver program, special rules help protect the financial security of the spouse who remains at home (referred to as staying in the community, meaning their local community as opposed to a senior living community). In Medicaid terminology, this person is called the community spouse, while the person entering care is the institutionalized spouse.What care settings do these protections apply to? Community spouse protections primarily apply when one spouse enters a nursing home and needs Medicaid to help pay for that care. In states that offer Medicaid waiver programs covering assisted living or memory care, some of these protections may also apply, though the rules can differ. These protections generally do not apply to independent living or other residential settings that dont qualify for Medicaid long-term care coverage.The core principle behind these protections is preventing spousal impoverishment, the idea that paying for one spouses care shouldnt leave the other spouse destitute. Without these rules, couples would need to spend nearly all their joint savings before Medicaid would help, potentially leaving the community spouse with almost nothing to live on.Instead, Medicaids spousal impoverishment protections allow the community spouse to keep a protected amount of the couples joint assets and income. Two key terms define these protections: The Community Spouse Resource Allowance (CSRA) is the amount of the couples combined countable assets that the community spouse can retain without affecting the institutionalized spouses Medicaid eligibility. For 2025, federal guidelines set this range between approximately $31,584 (the minimum) and $157,920 (the maximum), though the exact amount varies by state. Some states automatically allow the maximum, while others calculate it based on half of the couples combined countable assets, up to that maximum. The Minimum Monthly Maintenance Needs Allowance (MMMNA) protects the community spouses income. If the community spouses own income falls below a certain threshold (approximately $2,644 to $3,948 per month, depending on the state), they may be entitled to some or all of their institutionalized spouses income to reach that minimum level. This ensures that the community spouse has an adequate monthly income to maintain their household. These protections make a significant practical difference. Instead of spending down to near-poverty levels, a couple can preserve substantial resources for the community spouses ongoing living expenses, home maintenance, and future needs, while still qualifying the institutionalized spouse for Medicaid coverage. These rules are central to funding senior care in a way that safeguards both partners needs.Paying for senior care: Funding and benefit options to exploreBeyond Medicaids spousal protections, several funding sources may help cover care costs when one spouse moves to a community. Most families use a combination of these options over time and understanding them is an important part of funding senior care responsibly and sustainably.Private savings or retirement incomeMany couples initially pay for care using savings, retirement accounts, Social Security benefits, and pensions. When both spouses have their own income streams, families can often dedicate one spouses income toward care costs while the other spouses income covers household expenses at home.This arrangement can work well in the short term, though it may not be sustainable indefinitely if care costs significantly exceed one spouses income. For example, if assisted living costs $5,000 monthly but the spouse needing care receives only $2,500 in Social Security benefits, the couple must cover the $2,500 gap from savings or other income, a strategy that works until their savings deplete to levels where Medicaid eligibility becomes relevant.Veterans benefits (Aid and Attendance)The VAs Aid and Attendance benefit can provide additional monthly income to help pay for care, and it applies in situations where one spouse needs care while the other remains at home. This benefit is available to qualifying wartime Veterans or their surviving spouses who need help with daily activities.Importantly, when one spouse is a Veteran and the other needs care, the Veteran may claim Aid and Attendance benefits on behalf of their spouse. Similarly, if the Veteran needs care and has a spouse at home, the benefit amount may be higher than for a single Veteran, recognizing the need to support both the Veteran and the dependent spouse.This benefit considers household income and medical expenses, so families paying significant care costs may qualify even with moderate retirement income.Long-term care insuranceIf one or both spouses purchased long-term care insurance years ago, this can be a significant help. These policies typically pay a daily or monthly benefit when the insured person needs assistance with activities of daily living, regardless of the care setting, whether in a nursing home, assisted living, memory care, or even at home.When only one spouse has a policy, that insurance covers their care costs, preserving more of the couples joint assets and income for the community spouses needs. Some policies also include inflation protection or shared benefits between spouses, which can extend coverage considerably.MedicaidFor many couples, Medicaid eventually becomes necessary when care costs exhaust other resources. When one spouse applies for Medicaid, eligibility is determined using special rules that account for the couples marital status.Rather than treating each spouses income and assets separately, Medicaid looks at the couples combined resources, then applies the community spouse protections described earlier. This means the community spouse can retain protected amounts of both assets and income, while the institutionalized spouse can qualify for Medicaid even though the household as a whole has resources above the typical individual eligibility limits.The application process requires substantial documentation, financial records, asset statements, proof of income, and medical evaluations, and the rules around asset transfers and look-back periods are complex. However, the protections built into the system specifically for married couples can make Medicaid a viable option for funding senior care without impoverishing the spouse who remains at home.Where to find reliable helpNavigating these financial decisions while managing the emotional challenges of separation and changing care needs can feel overwhelming. You dont have to figure it all out alone.Contact your local Oasis advisor. Senior care advisors understand the local care landscape and can help you identify communities that fit both your loved ones care needs and your familys financial situation. They can explain which communities work with different payment sources, including Medicaid, and guide you through the process of finding appropriate care. Find your local Oasis advisor to get personalized support during this transition.Consult an elder law attorney. If Medicaid eligibility is a concern, either now or in the foreseeable future, working with an elder law attorney who specializes in Medicaid planning is invaluable. These attorneys understand your states specific rules, can help you navigate community spouse protections, ensure youre maximizing allowable asset retention, and guide you through the application process to avoid costly mistakes.The situation youre facing is difficult, but resources and protections exist to help you secure necessary care for one spouse while preserving financial stability for the other. With the right information and support, you can make decisions that honor both partners needs during this challenging chapter.
You Are Staying in Your Home but Need Help Downsizing
Downsizing isn't only for people who are moving. Many people choose to stay right where they are in the home filled with decades of memories but still feel the need to simplify, declutter, and create a more manageable living space. If that sounds like you, know this: you don't have to move to benefit from downsizing, and you don't have to do it alone.Why Downsize If You're Not Moving?There are many reasons someone might want to downsize their belongings while remaining in their home: Safety Reducing clutter can lower the risk of falls and make it easier to navigate the home, especially for aging in place. Simplicity A less cluttered space is often easier to clean, maintain, and enjoy. Peace of mind Many people find that a lighter, more organized home brings a sense of calm and control. Preparing for the future Sorting through belongings now deciding what's meaningful, what can be passed on, and what no longer serves a purpose can ease the burden on family members later. Mental clarity A more organized home can reduce daily stress and make everyday living more enjoyable. Whatever your reason, the goal is the same: a home that feels lighter, safer, and easier to live in without sacrificing the comfort and familiarity of staying where you are.The Same Structured Approach, Without the MoveDownsizing while staying in place uses the same thoughtful, room-by-room approach used when preparing for a move the difference is simply that everything you decide to keep stays right where it belongs: in your home.A structured approach typically includes: An initial conversation to understand your goals, priorities, and any specific areas of concern. A room-by-room plan to make the process feel manageable rather than overwhelming. Sorting and decision-making support guidance on what to keep, donate, sell, or let go of, without pressure or judgment. Organizing and reconfiguring your space so that what remains is arranged in a way that's functional, safe, and easy to enjoy. Coordinating donations, sales, or removal of anything you no longer want in your home. The Benefits of Hands-On HelpDownsizing on your own can be emotionally and physically exhausting, especially when sorting through decades of belongings. Having experienced, compassionate help alongside you can make a meaningful difference: Objective guidance A trusted third party can help you make decisions without the emotional weight that often comes with sorting through your own history. Physical support Sorting, lifting, and organizing can be physically demanding, especially for those with mobility challenges. Reduced overwhelm Breaking the process into manageable steps, guided by someone experienced, keeps the project from feeling impossible. A healthier, happier home The end result isn't just fewer belongings it's a home that feels lighter, safer, and more enjoyable to live in every day. A Path to a Healthier, Happier, Less Cluttered HomeYou don't need to be planning a move to benefit from downsizing. Whether your goal is a safer home, a simpler lifestyle, or peace of mind for the future, the process can be approached with the same care and structure as a full relocation just without the boxes and moving truck.If you're staying in your home but feel ready to simplify your surroundings, support is available every step of the way from that first conversation to the final, clutter-free result.If you'd like guidance on downsizing while staying in your home, we're here to help you create a space that feels healthier, happier, and easier to live in.
Local Services By This Author

The Junkluggers
Clutter Clean Up , , Texas, 75080Eco-friendly solution to junk removal in Dallas/Fort Worth Metroplex and Surrounding Areas.Are you looking to get rid of some old junk that is cluttering up your property or commercial space? The Junkluggers is here to help! They offer a wide range of junk removal services and have trained professionals ready to help clean up. From bulky furniture pieces to old electronics and even yard debris, their luggers can haul away any junk you have. Book a free on-site junk removal estimate today! MENTION CODE: 25BLUEBOOK to receive $25 off a 1/4 truck or more (In participating areas. Limit 1 per job. Cannot combine offer. Tax not included.) Services by The Junkluggers:Junk removalCommercial junk removalE-waste removal/ recyclingProperty management cleanouts Construction site cleanoutsSenior downsizingEstate cleanoutsAppliance removalFurniture removalAttic, basement & garage cleanoutsStorage unit cleanoutsHoarding cleanoutsAnd more!Say goodbye to your junk!Committed to removing unwanted items & helping the Dallas/Fort Worth Metroplex. At The Junkluggers, they strive to change the way people dispose of their unwanted items. They are an eco-friendly junk removal company because their luggers work hard to donate or recycle as many of your old items as possible. Anything that cannot be donated or recycled will be responsibly disposed of. They can remove all your items in a timely and efficient manner, without leaving a trace in your home or commercial space. Ready to get rid of your old furniture or appliances that are taking up space in your home or business? The Junkluggers offers commercial junk removal services, so they can help you clean up your local business. They also offer free on-site estimates on all their services when you schedule an appointment today!