Respite Stays - Learn More About the Benefits

Email US
Click to Email Us
Courtesy of Meridian Senior Living
Offering a short-term stay or respite program allows guests the opportunity to experience our community without any long-term commitment and offers caregivers some time to do, well whatever they need to do. It is important for caregivers to get a break now and then, and short-term stays is a great guilt-free option. Guests are charged a day rate with a minimum and maximum stay, and the community offers full access to amenities, dining, activities and, typically, a fully furnished apartment. Short-term stays provide a number of benefits to guests and their caregivers:
Recovery/Rehabilitation Stay: There may come a time in our lives when we are in need of assistance, particularly as we get older. If you or a loved one has just come out of the hospital, rehabilitation clinic or other healthcare facility, a short-term stay can provide a place to go to have caring and compassionate nurses manage your medication, assist with activities of daily living, and help you to recover. This can be a great option if a caregiver works and may not have the time needed to care for their loved one when they need more immediate and regular attention post-hospitalization.
Family Caregiver Absence
Sometimes caregivers may need to be absent for an extended period of time or may feel the need for a break from the stress of caregiving. Maybe a much-needed vacation is in order or work may pull a caregiver away, whatever the reason, a short-term respite stay can give caregivers peace of mind and flexibility, giving our new guest the opportunity to participate in exciting activities, enjoy restaurant-style dining and not have to worry about doing the dishes or cleaning the house as all of these services and more are provided!
Trial Stay
Making the decision to move to a senior community, no matter how beautiful, fun, exciting and caring it may be, is a very big and at times, an intimidating and scary experience. Signing the Lease Agreement adds to that scary thought. What if you could try it, before you commit? Our respite program allows you to do just that. Our respite guests experience community life with all the amenities, care services, full-service dining, and a wide range of activities and events that our residents enjoy every day!
Valuable Socialization
There are great benefits to living at a community. As we age, socialization and interaction become essential to keep our minds and bodies healthy. Getting involved and meeting people adds purpose and meaning to the day as you meet your neighbors for dinner or an activity, attend an exercise class, or go on outings with friends. Many times, living alone at home or even with loved ones, doesnt provide that level of independence. Respite stays, while just a short-term solution, give guests a glimpse into a more active social life that is all their own.
For each type of stay you will have access to the following accommodations:
A private studio or one bedroom apartment with an emergency call system right at your fingertips!
Weekly housekeeping and linen services.
Scheduled local transportation for community outings, personal appointments and/or errands.
Table side dining with chef prepared meals available in the dining room or with room service. (please specify any special dietary needs, food allergies etc.)
24-hour staffing
A diverse calendar of events and activities geared to provide opportunities to learn, socialize, worship, create and stay fit! Most of all to have FUN!
No matter which option you choose Or mission is to ensure you will leave us with a spring in your step, a gleam in your eye and a smile on your face! Relaxed and Rejuvenated!! Secure in your knowledge that no matter what your circumstance or need, you will always be part of our Meridian Family!! Because we truly believe that
Everyone Deserves a Great Life!!
Other Articles You May Like
Now is a Great Time to Explore Willow Valley Communities
Willow Valley Communities Manager of Sales, Margie Seagers, has been pleasantly surprised by the recent increased interest shes received from prospects wanting to learn more about life in our communities. As 2020 came to a close, she found many seniors in a reflective mood, examining where they had been, where they are now, as well as where and how they want to spend the next phase of their lives. Ive been hearing from seniors that they want the increased support from a community they can trust, Margie said. She added that the people shes been hearing from have been doing a good job at staying safe in their own homes, but over time its gotten pretty lonely. Its also been difficult to have consistent services on their own during the pandemic. As much as people say they can depend on their adult children or close friends to help them, there does come a time when that person is unable to help because of their own family obligations. Margie has also found that Willow Valley Communities 35-plus years reputation of excellence in senior living means even more now to seniors especially Baby Boomers. She said that Lifecare, Willow Valley Communities financially smart contract that promises supportive care, if ever needed, without an increase to monthly service fees, especially has caught their attention. Baby Boomers traditionally want to feel empowered to make their own decisions, and theyve spent their time researching. They desire a secure community environment, but they want the facts, and Willow Valley Communities has several ways to tell them more about what senior living options are available to them. We are happy to have that conversation, in person or online, to give them all the information they need to make a decision that is right for them, she said. Margie said shes had many visitors who have come to Willow Valley Communities during the COVID-19 pandemic for a safe, socially distant, in-person informational meeting. The process is very easy, she explained. Everyone goes through our screening process at the Cultural Center just two minutes away from the Welcome Center, where we then can meet. The Welcome Center has specially adapted, socially distant and private meeting areas. Prospects can comfortably meet with a Sales Counselor and get all the information they need about becoming a Resident at Willow Valley Communities. Tours are available for those interested in seeing more. For those who prefer a virtual meeting from the comfort of their own home, that is also easy to arrange. Willow Valley Communities Sales Counselors are happy to arrange an online Zoom meeting at a prospects convenience. And its as detailed as an in-person meeting, Margie noted. Willow Valley Communities Sales Counselors are known for their thorough knowledge of senior living and are able to explain all options thoroughly during an online meeting. She also said that, if needed, Sales Counselors can show close-up features of a specific residence, virtually, to a prospective Resident. Plus, virtual tours of Willow Valley Communities campus are always available online at WillowValleyCommunities.org. Its almost like being right here! Margie quipped. If youre considering a move to a secure senior living community, Willow Valley Communities is ready to provide all the information you need, whenever and however you wish. Whether its in person, online by appointment, or through WillowValleyCommunities.org, Willow Valley Communities is available to help you imagine your Life Lived Forward.
Downsizing or Selling Your Home in Retirement: Tax Implications to Kno
Downsizing or Selling Your Home in Retirement: Tax Implications to KnowSelling the family home is one of the biggest financial decisions many people make in retirement whether you're downsizing something smaller, moving closer to family, or relocating somewhere warmer. Before you list the house, it's worth understanding how the sale could affect your taxes.The Good News: Most Home Sellers Owe Little or No TaxUnder federal tax law, homeowners can exclude a significant amount of profit from capital gains tax when they sell a primary residence: Up to $250,000 in gain excluded for single filers Up to $500,000 in gain excluded for married couples filing jointly These limits have stayed the same since 1997 they aren't adjusted for inflation but for most sellers, especially those who haven't owned an especially high-value home for decades, they're enough to eliminate the tax bill entirely.Do You Qualify for the Full Exclusion?To claim the exclusion, you generally need to pass two tests: Ownership test: You owned the home for at least 2 years during the 5-year period before the sale. Use test: You lived in the home as your primary residence for at least 2 years during that same 5-year period. For married couples claiming the full $500,000 exclusion, both spouses need to meet the use test, though only one spouse needs to meet the ownership test. If only one spouse meets the use test, the exclusion drops to $250,000.If you don't fully meet the two-year requirements but had to sell due to a job change, health issue, divorce, or similar unforeseen circumstance, you may still qualify for a partial exclusion.How Your Gain Is Actually CalculatedThis is where record-keeping pays off. Your taxable gain isn't your sale price it's your sale price minus your cost basis, which includes: What you originally paid for the home The cost of qualifying capital improvements over the years (a new roof, an addition, major renovations not routine repairs or maintenance) Selling costs, such as agent commissions Every dollar documented improvement raises your basis and lowers your taxable gain. If you've owned your home for decades, digging up old receipts and records for major projects can make a meaningful difference sometimes the difference between owing tax and owing nothing at all.What Happens If Your Gain Exceeds the ExclusionIf your profit is larger than your exclusion amount, the excess is taxed as a long-term capital gain (assuming you owned the home more than a year), generally at 0%, 15%, or 20% depending on your overall taxable income. For higher-income sellers, an additional 3.8% Net Investment Income Tax may also apply above certain income thresholds. This is more common than it used to be for retirees who've owned a home for many years in an area where property values have risen substantially.A Few Other Situations Worth Knowing Home office deductions: If you claimed depreciation on a home office in past years, that portion is generally "recaptured" and taxed differently when you sell, separate from the main exclusion. Selling a second home or rental property: The primary residence exclusion generally doesn't apply to vacation homes or rental properties. Different rules, including possible depreciation recapture, come into play. Inherited homes: If you're selling a home you inherited, the property typically receives a stepped-up basis to its fair market value at the time of the original owner's death which can significantly reduce or eliminate taxable gain compared to using the original purchase price. Using the exclusion more than once: The exclusion isn't a one-time benefit. You can generally use it again for a future home sale, as long as you meet the ownership and use tests again and haven't claimed it on another sale within the prior two years. Why Planning Ahead MattersThe tax side of selling a home is often simpler than people expect, especially with the exclusion in play but assumptions can be costly in either direction. Some retirees overestimate their tax exposure and hesitate to sell when they'd actually owe little or nothing. Others underestimate it, especially with a long-held, appreciated home, and are surprised by a gain above the exclusion. Reviewing your specific numbers before you list the home, rather than after the sale closes, gives you room to plan.Thinking about downsizing or selling a home in retirement? Contact Zunic Advisory Services to walk through what the sale could mean for your taxes.
Required Minimum Distributions Explained: What Seniors Need to Know
Required Minimum Distributions Explained: What Seniors Need to Know Each YearIf you have a traditional IRA, 401(k), or similar tax-deferred retirement account, the IRS eventually requires you to start withdrawing money from it whether you need the cash or not. These withdrawals are called Required Minimum Distributions, or RMDs, and getting them wrong can be costly. Here's what to know.What Is an RMD?An RMD is the minimum amount you're required to withdraw each year from certain retirement accounts once you reach a specific age. The rule exists because these accounts let your money grow tax-deferred for decades the IRS eventually wants its share, so it requires withdrawals (which are taxed as ordinary income) to begin at a set point.RMDs generally apply to: Traditional IRAs SEP and SIMPLE IRAs 401(k), 403(b), and most other employer-sponsored retirement plans RMDs do not apply to Roth IRAs during the original owner's lifetime, and as of 2024, Roth 401(k) and Roth 403(b) accounts no longer require RMDs either.What Age Do RMDs Start?The starting age has changed more than once in recent years under the SECURE Act and SECURE 2.0, so its worth checking which rule applies to you based on your birth year: Born 1950 or earlier: RMD age is 73 Born 19511959: RMD age is 73 Born 1960 or later: RMD age is 75 Because the rules phased in over several years, it's easy to be working from outdated information especially if you read something a few years ago. When in doubt, confirm your specific required beginning age rather than assuming.The First-Year Deadline Is a Little DifferentYour very first RMD comes with a special option: you can delay it until April 1 of the year after you reach your RMD age, rather than taking it by December 31 of the year you turn that age.The catch: if you delay that first withdrawal, you'll need to take two RMDs in that same calendar year the delayed one and the current year's which can push you into a higher tax bracket. For many people, taking the first RMD by December 31 of the year they reach RMD age, rather than waiting, actually results in a smoother tax picture.After your first RMD, all future ones are due by December 31 each year.How Is Your RMD Calculated?Your RMD is based on your account balance as of December 31 of the prior year, divided by a life expectancy factor from an IRS table (most people use the Uniform Lifetime Table). The result is your required withdrawal for the year. If you have multiple IRAs, you calculate the RMD for each one separately but can withdraw the total from any single IRA or combination of them. 401(k) accounts generally don't allow that same flexibility each 401(k) typically requires its own withdrawal.What Happens If You Miss One?Missing an RMD, or withdrawing less than required, comes with a real penalty: a 25% excise tax on the amount you should have withdrawn but didn't. That penalty can be reduced to 10% if the mistake is corrected within two years. Given how steep the penalty is, it's worth building a reliable system or working with someone who tracks it for you rather than relying on memory alone.A Strategy Worth Knowing: Qualified Charitable DistributionsIf you're charitably inclined, a Qualified Charitable Distribution (QCD) lets you transfer funds directly from your IRA to a qualifying charity. That amount can satisfy some or all of your RMD for the year without counting as taxable income which can help keep your adjusted gross income lower, potentially reducing how much of your Social Security is taxed and help avoid higher Medicare premium brackets. This is generally available starting at age 70, even though it's tied to satisfying RMDs that begin later.Why This Deserves Yearly AttentionRMDs aren't a "set it and forget it" task. Your required amount changes every year as your balance and life expectancy factors change, and a distribution can ripple into other parts of your tax return affecting how much of your Social Security is taxable, your Medicare premium bracket, and your overall tax bill. Reviewing your RMD strategy annually, rather than treating it as a single calculation, often uncovers opportunities to plan more efficiently.Want help calculating your RMD or building it into your broader tax strategy? Contact Zunic Advisory Services we're happy to walk through where you stand.
Local Services By This Author
Addington Place of Cape Coral
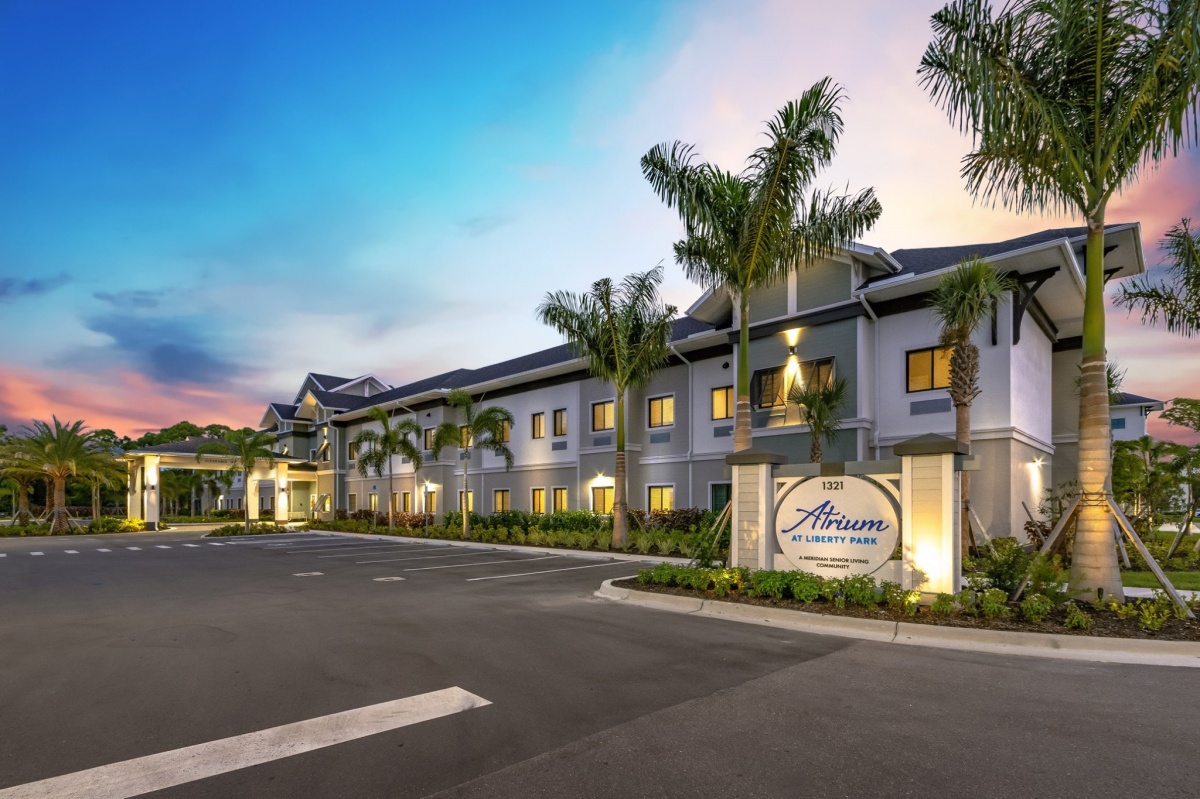
Independent Living 1321 N.E. 24th Ave., Cape Coral, Florida, 33909Addington Place of Cape Coral is a welcoming senior living community providing supportive independent living, assisted living, and specialized Valeo memory care in Cape Coral, Florida. The community offers personalized services designed to support residents as their needs change while helping them maintain independence, comfort, and meaningful connections.Independent living residents enjoy a convenient, low-maintenance lifestyle with chef-inspired dining, scheduled transportation, social activities, wellness programs, housekeeping, and other supportive services. Assisted living provides additional help with everyday needs, including bathing, dressing, medication management, and personal care, while encouraging residents to remain active and involved in community life.For individuals living with Alzheimers disease or other forms of dementia, the Valeo memory care program provides structured routines, personalized support, and purposeful activities in a comfortable environment. Addington Place of Cape Coral also offers short-term stays, 24-hour nursing services, on-site therapy, landscaped courtyards, and a full calendar of enrichment programs.
Addington Place of Cape Coral
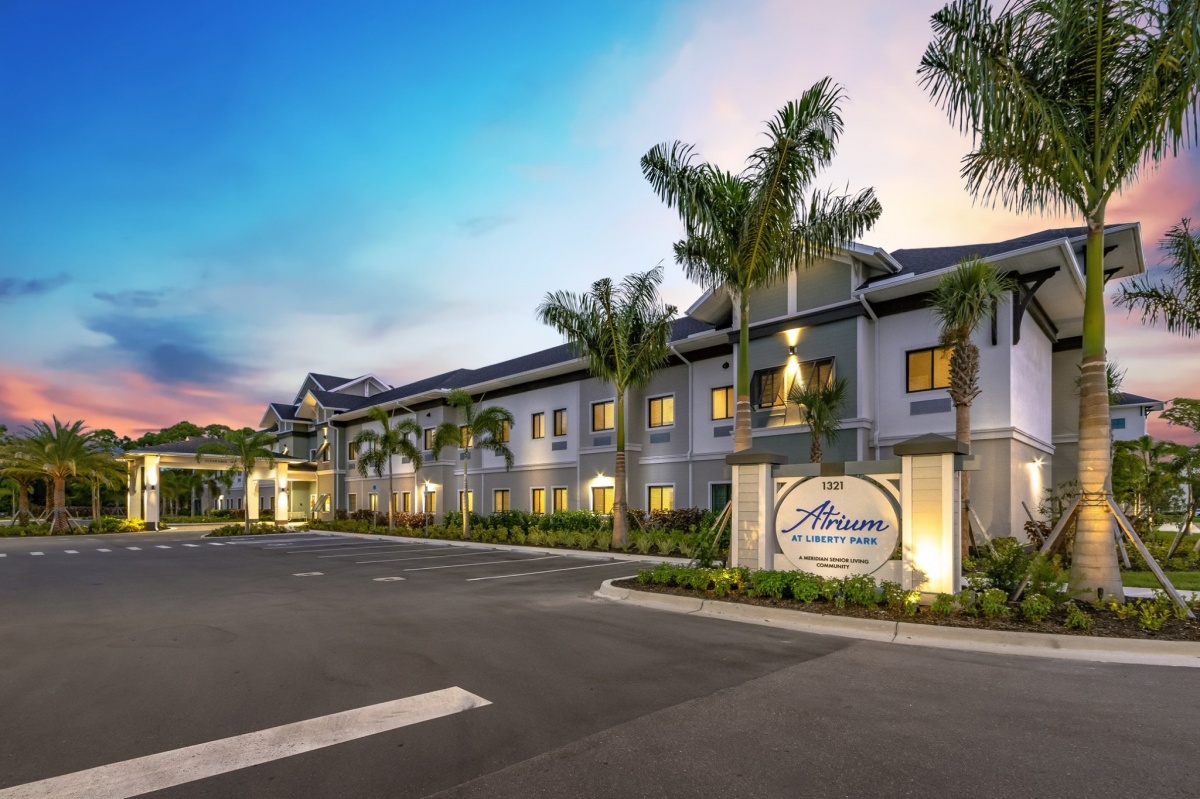
Assisted Living 1321 N.E. 24th Ave., Cape Coral, Florida, 33909Addington Place of Cape Coral is a welcoming senior living community providing supportive independent living, assisted living, and specialized Valeo memory care in Cape Coral, Florida. The community offers personalized services designed to support residents as their needs change while helping them maintain independence, comfort, and meaningful connections.Independent living residents enjoy a convenient, low-maintenance lifestyle with chef-inspired dining, scheduled transportation, social activities, wellness programs, housekeeping, and other supportive services. Assisted living provides additional help with everyday needs, including bathing, dressing, medication management, and personal care, while encouraging residents to remain active and involved in community life.For individuals living with Alzheimers disease or other forms of dementia, the Valeo memory care program provides structured routines, personalized support, and purposeful activities in a comfortable environment. Addington Place of Cape Coral also offers short-term stays, 24-hour nursing services, on-site therapy, landscaped courtyards, and a full calendar of enrichment programs.
Addington Place of Cape Coral
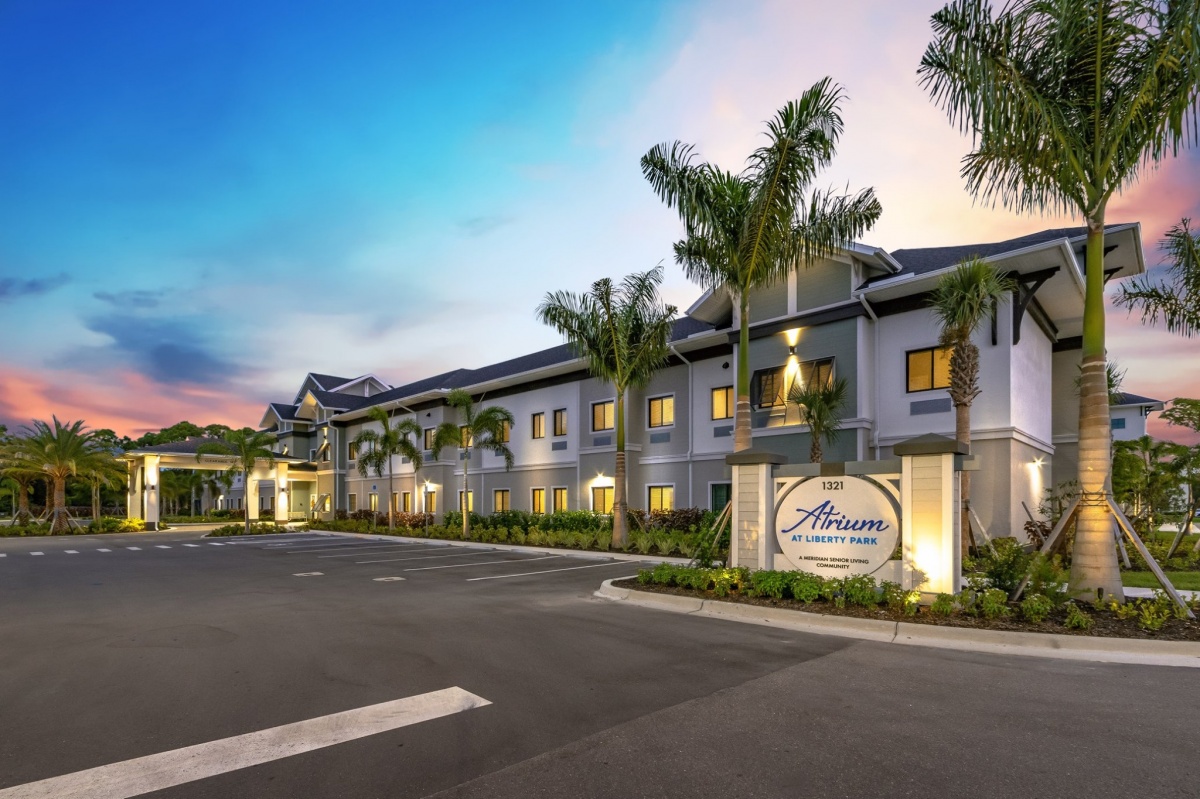
Memory Care 1321 N.E. 24th Ave., Cape Coral, Florida, 33909Addington Place of Cape Coral offers supportive independent living, assisted living, and memory care services in Cape Coral, Florida. Voted Best Assisted Living by U.S. News & World Report for 2023-2024, our community provides an exciting and fulfilling lifestyle for seniors.Services: At Addington Place, youll find more than senior living services. Youll find community. Feel confident that our experienced senior care team is invested in your health and wellbeing. Enjoy a senior living community where its easy to fill your days with opportunities for fun and engagement. Our goal is to enrich the lives of those who call Atrium at Liberty Park home. We offer an array of programs and services that focus on whole-body wellness whether its creating an opportunity to socialize and make new friendships or participating in daily activities designed to strengthen your body and mind. For more information, visit the Lifestyle page.Lifestyle: Living at Atrium at Liberty Park is a fresh start to let go of responsibility and do more of what makes you happy. Relish in the simple pleasures and leave behind the burdens of owning and maintaining a home. We take care of everything, leaving you with more time for new friendships and hobbies, daily adventures, or maybe just more time to relax and be pampered.Memory Care: For residents with Alzheimers or other dementia, Atrium at Liberty Park is proud to feature MONTESSORI MOMENTS IN TIME memory care programming. We make every day feel special for your loved one with exceptional care and success-oriented programming that brings a sense of purpose and meaning to your loved one's experience at Atrium at Liberty Park.Contact us today to learn more about our community and how we can provide the tranquility and care your family deserves.