Ahrens Deangeli Law Group
420 Main St, Suite 305, Boise, Idaho, 83702
Counties Served: Idaho - Ada | Idaho - Canyon
Long Term Care Insurance
.jpg)


About Ahrens Deangeli Law Group
Let Elder Law at Ahrens DeAngeli Law Group
guide you through the maze of financial and legal decisions that are
part of growing older. We strive to protect your familys hard-earned
assets, ensure loved ones receive the quality care they need and,
ultimately, provide greater peace of mind through proper planning.
We focus on elder law and closely related practice areas, including
Medicaid planning, elder-focused estate planning, veterans benefits
planning, and Alzheimers planning.
We are part of Ahrens DeAngeli Law Group. Please call us at (208) 387-0729 to schedule a meeting with one of our attorneys.
See More
Additional Services Offered
Ahrens Deangeli Law Group
Elder Law 420 West Main Street, Suite 305, Ada County, Boise, Idaho, 83702Let Elder Law at Ahrens DeAngeli Law Group guide you through the maze of financial and legal decisions that are part of growing older. We strive to protect your familys hard-earned assets, ensure loved ones receive the quality care they need and, ultimately, provide greater peace of mind through proper planning. We focus on elder law and closely related practice areas, including Medicaid planning, elder-focused estate planning, veterans benefits planning, guardianship and conservatorships, and Alzheimers planning. We are part of Ahrens DeAngeli Law Group. Please call us at (208) 387-0729 to schedule a meeting with one of our attorneys.
Continue Your Search! Explore More Local Options.
Start SearchingLet’s engage and get educated!
Browse through thousands of expert articles in over 100 different categories.
Browse NowArticles You May Like
Powers of Attorney, Healthcare Directives, Guardianship, and Conservat
Powers of Attorney, Healthcare Directives, Guardianship, and ConservatorshipMany families prepare carefully for what will happen after someone dies.They create a will.They name beneficiaries.They talk about who should receive the house or family heirlooms.But another question can be just as important:What happens if you are still living but can no longer manage important decisions on your own?A serious illness, stroke, brain injury, dementia, or other condition can affect someone's ability to handle finances, communicate healthcare choices, sign documents, or make complex decisions.For older adults and families in Boise and Ada County, Idaho, planning for that possibility can help clarify who should step in, what authority they should have, and what wishes they should follow.Ahrens DeAngeli Law Group focuses its elder law practice on legal concerns affecting older adults, including powers of attorney, estate planning, Alzheimer's and dementia planning, Medicaid and long-term care planning, and related incapacity issues. The firm's elder law office is located at 420 West Main Street, Suite 305 in Boise.Planning early can sometimes reduce the likelihood that a family will have to seek court involvement later.Incapacity Planning Is About Life, Not Just DeathEstate planning is often associated with inheritance.Incapacity planning focuses on what happens during life.Families may need answers to questions such as:Who can pay bills if I cannot?Who can manage bank accounts?Who can communicate with insurers?Who should make healthcare decisions?Who understands my medical wishes?What happens if no one has legal authority to act?Would a court-appointed guardian or conservator become necessary?Ahrens DeAngeli emphasizes powers of attorney as important caregiving documents because they can give a trusted person authority to address matters such as bills, taxes, and financial assistance when the individual cannot manage those responsibilities independently.Planning Tip: Incapacity documents are usually most useful when they are created before anyone urgently needs them. Waiting until someone can no longer understand or sign legal documents may significantly limit the available options.What Is a Financial Power of Attorney?A financial power of attorney allows someone to appoint another personoften called an agentto act on their behalf within the authority provided by the document.Depending on how it is written, that authority may involve matters such as:Paying billsManaging bank accountsHandling real estate mattersDealing with taxesManaging investmentsCommunicating with financial institutionsApplying for certain benefitsAddressing other financial responsibilitiesAhrens DeAngeli notes that powers of attorney are especially important for caregivers who may eventually need to handle finances or pursue financial assistance for a loved one.Not every power of attorney contains the same authority.An older document may not address the kinds of transactions that later become necessary.That is why families should not simply ask, "Do we have a power of attorney?"A more useful question may be:"Does the document we have actually provide the authority that may be needed?"Healthcare Decision-Making Requires Different PlanningFinancial authority does not automatically answer healthcare questions.Idaho's Advance Directive includes two components:A Durable Power of Attorney for HealthcareA Living WillThe Durable Power of Attorney for Healthcare allows an individual to name someone to speak on their behalf if they cannot communicate or make medical decisions.The Living Will provides instructions regarding certain medical treatment preferences.Idaho's Department of Health and Welfare encourages people creating an advance directive to discuss their values, wishes, and instructions with the person they choose as their healthcare agent.That conversation can be just as important as the document itself.A person named as healthcare agent should understand questions such as:What matters most to you if you become seriously ill?What kinds of treatment would you want or decline?How do you think about quality of life?Who should be included in important family discussions?Are there religious or personal values that should guide decisions?Legal paperwork works best when the people involved understand the wishes behind it.Idaho Has an Advance Directive RegistryIdaho also maintains a Healthcare Directive Registry.The Idaho Department of Health and Welfare describes the registry as a secure way to create, upload, store, and share an advance directive so the document can be available to healthcare providers and family members when needed.An Idaho Advance Directive must be signed by the individual, and the state says it does not need to be notarized or signed by a medical provider.Even when a document is valid, practical access matters.A healthcare directive stored somewhere no one can find during an emergency may be difficult to use.Families may want to make sure:The healthcare agent knows where the document is.Important family members know who has been appointed.Healthcare providers have access when appropriate.Updated documents replace outdated copies.Choosing an Agent Deserves Careful ThoughtSelecting someone to act under a power of attorney is not simply an honorary designation.The person may eventually be responsible for important decisions during a stressful time.Consider whether the individual is:TrustworthyOrganizedWilling to serveComfortable handling financial or healthcare mattersAble to communicate with family membersAvailable when neededCapable of following your wishes even when they differ from their ownThe person who is best at handling finances may not necessarily be the same person you would choose for healthcare decisions.Families should also think about backup agents in case the first person becomes unavailable.What Happens When There Is No Power of Attorney?If someone loses the ability to manage important decisions and no effective planning documents are in place, the family may need to explore court involvement.That can include guardianship, conservatorship, or both.The Idaho Supreme Court explains that guardians and conservators are appointed by a court to act for someone who cannot fully manage their own affairs. In Idaho, a guardian generally handles personal and health-related decisions, while a conservator manages financial matters or property.These roles are different from a voluntarily created power of attorney.A power of attorney is generally established by the individual while they still have the legal ability to appoint someone.Guardianship and conservatorship involve a court process.What Does an Idaho Guardian Do?The Idaho Supreme Court defines a guardian as a court-appointed person who makes personal or health-related decisions for another individual.Depending on the court order and circumstances, responsibilities may involve matters such as:Living arrangementsHealthcarePersonal welfareSafetyOther significant personal decisionsIdaho Health and Welfare explains that guardianship can be used when an incapacitated person lacks the ability to make informed decisions about care or finances, though the exact guardianship process depends on which Idaho law applies to the individual.Guardianship should not be viewed casually.It can affect important personal rights and decision-making authority.What Does a Conservator Do?A conservator generally focuses on finances and property.The Idaho Supreme Court defines a conservator as a person appointed to manage the finances or estate of a protected person.That may involve:Managing financial accountsProtecting assetsPaying appropriate expensesHandling propertyKeeping financial recordsReporting to the court when requiredIdaho Health and Welfare notes that when a person's finances are substantial enough to require formal management, a conservator may be appointed separately from the guardian.One person may sometimes serve in both roles, but guardianship and conservatorship are legally distinct responsibilities.Guardianship Is a Court ProcessFamilies sometimes assume they can simply declare themselves a parent or spouse's guardian.That is not how the process works.Idaho courts describe guardianship and conservatorship as formal legal arrangements involving court appointment. Idaho's judicial system provides forms, rules, education, and required procedures for guardians and conservators.In adult guardianship matters, the process can involve:Filing a petitionCourt reviewNotice to interested partiesA court visitor in applicable casesLegal representation for the proposed protected personA hearingA judicial decision about whether guardianship is necessaryThe exact process depends on the circumstances and applicable Idaho law.Because guardianship can affect significant legal rights, families facing this situation may benefit from legal advice rather than assuming the process is simply paperwork.Idaho Requires Training for Many Guardians and ConservatorsCourt appointment also brings responsibilities.Idaho Court Administrative Rule 54 generally requires a proposed guardian or conservator to complete online training before receiving permanent letters of appointment, unless the court waives the requirement for good cause.That reflects an important point:Guardianship is not merely permission to make decisions.It creates ongoing legal responsibilities toward another person.Conservators may also have recordkeeping, inventory, accounting, and court-reporting obligations. Idaho's court system provides separate reporting forms for adult guardians and conservators.Guardianship Should Not Automatically Be the First SolutionIdaho emphasizes that guardianship can be restrictive.The Idaho Department of Health and Welfare encourages families to consider whether less restrictive alternatives might provide enough support. These can include tools such as powers of attorney, representative payees, information releases, or supported decision-making arrangements when appropriate.Supported decision-making allows an individual to select trusted supporters who help explain information, consider options, and communicate decisions while the individual retains decision-making authority.Not every older adult experiencing difficulty needs a guardian.The appropriate solution depends on the person's abilities, risks, legal capacity, and available support.Dementia Makes Early Planning Particularly ImportantDementia is one situation where timing can matter greatly.Early in the disease, a person may still be able to understand legal documents and make informed decisions about who should act for them.As cognitive impairment progresses, that may change.Ahrens DeAngeli's dementia-planning materials emphasize establishing financial and healthcare powers of attorney while the person still has sufficient legal capacity. The firm notes that delayed planning can create more complicated legal problems for families later.Families should not assume that a dementia diagnosis automatically eliminates all legal capacity.Capacity can depend on the person, the decision, and the circumstances.But a diagnosis can be an important reason to review existing documents promptly.Review Documents After Major Life ChangesEven families who already have estate planning documents should review them periodically.Important questions include:Is the named agent still living?Is the agent still willing and appropriate?Have family relationships changed?Has a spouse died?Has someone moved out of state?Have health needs changed?Does the document address long-term care or benefit planning issues that may now matter?Ahrens DeAngeli's elder law resources encourage families to revisit estate and incapacity plans after significant health changes, particularly when memory loss or dementia becomes part of the picture.The goal is not to constantly rewrite documents.It is to make sure the plan still reflects reality.Keep Important Documents AccessibleA carefully drafted plan cannot help very much if no one knows where it is.Families may want to keep an organized file containing:Financial power of attorneyHealthcare advance directiveLiving willWill or trustInsurance informationLong-term care insuranceMedication listHealthcare provider informationEmergency contactsThe person named as agent should know how to locate relevant documents.Families should also avoid scattering conflicting copies of old and new documents across several locations.Clear organization can help prevent confusion when decisions must be made quickly.Talk About Wishes While the Conversation Is Still EasyLegal planning works best when paired with conversation.Ask:Who would you trust to handle finances?Who should speak with physicians?What matters most if your health changes?Would you prefer to remain at home if possible?How should long-term care decisions be approached?These conversations may feel uncomfortable.But they can be much harder when a family is already dealing with hospitalization, dementia progression, or another crisis.Idaho's advance directive guidance specifically encourages people to reflect on personal values and discuss wishes with the healthcare agent they appoint.When Should a Boise Family Consider an Elder Law Consultation?Families may want legal guidance when:No power of attorney exists.Existing documents are decades old.A parent has received a dementia diagnosis.There is uncertainty about whether someone still has legal capacity.Family members disagree about decision-making.A spouse can no longer manage finances.Guardianship or conservatorship may be necessary.Long-term care and Medicaid planning overlap with incapacity concerns.A named agent is no longer appropriate or available.Ahrens DeAngeli Law Group provides elder law services from its Boise office at 420 West Main Street, Suite 305, with 208-387-0729 listed as the firm's elder law phone number.Frequently Asked Questions About Incapacity Planning in IdahoWhat is the difference between a power of attorney and guardianship?A power of attorney is generally created voluntarily by an individual who appoints another person to act on their behalf. Guardianship is a court-created arrangement in which a judge appoints someone to make personal or healthcare decisions for a person who cannot adequately manage those matters.What is the difference between a guardian and a conservator?In Idaho, a guardian generally handles personal or health-related decisions, while a conservator manages finances and property.What does an Idaho Advance Directive include?Idaho's Advance Directive includes a Durable Power of Attorney for Healthcare and a Living Will. The healthcare power of attorney allows someone to appoint a healthcare agent who can speak on their behalf when they cannot make or communicate medical decisions.Can an Idaho Advance Directive be stored online?Yes. Idaho maintains a Healthcare Directive Registry where individuals can create, upload, store, and share advance directives securely.Can powers of attorney help avoid guardianship or conservatorship?In some situations, properly created powers of attorney or trusts may provide enough authority that formal court-appointed conservatorship or guardianship is unnecessary. Whether that is possible depends on the individual's circumstances and the documents already in place.Make Important Decisions Before a Crisis Makes Them HarderIncapacity planning is not about expecting the worst.It is about deciding who you trust before someone else must solve that question under pressure.Who should handle finances?Who should speak with healthcare providers?What treatments matter to you?What happens if dementia progresses?Could powers of attorney provide enough support?Would a guardian or conservator ever become necessary?These are easier questions to address when the older adult can actively participate.For families in Boise and Ada County, Ahrens DeAngeli Law Group focuses on elder law and related planning issues that can arise as health, cognition, long-term care needs, and family responsibilities change. Its elder law resources emphasize the importance of financial and healthcare powers of attorney and planning before legal capacity becomes a concern.Idaho also provides formal resources for advance directives, guardianship, conservatorship, and supported decision-making, giving families several different legal tools depending on the individual's abilities and circumstances.To learn more about local elder law guidance, connect with Ahrens DeAngeli Law Group through their SeniorsBlueBook.com business profile: [SBB Listing URL].Planning while someone can still clearly express their wishes may give families something particularly valuable later: confidence that important decisions are being made according to the older adult's own choices rather than simply because a crisis left no other option.
Sep 23, 2026

Understanding Elder Law in Boise, Idaho: Protecting the Rights, Assets, and Dignity of Seniors
Understanding Elder Law in Boise, Idaho: Protecting the Rights, Assets, and Dignity of SeniorsPlanning for the future is one of the most important acts of care you can take for yourself and your loved ones. As we age, legal considerations surrounding health care, finances, housing, and long-term planning become increasingly complex. This is where Elder Law comes in and why the Ahrens Deangeli Law Group in Boise, Idaho, has earned a trusted reputation for guiding seniors and families through lifes most sensitive transitions with clarity, compassion, and expertise.What Is Elder Law?Elder Law is a specialized field of legal practice focusing on the unique needs of older adults. It covers a broad range of issues that affect aging individuals, such as:Estate planning and willsPowers of attorney and advance health care directivesGuardianships and conservatorshipsLong-term care planningMedicaid and Veterans benefitsProbate and trust administrationAsset protection and retirement planningUnlike general legal services, Elder Law attorneys take a holistic view of their clients wellbeing addressing financial, medical, and personal matters that intersect during the later stages of life.Why Elder Law Matters in Boise, IdahoBoise and the Treasure Valley are among the fastest-growing areas in the Pacific Northwest, and that includes their senior populations. According to the Idaho Department of Health and Welfare, more than 17% of Ada County residents are age 65 or older, a number expected to rise sharply over the next decade.As more families move to Boise for its quality of life and affordability, the demand for experienced Elder Law services has grown. From estate planning to Medicaid qualification, having a local attorney who understands both Idahos laws and the communitys resources can make all the difference.Boises mix of urban convenience and close-knit neighborhoods also means that seniors here often want to remain in their homes as long as possible. A thoughtful Elder Law plan ensures they can do so safely while also protecting assets, honoring healthcare wishes, and preparing for potential care transitions.The Ahrens Deangeli Law Group DifferenceFounded on integrity, experience, and a commitment to personalized service, Ahrens Deangeli Law Group has become a leading name in Elder Law throughout Idaho and the Mountain West. Their Boise office provides comprehensive legal solutions that adapt to each clients personal and financial circumstances.A Team Centered on Trust and ExpertiseEvery seniors situation is unique. Whether youre a retiree looking to update your will, a family member navigating Medicaid eligibility for a parent, or a caregiver managing complex financial matters, Ahrens Deangelis attorneys bring both technical skill and human understanding to each case.Tip from the team:Elder Law isnt just about preparing documents its about building peace of mind, says Joshua Reams of Ahrens Deangeli Law Group. We focus on helping families protect what matters most their loved ones, their legacy, and their sense of security.Key Areas of Elder Law Services1. Estate Planning and Asset ProtectionEstate planning is the foundation of a secure future. The team helps seniors create or update wills and trusts, designate powers of attorney, and structure assets to minimize taxes or legal disputes. Proper estate planning ensures your wishes are honored and your family avoids unnecessary stress during transitions.2. Long-Term Care and Medicaid PlanningWith the cost of long-term care steadily increasing, its vital to plan early. Medicaid eligibility rules are complex and can easily overwhelm families. Ahrens Deangeli Law Group helps clients legally protect their assets while still qualifying for essential care benefits, including nursing home or in-home care coverage.3. Guardianships and ConservatorshipsWhen a loved one becomes unable to make safe or informed decisions, establishing legal guardianship or conservatorship may be necessary. The firm provides compassionate guidance throughout these sensitive proceedings to ensure the seniors dignity and best interests are preserved.4. Probate and Trust AdministrationLosing a loved one is difficult enough without navigating complicated probate laws. The firm assists executors and families through every step of the estate administration process from validating wills to distributing assets while ensuring compliance with Idahos probate code.5. Special Needs and Disability PlanningFor families caring for an adult child or loved one with disabilities, special needs trusts can protect eligibility for government benefits while providing long-term financial stability. Ahrens Deangeli Law Group designs customized plans to safeguard these critical supports.How Elder Law Empowers FamiliesWorking with an Elder Law attorney is more than just checking a box. Its about creating confidence for the years ahead.Here are a few ways proactive planning can benefit Boise families:Preserve assets from being depleted by nursing home or medical costsAvoid family conflict through clear legal instructionsPrevent financial exploitation or elder abuseEnsure medical wishes are honored through advance directivesSimplify transitions for heirs and caregiversAccess government programs and community resources efficientlyIn a city like Boise known for its strong sense of community and neighborly support Elder Law planning reinforces the values that make the Treasure Valley such a special place to grow older.Local Insight: Elder Care in BoiseBoise continues to attract retirees who value its balance of natural beauty, accessible healthcare, and low crime rate. With St. Lukes Boise Medical Center and Saint Alphonsus Regional Medical Center providing exceptional geriatric and rehabilitation services, seniors in the region have access to comprehensive care networks.However, as Idahos senior population increases, so does the need for integrated legal and care planning. Many residents are turning to Ahrens Deangeli Law Group to help coordinate between financial advisors, healthcare providers, and family members to build cohesive plans that protect every aspect of senior life.Frequently Asked Questions About Elder Law1. Whats the difference between an Elder Law attorney and a general attorney?Elder Law attorneys specialize in the needs of aging clients including long-term care, Medicaid, and estate planning whereas general attorneys may not have the same depth of knowledge in these areas.2. When should I start planning for long-term care?Ideally, begin planning before care is needed. Early planning allows you to explore more options, protect assets, and avoid crisis-driven decisions.3. Can I protect my home if I need to go into a nursing facility?Yes, there are legal strategies that can help safeguard your home and other assets while still qualifying for Medicaid. These should be implemented carefully with the help of a qualified Elder Law attorney.4. What happens if I dont have a power of attorney or will?Without these documents, the court may appoint someone to make decisions for you or distribute your assets according to state law not necessarily according to your wishes. Drafting these now ensures your preferences are respected.5. Does Elder Law cover issues for younger adults with disabilities?Absolutely. Elder Law also addresses planning for individuals with long-term disabilities, including special needs trusts and guardianship arrangements.Why Choose a Local Boise Elder Law FirmChoosing a Boise-based Elder Law attorney means working with professionals who understand Idahos unique laws and the local senior care landscape. The Ahrens Deangeli Law Group works closely with area resources, including senior centers, care facilities, and medical providers, to ensure clients receive seamless support from every direction.Their long-standing commitment to Idaho families has made them a trusted partner in Elder Law, estate planning, and long-term care strategy.Take the Next Step Toward Peace of MindWhether youre beginning your retirement journey, helping an aging parent plan for the future, or navigating a sudden change in health or finances, the Ahrens Deangeli Law Group in Boise is here to help. Their compassionate attorneys understand that every clients situation is unique and every plan should be too.Visit their Seniors Blue Book profile to learn more or request a consultation: Ahrens Deangeli Law Group Boise, ID
Oct 13, 2025
How Families Can Prepare Before a Long-Term Care Crisis
How Families Can Prepare Before a Long-Term Care CrisisMost families do not wake up one morning thinking, Today is the day we need an elder law attorney.The need usually develops more gradually.A parent begins needing more help at home. A spouse receives a dementia diagnosis. Someone starts researching assisted living or nursing care and is surprised by the potential cost. Adult children realize they do not know who has legal authority to manage finances if Mom or Dad can no longer do so independently.Then a hospital stay, fall, or sudden change in health can turn questions that once felt theoretical into decisions that need answers quickly.For older adults and families in Boise and Ada County, Idaho, elder law planning can help connect several issues that often overlap as people age: estate planning, incapacity, long-term care, Medicaid, veterans benefits, asset protection, and decision-making authority.Elder Law at Ahrens DeAngeli Law Group, based at 420 West Main Street, Suite 305 in Boise, focuses on elder law and related areas including Medicaid planning, elder-focused estate planning, veterans benefits planning, and Alzheimer's planning. The firm also assists families facing long-term care and asset-preservation questions.The important point is that elder law planning does not have to begin during an emergency.In many situations, starting earlier gives families more time to understand their choices.Why Elder Law Matters for Boise and Ada County FamiliesBoise and Ada County have substantial older-adult populations.The U.S. Census Bureau estimated Boise's population at 238,429 in 2025, with 16.2% of residents age 65 or older. Ada County's estimated population reached 546,141, with adults age 65 and older representing 18.1% of county residents.That means thousands of local households are navigating questions involving retirement, caregiving, estate planning, dementia, long-term care, and financial preparation.Many of those questions do not fit neatly into a single category.For example, moving a spouse into long-term care can involve:Healthcare decisionsFinancial accountsProperty ownershipMedicaid rulesInsuranceEstate planning documentsPowers of attorneyThe financial security of the spouse remaining at homeAn elder law attorney looks at how those issues interact rather than treating each one as an isolated problem.Elder Law Planning Tip: Do not wait until someone has lost decision-making capacity to review legal documents. Planning is generally easier when the older adult can clearly participate in decisions and explain what they want.Elder Law Is More Than Writing a WillEstate planning is an important part of elder law, but elder law goes beyond deciding who inherits property.A traditional estate plan often focuses heavily on what happens after death.Elder law also asks:What happens if I am still living but can no longer manage everything myself?That question may become increasingly important with age.A thoughtful plan may need to address:Who can manage finances if you become incapacitated?Who can make healthcare decisions?What are your wishes regarding medical treatment?How will long-term care be paid for?What happens to a spouse's finances if one partner needs expensive care?Could Medicaid or veterans benefits eventually be relevant?Are existing wills and trusts still appropriate?How should property be titled?Ahrens DeAngeli Law Group describes its approach as elder-focused estate planning that can incorporate long-term care concerns rather than considering inheritance planning by itself.Powers of Attorney Can Become Critical During a Health CrisisMany families assume that an adult child or spouse will automatically be able to handle financial matters when someone becomes ill.That is not always the case.A properly prepared power of attorney can authorize a trusted person to act on another person's behalf in specified circumstances.Depending on the document and situation, this may involve tasks such as:Paying billsManaging financial accountsHandling certain property mattersWorking with benefit programsManaging other financial affairsAhrens DeAngeli Law Group identifies powers of attorney as important documents for caregiving and notes that appropriate legal authority can become important when caregivers need to manage finances or pursue financial assistance for a loved one.Healthcare decision-making documents can be equally important.Families should review these documents while the older adult is able to meaningfully participate in planning.Waiting until someone has significantly impaired capacity may reduce available options and could lead to more complicated legal proceedings.Long-Term Care Planning Is Often a Financial Planning Issue TooOne of the biggest concerns families bring to elder law attorneys is how to pay for long-term care.Care might eventually include:Help at homeAssisted livingMemory careSkilled nursingOther long-term supportCosts can accumulate quickly, particularly when care continues for months or years.Ahrens DeAngeli Law Group's elder law practice places significant emphasis on long-term care planning, Medicaid eligibility, and strategies intended to preserve appropriate resources while helping families plan for necessary care.The right strategy varies greatly from person to person.A married couple may face different rules and planning considerations from a single adult.Someone who owns a home may have different concerns from someone who rents.An individual with long-term care insurance will have a different financial picture from someone without coverage.That is why general advice from friends or online discussions should not be treated as individualized legal guidance.Understanding Medicaid PlanningMedicaid can become relevant when an older adult requires long-term care and meets applicable financial and functional eligibility requirements.However, Medicaid planning can be complicated.Idaho's eligibility framework includes income limits, resource limits, spouse-related protections, transfer rules, and other requirements. Ahrens DeAngeli Law Group publishes a 2026 Medicaid desk reference and emphasizes that these figures and rules require careful application to each person's circumstances.Families sometimes hear statements such as:You have to spend everything first.Just give the house to the kids.Move the money out of Mom's name.Medicaid will never help because Dad has savings.Statements like these can be incomplete or potentially harmful when applied without understanding the law.Transfers of property or money can have consequences for Medicaid eligibility, which is one reason Ahrens DeAngeli specifically advises families to obtain knowledgeable legal guidance before making gifts or transferring assets as part of long-term care planning.Medicaid Planning Is Not Only for People Already in a Nursing HomeSome people associate Medicaid planning entirely with an immediate long-term care crisis.Planning can also begin earlier.Ahrens DeAngeli distinguishes between crisis Medicaid planning, when someone already needs nursing-home care or is likely to enter care soon, and Medicaid pre-planning, when a person is still relatively healthy but wants to prepare for possible future incapacity or long-term care.Planning earlier may provide time to review:Existing estate documentsProperty ownershipAvailable financial resourcesLong-term care insurancePotential benefit eligibilityFamily goalsPossible future care needsIt does not mean someone is predicting that nursing care will definitely be needed.It means they are preparing for the possibility.Dementia Can Make Legal Planning More UrgentA diagnosis of Alzheimer's disease or another form of dementia can change many parts of family life.Early in the disease, someone may still be capable of participating meaningfully in legal and financial planning.As the condition progresses, that ability may change.Ahrens DeAngeli's Alzheimer's planning resources emphasize reviewing powers of attorney, healthcare directives, wills, trusts, property ownership, long-term care planning, and financial strategies after significant cognitive changes or an Alzheimer's diagnosis.For families, important questions may include:Who can manage finances?Who can communicate with financial institutions?Who can make healthcare decisions?Are current estate documents still appropriate?How will care be paid for?Could Medicaid become relevant?Is long-term care insurance available?What happens if the primary caregiver can no longer provide care?These conversations may be emotionally difficult.But addressing them while the individual can participate may preserve more choice.Review Estate Planning Documents as Life ChangesA will or trust created 15 years ago may still be legally valid while no longer reflecting someone's current circumstances.Life changes.Children marry or divorce.Grandchildren are born.A spouse dies.Assets change.Someone sells a business.Health needs develop.Family relationships change.Ahrens DeAngeli recommends revisiting wills and trusts when major life events occur and incorporates long-term care concerns into its elder-focused estate planning services.Families may want to review:WillsTrustsPowers of attorneyHealthcare directivesBeneficiary designationsProperty titlesAn attorney can help determine whether changes are appropriate rather than assuming an older document still accomplishes the intended goal.Property Ownership Can Affect More Than InheritanceHow property is titled can affect what happens during incapacity and after death.Homes, bank accounts, investments, and other assets may be owned individually, jointly, through trusts, or with beneficiary arrangements.These details can influence whether court involvement becomes necessary.Ahrens DeAngeli notes that probate is generally used when assets titled in a deceased person's name must be legally transferred and that some assets may pass through other mechanisms depending on how they are titled or designated.Property ownership can also interact with long-term care and Medicaid planning.Because the consequences can be substantial, families should avoid retitling assets simply because a friend or relative used a particular strategy.The appropriate structure depends on the individual's circumstances.Veterans Benefits May Be Worth ExploringSome older adults or surviving spouses may qualify for benefits connected to military service.Ahrens DeAngeli includes veterans benefits planning among its elder law practice areas, and attorneys within the practice have experience addressing veterans-related benefit considerations alongside long-term care and estate planning.Eligibility depends on the specific benefit and individual circumstances.Families should gather information about military service when preparing for an elder law consultation, particularly when the older adult or a deceased spouse served in the military.Veterans benefits should also be considered alongside other financial resources rather than viewed in isolation.What Should You Bring to an Elder Law Meeting?Legal planning becomes easier when families arrive with organized information.Ahrens DeAngeli's planning materials ask clients to gather financial statements, existing estate planning documents, and real-property information before a consultation.Depending on the situation, useful documents may include:Existing wills and trustsPowers of attorneyHealthcare directivesRecent bank and investment statementsProperty deedsLong-term care insurance policiesInformation about pensions or retirement accountsLife insurance informationVeterans-service informationDetails about current or anticipated long-term careA current list of important family contactsDo not worry if everything is not perfectly organized.The purpose of the first conversation is often to identify what information matters and what additional documents may be needed.When Should a Boise Family Talk With an Elder Law Attorney?There is no single perfect age.Several situations may make a consultation worth considering:A parent has received a dementia diagnosis.A spouse may soon need assisted living or nursing care.The family is concerned about long-term care costs.Existing estate documents are old.No power of attorney is in place.An older adult wants to plan before health changes.Medicaid eligibility questions have arisen.A veteran or surviving spouse may have benefit questions.Someone has been told they must spend down substantial assets before receiving assistance.Family members are unsure who has authority to make decisions.The key is not waiting until every question becomes urgent.Frequently Asked Questions About Elder Law in BoiseWhat does an elder law attorney do?Elder law attorneys address legal concerns that commonly affect older adults and their families. Depending on the firm and circumstances, this may include estate planning, powers of attorney, long-term care planning, Medicaid, veterans benefits, incapacity planning, guardianship or conservatorship, probate, and related matters. Ahrens DeAngeli specifically identifies elder law, Medicaid planning, estate planning, veterans benefits, and Alzheimer's planning among its core services.Should I meet with an elder law attorney before I need long-term care?Planning early can be useful because it allows an older adult to participate fully in decisions and gives the family time to review legal documents, finances, benefits, and potential long-term care strategies. Ahrens DeAngeli offers both advance planning and assistance for families already experiencing a Medicaid or long-term care crisis.Can an elder law attorney help with Medicaid planning?Yes. Medicaid planning is one of Ahrens DeAngeli Law Group's stated elder law practice areas. Because Idaho Medicaid rules contain detailed financial requirements and are updated over time, individual legal advice may be particularly important before transferring assets or making major financial changes.Does Ahrens DeAngeli Law Group help families dealing with Alzheimer's disease?Yes. Alzheimer's planning is a stated practice area. The firm's resources discuss powers of attorney, healthcare directives, estate documents, property ownership, long-term care, and benefit planning for families dealing with cognitive decline.Where is Ahrens DeAngeli Law Group's elder law office in Boise?The Boise elder law office is located at 420 West Main Street, Suite 305, Boise, Idaho 83702. The firm currently lists 208-387-0729 as its phone number.Plan Before a Crisis Makes the Decisions for YouAging brings legal questions that often connect directly to healthcare, housing, finances, and family responsibilities.Who can make decisions?How will long-term care be funded?What happens if someone develops dementia?Are estate planning documents still appropriate?Could Medicaid or veterans benefits eventually help?These questions are easier to address when families have time to understand their options.For older adults and families in Boise and Ada County, Ahrens DeAngeli Law Group focuses its elder law practice on the legal and financial issues associated with aging, including Medicaid planning, elder-focused estate planning, veterans benefits, Alzheimer's planning, long-term care, and asset preservation.The firm also maintains a Seniors Blue Book profile serving Ada and Canyon counties, giving local families another way to review information and make contact.To learn more, connect with Ahrens DeAngeli Law Group through its SeniorsBlueBook.com business profile.Good elder law planning is not about assuming something will go wrong. It is about making important decisions while there is still time to make them thoughtfullyand giving seniors and their families a clearer plan for whatever comes next.
Sep 23, 2026

Don't Lose Your Life Savings to Long Term Care Costs-Lifelines for Seniors and Their Families
Don't Lose Your Life Savings to Long-Term Care Costs: Lifelines for Seniors and Their Families(1) Medicaid: The A&D WaiverNavigating the high costs of long-term care can be incredibly stressful. We recently met a woman whose husband was paying thousands monthly for care. They were told he couldn't receive Medicaid help because their life savings, held in an annuity, were "too much." The advice they received was to cash it out and spend most of it, leaving very little for her.This is heartbreaking, but it's not always true that you have to spend everything you have. In this case, we made some important changes to their annuity. Within weeks, her husband was approved for Medicaid, even with the same savings! This allowed the wife to keep their nest egg while her husband received the care he needed.Are you facing similar concerns? You're not alone. Many families find it impossible to afford steep monthly care costs. It's especially tough when one spouse needs care, but they worry about using all their savings, potentially leaving the healthier spouse with nothing.The good news is that it is possible to get help paying for care without losing everything you've worked for. The key is understanding how to qualify for available programs and using the rules to your advantage. Another family was told to purchase a costly Medicaid Annuity, but the rules allowed their family to appeal their initial application and keep all their assets without any further steps. Medicaid has specific rules about assets and income. However, it also has provisions that can be used strategically to benefit the person who needs care and their family. Even if you believe your loved one won't qualify, don't assume the worst. As our examples demonstrate, a skilled elder law attorney can sometimes use Medicaid rules to help a person qualify before their money is gone. (2) Help for Veterans and Their Spouses: The Aid & Attendance ProgramFor veterans and their spouses, the Aid and Attendance program can provide significant financial help for long-term care. A married veteran paying for care might qualify for up to $2,795.67 per month from the VA.To qualify, many veterans only need to have: Served at least 90 days active duty, with one day during a period of war. Received an honorable discharge. A service-connected disability is not required! While there are asset and income rules, don't give up if initially told you don't qualify. It's crucial to consult a VA-accredited elder law attorney. A knowledgeable advisor can often help families adjust their situation to become eligible.Don't Fall for Misconceptions Get the Right Advice!Many myths exist about long-term care and how to pay for it. Resources are available, but you often need proper planning and expert legal guidance. Even if you haven't planned far in advance, don't give up hope if discouraging advice comes from a friend or even another professional. Unfortunately, incorrect information is common.Your lifetime of hard work deserves protection. Find a qualified elder law attorney in Idaho who can help you understand your options and ensure your family's financial security.Joshua C. P. Reams, B.A., J.D., NAELAElder Law Attorney, VA AccreditedDavid J. Wilson, J.D., L.L.M., CELA Board Certified Elder Law Attorney
Aug 28, 2025
Preserving Assets Amid Rising Long Term Care Costs: Strategic Resource
Preserving Assets Amid Rising Long-Term Care Costs: Strategic Resources for Seniors and FamiliesNavigating the financial complexities of long-term care can be challenging for families. A primary concern for many couples is the fear that securing necessary care for one spouse will deplete their shared life savings, leaving the healthier spouse financially vulnerable.Fortunately, strict "spend-down" requirements are not always mandatory. With strategic planning, families can often qualify for state and federal assistance programs while legally protecting their hard-earned assets.1. Medicaid: The Aged & Disabled (A&D) WaiverMany families operate under the misconception that they must completely liquidate their assets to meet Medicaid eligibility thresholds. For example, a couple was recently advised to cash out a sizable annuity and spend the proceeds before applying for assistance. This advice would have left the wife with minimal financial security.By implementing compliant asset-restructuring strategies, the husband successfully qualified for Medicaid within weekswithout liquidating the annuity. This allowed the husband to receive critical care while preserving the couple's primary nest egg. In another instance, a family avoided purchasing an expensive Medicaid Annuity altogether by leveraging asset rules to successfully appeal an initial application denial.Medicaid guidelines regarding income and assets are complex, but they include specific provisions designed to protect the "community spouse" (the spouse remaining at home). Rather than assuming ineligibility, families should consult a skilled elder law attorney who can utilize these rules to accelerate qualification while safeguarding family assets.2. Veterans Benefits: The Aid & Attendance PensionFor wartime veterans and their surviving spouses, the Department of Veterans Affairs (VA) offers the Aid & Attendance program. This benefit provides significant monthly supplemental income to help offset the costs of home health care, assisted living, or nursing home care. For instance, a married veteran paying for long-term care may qualify for up to $2,874 per month.Core Eligibility Criteria: Service Requirement: A minimum of 90 days of active duty, with at least one day served during a recognized period of war. Discharge Status: An honorable or general discharge. Disability Status: A service-connected disability is not required. While the VA enforces strict net-worth and income limits, an initial calculation that exceeds these limits does not mean eligibility is impossible. A VA-accredited elder law attorney can assist families in structured planning to meet these criteria legally.Mitigating Risk through Professional PlanningMisinformation regarding asset limits, look-back periods, and eligibility rules is common. Relying on anecdotal advice from friends or misinformed professionals can lead to costly, irreversible financial errors.Protecting a lifetime of savings requires proactive planning and precise legal execution. Families facing long-term care decisions are strongly encouraged to retain a qualified elder law attorney in Idaho to evaluate their options, maximize available benefits, and secure their financial future.Joshua C. P. Reams, B.A., J.D.Elder Law Attorney, VA AccreditedDavid J. Wilson, J.D., L.L.M., CELABoard Certified Elder Law Attorney
Jul 23, 2026
What Idaho Families Should Know Before a Crisis
What Idaho Families Should Know Before a CrisisLong-term care planning often begins with a deceptively simple question:How will we pay for care if Mom or Dad eventually needs more help?The answer can become complicated quickly.An older adult may need assistance at home for several years. Another person may eventually move to memory care. Someone recovering from a major health event may need skilled nursing care. A married couple may worry that paying for one spouse's care could leave the other spouse without enough money to maintain the household.Then Medicaid enters the conversation.Families hear different versions of the rules from friends, relatives, websites, care communities, and other professionals. One person says the family must spend everything. Someone else recommends transferring the house. Another insists that having savings makes Medicaid impossible.In reality, Idaho Medicaid rules for long-term care involve income, resources, functional care needs, marital circumstances, transfers, and other factors that should be evaluated together.For seniors and families in Boise and Ada County, Idaho, Ahrens DeAngeli Law Group focuses its elder law practice on issues that include Medicaid planning, elder-focused estate planning, veterans benefits, Alzheimer's planning, and long-term care. The firm's elder law office is located at 420 West Main Street, Suite 305 in Boise.Understanding the basics before a crisis can help families recognize which questions require individualized legal guidance.Long-Term Care Planning Is Increasingly Relevant in Ada CountyAda County continues to grow and has a substantial older-adult population.The U.S. Census Bureau estimated the county's population at 546,141 residents in 2025, with adults age 65 and older representing approximately 18.1% of the population. Boise itself had an estimated 238,429 residents, with approximately 16.2% age 65 or older.That means tens of thousands of local residents are navigating questions about retirement, aging at home, caregiving, assisted living, memory care, skilled nursing, and how future care may be financed.Long-term care planning is not only relevant for people who are already in nursing facilities.It can also help relatively healthy adults understand what options may exist if their needs eventually change.Long-Term Care Planning Tip: Before transferring property, changing account ownership, or making large gifts because you are worried about Medicaid, get current Idaho-specific advice. A financial move that appears simple can affect future eligibility.What Does Medicaid Have to Do With Long-Term Care?Medicaid is a public health coverage program, but certain Medicaid programs can also help eligible individuals pay for long-term care.The Idaho Department of Health and Welfare states that someone entering a nursing home may qualify for Medicaid assistance with nursing-home costs depending on income, resources, household circumstances, and care needs.Medicaid may also support certain Home and Community Based Services, depending on eligibility and the required level of care.This is different from assuming Medicaid automatically pays for every type of senior living.Coverage depends on the program, the person's circumstances, financial eligibility, functional eligibility, and the type of care involved.That is one reason families should avoid treating Medicaid as one simple set of rules.Financial Eligibility Is Only Part of the ProcessFamilies sometimes focus entirely on income and savings.Those factors matter, but they are not the whole picture.Idaho explains that a person seeking Medicaid for nursing-home or certain home- and community-based services may also need a Level of Care Determination. This process evaluates whether the individual requires the type of care provided in a nursing home or long-term care setting.In other words, qualifying financially does not automatically establish that someone meets the care criteria for a particular long-term care Medicaid program.Families may need to address both:Financial eligibilityFunctional or level-of-care eligibilityThis distinction is important when someone is planning ahead.Idaho's 2026 Medicaid Limits Are Only a Starting PointThe Idaho Department of Health and Welfare publishes current income and resource guidelines for Medicaid programs.Effective January 2026, Idaho's published table for Long-Term Facility Care lists a monthly income limit of $3,002 for an individual and an individual resource limit of $2,000. Idaho lists the same individual figures for Home and Community Based Services.Those numbers should not be viewed as a complete eligibility test.Married couples can be subject to additional rules regarding income, ownership, resources, and protection for the spouse remaining at home. Idaho's nursing-home guidance specifically explains that income can be treated differently between spouses and that, after Medicaid eligibility is established, some income may potentially be used to support the spouse living in the community.This is why a family should not conclude:Mom has more than $2,000, so there is nothing we can do.or:Dad's monthly income is above the number, so he can never qualify.The analysis can be more complicated than a single number.Married Couples Need Special AttentionLong-term care planning can be particularly stressful for married couples.Imagine that one spouse needs nursing-home care while the other continues living at home.The spouse remaining at home may still need money for:Mortgage or rentProperty taxesUtilitiesFoodTransportationInsuranceMedical careTheir own future needsFamilies are often afraid that everything must be spent on the spouse receiving care.Idaho Medicaid rules recognize that married couples require special treatment.The Department of Health and Welfare explains that eligibility calculations may involve determining how income belongs to each spouse, and in some situations a portion of the Medicaid recipient's income may help support the spouse remaining at home.The exact result depends on individual circumstances.For that reason, married couples facing long-term care should be especially cautious about applying general Medicaid advice found online.Do Not Transfer Assets Simply Because Someone Says You ShouldOne of the most common long-term care planning mistakes is making major financial transfers without understanding the consequences.A family may hear:Put the house in your daughter's name.Give the savings to the grandchildren.Move everything into someone else's account.These suggestions may sound straightforward.Medicaid eligibility rules, however, can take transfers into account.Idaho Health and Welfare specifically warns that transferring income between spouses or to another person without following applicable rules could delay or affect benefits and advises individuals to contact the department before taking action.Ahrens DeAngeli also emphasizes that Medicaid law is complex and that families often receive incomplete or outdated information when they are trying to determine eligibility.A transaction that seems helpful today can create complications later.That does not mean no planning strategies exist.It means strategies should be designed for the actual family rather than copied from someone else's situation.Medicaid Crisis Planning and Pre-Planning Are DifferentAhrens DeAngeli distinguishes between two broad situations.Medicaid Crisis PlanningA crisis may occur when someone has already entered a nursing facilityor needs to enter one very soonand the family discovers that available assets appear too high for Medicaid eligibility.At this stage, decisions may need to be made quickly.Ahrens DeAngeli states that it assists families who are already facing long-term care expenses and Medicaid eligibility questions, including situations where an application has previously been denied.Medicaid Pre-PlanningPre-planning happens before care becomes urgent.Someone may still be living independently but wants to prepare for possible future incapacity or long-term care.The firm describes Medicaid pre-planning as part of an elder-focused estate planning approach that considers future care needs and asset protection before a crisis occurs.Pre-planning may provide more time to review:Estate documentsProperty ownershipFinancial accountsInsuranceFamily goalsPowers of attorneyPotential long-term care optionsStarting early does not mean someone expects to enter a nursing home.It means the family understands that aging plans should account for more than inheritance.Long-Term Care Insurance Should Be Reviewed Alongside MedicaidSome families own long-term care insurance policies purchased years ago.These policies may potentially help pay for certain services such as:Care at homeAssisted livingMemory careNursing careCoverage depends entirely on the contract.A recent Seniors Blue Book article associated with Ahrens DeAngeli explains that long-term care insurance can involve questions about covered settings, benefit triggers, elimination periods, and how Medicaid may eventually fit into the picture if private insurance benefits are exhausted.Families should locate the policy before care is urgently needed.Ask:What triggers benefits?Which care settings are covered?How much does the policy pay?How long can benefits continue?Is inflation protection included?Is dementia or cognitive impairment addressed?Who should be contacted to begin a claim?Insurance, Medicaid, private savings, veterans benefits, and other resources may all form part of the same broader long-term care strategy.Estate Planning Should Coordinate With Long-Term Care PlanningA will alone does not solve a long-term care problem.Someone may have an excellent plan for transferring property after death but no plan for managing finances while living with dementia or paying for several years of care.Ahrens DeAngeli identifies elder-focused estate planning as one of its core practice areas alongside Medicaid planning.Documents worth reviewing may include:WillTrustFinancial power of attorneyHealthcare directiveBeneficiary designationsProperty ownership documentsA recent Seniors Blue Book article from the firm also emphasizes that estate planning involves much more than a will and can address decision-making during incapacity as well as asset and family considerations.The right estate plan should reflect the person's current goals and circumstances.Powers of Attorney Can Matter During Medicaid PlanningLong-term care planning often requires someone to communicate with agencies, financial institutions, insurers, and care providers.If the older adult becomes unable to manage those tasks independently, the family needs to know who has legal authority to act.That is why powers of attorney can be important before a crisis.Families should review:Who is currently namedWhether that person is still appropriateWhether the document remains validWhether it gives sufficient authority for the tasks that may ariseWaiting until an individual no longer has capacity to sign appropriate documents may make planning substantially more difficult.Do Not Assume Nursing Home Care Is the Only Medicaid-Supported OptionWhen people hear Medicaid long-term care, they often think only of nursing facilities.Idaho also administers Home and Community Based Services, subject to financial and level-of-care requirements.This can matter for families whose goal is to support an older adult in a home or community setting when appropriate.The specific services available, eligibility requirements, and care arrangements should be confirmed through Idaho Medicaid and appropriate professionals.Families should not assume that qualifying for one Medicaid program automatically qualifies someone for every type of service.Keep Documentation OrganizedApplying for long-term care Medicaid can require detailed financial and personal information.Idaho states that applicants may need to provide documentation concerning:IdentityHousehold incomeHousehold resourcesMonthly expensesOther eligibility-related informationFamilies can reduce stress by organizing records before a crisis.Consider creating a file containing:Recent bank statementsInvestment statementsRetirement accountsPension informationSocial Security incomeProperty informationInsurance policiesLong-term care insurancePowers of attorneyEstate planning documentsMajor recent financial transactionsThe purpose is not to determine eligibility on your own.It is to make the necessary information easier to find when professionals need it.Be Careful With Advice From People Who Are Not Reviewing the Full PictureSocial workers, care community staff members, friends, and family members can all be helpful resources.But no single person may know every detail of the older adult's financial, legal, and family circumstances.Ahrens DeAngeli specifically notes that families facing Medicaid crises frequently receive information from well-intentioned sources that may be incomplete, outdated, or insufficient for individualized planning.When major assets, a spouse's financial security, property ownership, or long-term eligibility are involved, families may benefit from legal advice that is specific to Idaho and to their circumstances.Medicaid Applications Can Require Ongoing AttentionMedicaid eligibility is not necessarily a one-time process.Idaho states that individuals receiving Medicaid undergo an annual re-evaluation and receive instructions regarding renewal.Families should maintain records even after approval.Changes involving:IncomeResourcesResidenceHousehold circumstancesCare needsmay need to be reported or reviewed.Staying organized can make future re-evaluations easier.What If Medicaid Is Denied?A Medicaid denial does not necessarily mean every option has been exhausted.Idaho provides appeal and fair-hearing rights for certain eligibility decisions.Ahrens DeAngeli also states that its attorneys work with families facing Medicaid crises, including situations where an application has previously been denied.The appropriate response depends on why the application was denied.Families should review the written notice carefully rather than assuming the denial means permanent ineligibility.Frequently Asked Questions About Medicaid Planning in BoiseDoes Idaho Medicaid help pay for nursing-home care?Potentially. Idaho states that Medicaid may help eligible individuals pay a portion of nursing-home costs. Eligibility depends on income, resources, household circumstances, and level-of-care requirements.What is Idaho's Medicaid income limit for long-term facility care in 2026?Idaho's published 2026 table lists $3,002 per month for an individual for Long-Term Facility Care, along with an individual resource limit of $2,000. These figures do not explain every eligibility rule, particularly for married couples.Can a spouse remain at home while the other spouse receives Medicaid-supported long-term care?Potentially. Idaho has specific rules for married couples and explains that income may be treated differently between spouses, with certain provisions potentially supporting the spouse who remains at home. Individual circumstances must be evaluated.Should I give away assets before applying for Medicaid?Families should not make significant gifts or transfers solely to try to qualify for Medicaid without obtaining current professional guidance. Transfers can affect eligibility, and Idaho advises people to understand the rules before moving income or resources.Does Ahrens DeAngeli Law Group help with Medicaid planning?Yes. Medicaid planning is one of the firm's stated elder law practice areas. It assists with both advance planning and situations where someone already needs long-term care.Start Long-Term Care Planning Before Every Choice Becomes UrgentLong-term care can affect far more than healthcare.It can affect:A spouse's financial security.A family home.Retirement savings.Estate planning.Insurance.Caregiving responsibilities.And the older adult's ability to choose how and where care is received.For Boise and Ada County families, understanding Medicaid can be part of that planningbut Medicaid should not be viewed as a simple checklist or a last-minute financial trick.Idaho's rules involve income, resources, care needs, marital circumstances, and ongoing eligibility requirements.Ahrens DeAngeli Law Group focuses its elder law practice on Medicaid planning, estate planning, veterans benefits, Alzheimer's planning, guardianship and conservatorship matters, and other legal issues affecting older adults and their families. Its Seniors Blue Book profile identifies the Boise office at 420 West Main Street, Suite 305 and lists 208-387-0729 as its elder law contact number.Families do not necessarily need to know which planning strategy is appropriate before reaching out.They simply need to recognize when important questions deserve answers.Can a spouse remain financially secure?Could Medicaid eventually help?Should existing estate documents be updated?How should long-term care insurance fit into the plan?Are financial transfers being considered?Those questions are often easier to address before care becomes an emergency.To learn more and connect with the firm, visit the Ahrens DeAngeli Law Group profile on SeniorsBlueBook.com.Planning for long-term care does not mean assuming that nursing-home care is inevitable. It means giving yourself and your family a clearer understanding of the legal and financial options available if circumstances change.
Sep 23, 2026
Legal Planning Steps Boise Families Should Consider
Legal Planning Steps Boise Families Should ConsiderAn Alzheimers or dementia diagnosis can change the direction of an entire family.At first, the concerns may be mostly medical.What type of dementia is this?How quickly might it progress?Which treatments or services may help?But before long, other questions often emerge.Who will manage finances if Mom can no longer do so independently? Who has authority to make healthcare decisions? Can Dad remain at home? How will future memory care or nursing care be paid for? Are existing estate planning documents still appropriate?For families in Boise and Ada County, Idaho, addressing these legal and financial questions early can make future decisions easier to navigate.Ahrens DeAngeli Law Group has an elder law practice focused on Medicaid planning, elder-focused estate planning, veterans benefits planning, long-term care issues, and Alzheimers planning. The firms Boise elder law office is located at 420 West Main Street, Suite 305 in Boise.The goal of planning is not to predict every stage of dementia.It is to establish enough legal authority, financial preparation, and written guidance that families are not forced to solve everything during a crisis.Dementia Planning Is a Growing Concern for Idaho FamiliesAlzheimers disease and related dementias affect thousands of Idaho households.The Idaho Department of Health and Welfare currently reports that approximately 30,000 Idahoans have received an Alzheimers diagnosis, while about 74,000 Idahoans are providing care to someone with Alzheimers disease in 2026. The state also reports approximately $222 million in Medicaid costs associated with caring for people with Alzheimers in 2025.Those numbers show why dementia is not simply a medical issue.It can also become a:Family caregiving issueHousing issueFinancial issueLong-term care issueLegal decision-making issueA diagnosis may affect several parts of life at once.That is why legal planning should often begin alongside medical and caregiving planning rather than years later.Elder Law Tip: A dementia diagnosis does not automatically mean someone can no longer make legal decisions. Capacity can vary by person and circumstance. The important step is addressing planning early, while the individual can still participate meaningfully whenever possible.Start by Understanding What the Diagnosis MeansBefore making major legal or financial decisions, families should understand the medical situation as clearly as possible.Not every memory problem is Alzheimers disease.The Idaho Department of Health and Welfare notes that dementia is a broad term and that some causes of cognitive decline may be reversible or treatable. The agency encourages medical evaluation when symptoms such as memory loss, difficulty completing familiar tasks, confusion, planning problems, or other significant cognitive changes appear.For families, this means legal planning and medical evaluation should often happen in parallel.A medical diagnosis can help clarify:Whether cognitive decline is temporary or progressiveWhat support may be neededHow quickly circumstances may changeWhether long-term care planning should become more urgentAhrens DeAngelis Alzheimers planning materials similarly encourage families to obtain medical evaluation while also addressing legal and financial planning early.Review Financial Power of AttorneyOne of the most important questions after a dementia diagnosis is:Who can legally manage financial matters if the person eventually cannot?A financial power of attorney can authorize another trusted person to handle certain financial or business matters on the individuals behalf.Depending on how the document is written and the circumstances, that may involve tasks such as:Paying billsManaging bank accountsHandling property mattersCommunicating with financial institutionsManaging insurance-related issuesApplying for benefitsHandling tax or business mattersAhrens DeAngeli identifies financial powers of attorney as one of the important early planning tools for families dealing with Alzheimers or dementia.Simply being someones spouse, son, or daughter does not necessarily provide unlimited authority over every financial account or transaction.Having the appropriate legal documentation in place can reduce confusion later.Review Healthcare Decision-Making DocumentsFinancial authority is only one side of the planning process.Families also need to understand who can make healthcare decisions if the person with dementia eventually cannot make or communicate those decisions independently.Ahrens DeAngelis dementia-planning materials emphasize healthcare powers of attorney and treatment directives as important parts of early legal planning.These documents may help identify:Who should make medical decisionsWho can communicate with healthcare providersWhat the persons treatment preferences areWho should be involved if serious healthcare decisions ariseThe exact documents and language appropriate for one person may not be right for another.That is why families should review existing documents rather than assuming an old form still meets current needs.Capacity Makes Timing ImportantDementia often progresses over time.A person may still be able to understand and make certain decisions during early stages of the disease.Later, that ability may become limited.Ahrens DeAngeli emphasizes that legal planning becomes more difficult when the person no longer has sufficient legal capacity to understand and execute needed documents.That does not mean every family must immediately rewrite every legal document after a diagnosis.It means the diagnosis is a reason to review what already exists and determine whether important gaps remain.Waiting until a family urgently needs access to accounts, authority to sign documents, or permission to arrange care can create unnecessary complications.Review the Existing Will and TrustA dementia diagnosis is also an appropriate time to review estate planning documents.A will or trust created many years earlier may still reflect the persons wishes.Or it may no longer fit.Circumstances may have changed because:A spouse diedA family member became a caregiverAssets changedProperty was soldNew grandchildren were bornA beneficiary developed special needsLong-term care expenses became a concernAhrens DeAngeli recommends reviewing wills and trusts after major life events and specifically identifies memory loss or an Alzheimers diagnosis as an important reason to revisit existing plans.The purpose is not automatically to make changes.It is to confirm that the plan still accomplishes what the older adult intends.Look at How Property Is TitledProperty ownership can affect both estate administration and long-term care planning.Homes, bank accounts, investments, and other assets may be held:IndividuallyJointlyIn a trustWith beneficiary designationsThrough another ownership arrangementAhrens DeAngelis Alzheimers planning guidance specifically identifies property-title review as an important part of planning after cognitive decline is identified.Families should avoid changing ownership casually.Moving a house, account, or investment into someone elses name can have legal, tax, estate planning, and Medicaid consequences.What worked for a neighbor or relative may not be appropriate for another family.Begin Long-Term Care Planning EarlyDementia-related care needs often increase gradually.At first, a person may need only reminders.Later, support may include:TransportationMeal preparationMedication supervisionPersonal careHome careAdult day servicesIncreased supervisionAssisted livingMemory careSkilled nursing careAhrens DeAngelis Alzheimers practice specifically focuses on planning and paying for long-term dementia care, including how legal and financial resources may need to change as care needs progress.Planning early gives families time to consider:Available savingsRetirement incomeLong-term care insuranceVeterans benefitsMedicaidPropertyFamily caregiving capacityPreferred care settingsThe right plan will depend on the persons finances, health, marital status, and goals.Understand Medicaid Before Moving AssetsMedicaid may become relevant when someone eventually needs substantial long-term care.However, Medicaid eligibility involves detailed rules.Ahrens DeAngeli distinguishes between Medicaid pre-planning, when someone is planning in advance, and Medicaid crisis planning, when long-term care is already needed or expected soon.Families should be particularly cautious about transferring assets based on informal advice.Statements such as:Just give the house to the children.Move all the money out of Dads name.Spend everything before applying.may oversimplify a complicated legal situation.Ahrens DeAngeli specifically warns that gifts or property transfers can affect benefit eligibility and should be reviewed carefully before action is taken.Medicaid rules can change, so current individualized advice matters.Think About the Spouse Who Is Still IndependentDementia planning should not focus only on the person who has been diagnosed.If that person is married, the financial stability of the other spouse also matters.One spouse may eventually need expensive long-term care while the other still needs resources for:HousingFoodUtilitiesTransportationHealthcareInsuranceTheir own future careMedicaid rules contain specific protections and requirements for married couples when one spouse requires long-term care.Those rules are technical, and individual circumstances matter.Families should avoid assuming that all marital assets must automatically be exhausted before assistance becomes possible.Review Long-Term Care Insurance EarlyIf the older adult owns long-term care insurance, locate the policy before care needs become urgent.Families should understand:What services are coveredHow benefits are triggeredWhether cognitive impairment can qualifyWhether home care is coveredWhether assisted living or memory care is coveredWhether there is an elimination periodHow long benefits may lastRecent Seniors Blue Book resources involving Ahrens DeAngeli note that some long-term care insurance policies use severe cognitive impairment as a qualifying condition, but the actual definition and requirements depend on the specific contract.Insurance should be considered alongside broader legal and financial planning rather than as a complete solution by itself.Veterans Benefits May Also Be RelevantMilitary service can be easy to overlook during dementia planning.Ahrens DeAngeli includes veterans benefits planning among its core elder law services.Families may want to gather information about:The older adults military serviceA deceased spouses military serviceExisting VA benefitsDischarge documentationEligibility depends on the specific program and the individuals circumstances.Veterans benefits may be one component of a larger long-term care plan alongside insurance, private resources, and Medicaid.Build a Caregiving Plan, Not Just a Legal PlanDocuments alone do not solve everyday caregiving challenges.Idaho currently reports approximately 74,000 people providing care to someone with Alzheimers disease, illustrating how heavily dementia care depends on families.Families should discuss practical questions such as:Who can help with appointments?Who will manage bills?Who can provide transportation?Who will communicate with healthcare providers?Who will manage insurance paperwork?What happens if the primary caregiver becomes ill?At what point might professional home care be needed?When should memory care be considered?Idaho Health and Welfare also notes that caregiver support is an important part of dementia care and points families toward Area Agencies on Aging, training, support groups, and other caregiver resources.A plan that depends entirely on one spouse or one adult child can become vulnerable over time.What If Legal Planning Was Not Completed Early?Not every family gets the opportunity to plan soon after diagnosis.Sometimes significant cognitive impairment is already present before anyone realizes legal documents are missing.In those circumstances, families may need to explore other legal options.Ahrens DeAngelis Seniors Blue Book profile lists guardianship and conservatorship matters among the firms elder law services.Guardianship and conservatorship are formal legal processes and should not be confused with routine family caregiving.Whether either process is necessary depends on the facts of the individual situation.Early planning may help some families avoid court involvement, but that is not always possible.What to Bring to an Elder Law ConsultationFamilies can make an elder law meeting more productive by gathering information ahead of time.Useful items may include:Current willTrust documentsFinancial power of attorneyHealthcare directiveProperty deedsBank statementsInvestment statementsRetirement-account informationLong-term care insuranceVeterans-related documentsList of current care needsInformation about major assets and debtsNames of important family members or caregiversThe firms planning materials specifically ask clients to bring current financial statements, estate planning documents, and real property information when preparing for a consultation.Do not postpone a conversation simply because every document cannot be located immediately.The consultation itself can help identify what information still needs to be gathered.Frequently Asked Questions About Dementia and Elder Law in BoiseWhen should legal planning begin after a dementia diagnosis?As early as reasonably possible. A diagnosis does not automatically mean the individual lacks legal capacity. Planning earlier may allow the person to participate more fully in decisions about finances, healthcare, estate planning, and long-term care.What legal documents may be important?Depending on the person's circumstances, important documents may include a financial power of attorney, healthcare power of attorney or advance directive, will, trust, and other estate or long-term care planning documents. Ahrens DeAngeli specifically emphasizes financial and healthcare powers of attorney in its Alzheimer's planning resources.Can Ahrens DeAngeli Law Group help with Medicaid planning?Yes. Medicaid planning is one of the firm's stated elder law practice areas, including both advance planning and crisis situations involving long-term care.Does the firm help with Alzheimer's and dementia planning?Yes. Alzheimer's planning is identified as one of Ahrens DeAngeli Law Group's core elder law practice areas. The firm's published resources discuss legal authority, estate planning, property ownership, Medicaid, and long-term care concerns that may arise after diagnosis.Where is Ahrens DeAngeli Law Group located in Boise?The elder law office is located at 420 West Main Street, Suite 305, Boise, Idaho 83702. The firm lists 208-387-0729 as its elder law phone number.Create a Legal Plan While Your Loved One Can Still Have a VoiceA dementia diagnosis can create uncertainty about what comes next.But not every decision has to be made immediately.Start with the areas where early action matters most.Confirm who has authority to manage finances.Review healthcare directives.Look at wills and trusts.Understand property ownership.Locate insurance policies.Learn about long-term care options.Explore Medicaid and veterans benefits before making major financial transfers.And most importantly, include the person living with dementia in those conversations for as long as they are able to participate.For families in Boise and Ada County, Ahrens DeAngeli Law Group focuses on elder law issues including Alzheimers planning, Medicaid planning, elder-focused estate planning, veterans benefits, guardianship and conservatorship matters, long-term care planning, and related financial concerns.Idaho currently reports approximately 30,000 residents diagnosed with Alzheimers disease and 74,000 people providing Alzheimers care, reinforcing how many families are facing these questions across the state.To learn more about local elder law resources, connect with Ahrens DeAngeli Law Group through its SeniorsBlueBook.com business profile.A dementia diagnosis may change the future, but early planning can help ensure that important decisions are guided by the older adult's wishes rather than by the urgency of a crisis.
Sep 23, 2026
Getting Help Paying for Long Term Care
Getting Help Paying for Long Term CareLast month a woman came into our office and told us that her husband, who was paying thousands of dollars a month for long term care, had been denied for Medicaid because the couples life savings (that they held in an annuity) was too much and they would have to cash the annuity out and spend most of the money before Medicaid would help, leaving little for the wife to live on. We explained that was not necessarily true, and we contacted the annuity company to make some important changes to the annuity. Her husband was approved for Medicaid within a few weeks, even the couple still had the same amount of savings. Many families find it difficult or impossible to pay the high monthly cost of long term care. It can be especially difficult when one spouse needs long term care but the couple is hesitant to spend all the life savings on that spouses care when the healthier spouse may have many years of life left. However, it is possible to get help paying for care without becoming impoverished; but it is crucial to know how to qualify and use that help to your advantage. For veterans and their spouses there is a program often called Aid and Attendance that helps veterans, and their spouses pay for long term care. Currently, a married veteran paying for nursing home care may qualify for up to $2,642.83 per month from the VA to help pay for that care. To qualify, in most situations a veteran needs to have served only 90 days of active duty, one day of which was during a period of war and cannot have had a dishonorable discharge. A veteran does not need to have a service-connected disability to qualify.There are rules about assets and income to qualify for a VA Aid and Attendance pension. Often, veterans are told they dont qualify when they make an initial inquiry to the VA. However, before giving up, it is important that a family consult a VA accredited elder law attorney to check whether there is anything the veteran can do to change the financial situation and become eligible for the pension. A good advisor may be able to help the family make changes to become eligible.Medicaid also has a program to help seniors pay for long term care. Like the VA pension above, Medicaid has strict rules about assets and income. However, Medicaid also has rules that can be used to the advantage of the person needing long term care. Even if you have think your loved one does not qualify for any help, you must consult with an elder law attorney to see if anything can be done to help your loved one before they become impoverished. In the story above, we used the Medicaid rules to help the womans husband qualify before the money was gone.There are many myths and misconceptions about long term care and how to pay for it. There are resources available to help pay for care, but you must plan appropriately to make sure that you can get the help you need. However, even if you havent planned ahead, dont give up just because a friend or even a professional tells you cannot get any help. People often get bad advice in this area; find an elder law attorney near you that can help you protect yourself and your loved ones.David J. Wilson, J.D., L.L.M., CELABoard Certified Elder Law Attorney, VA AccreditedJoshua C. P. Reams, B.A., J.D., NAELA Elder Law Attorney, VA Accredited
Jan 04, 2024
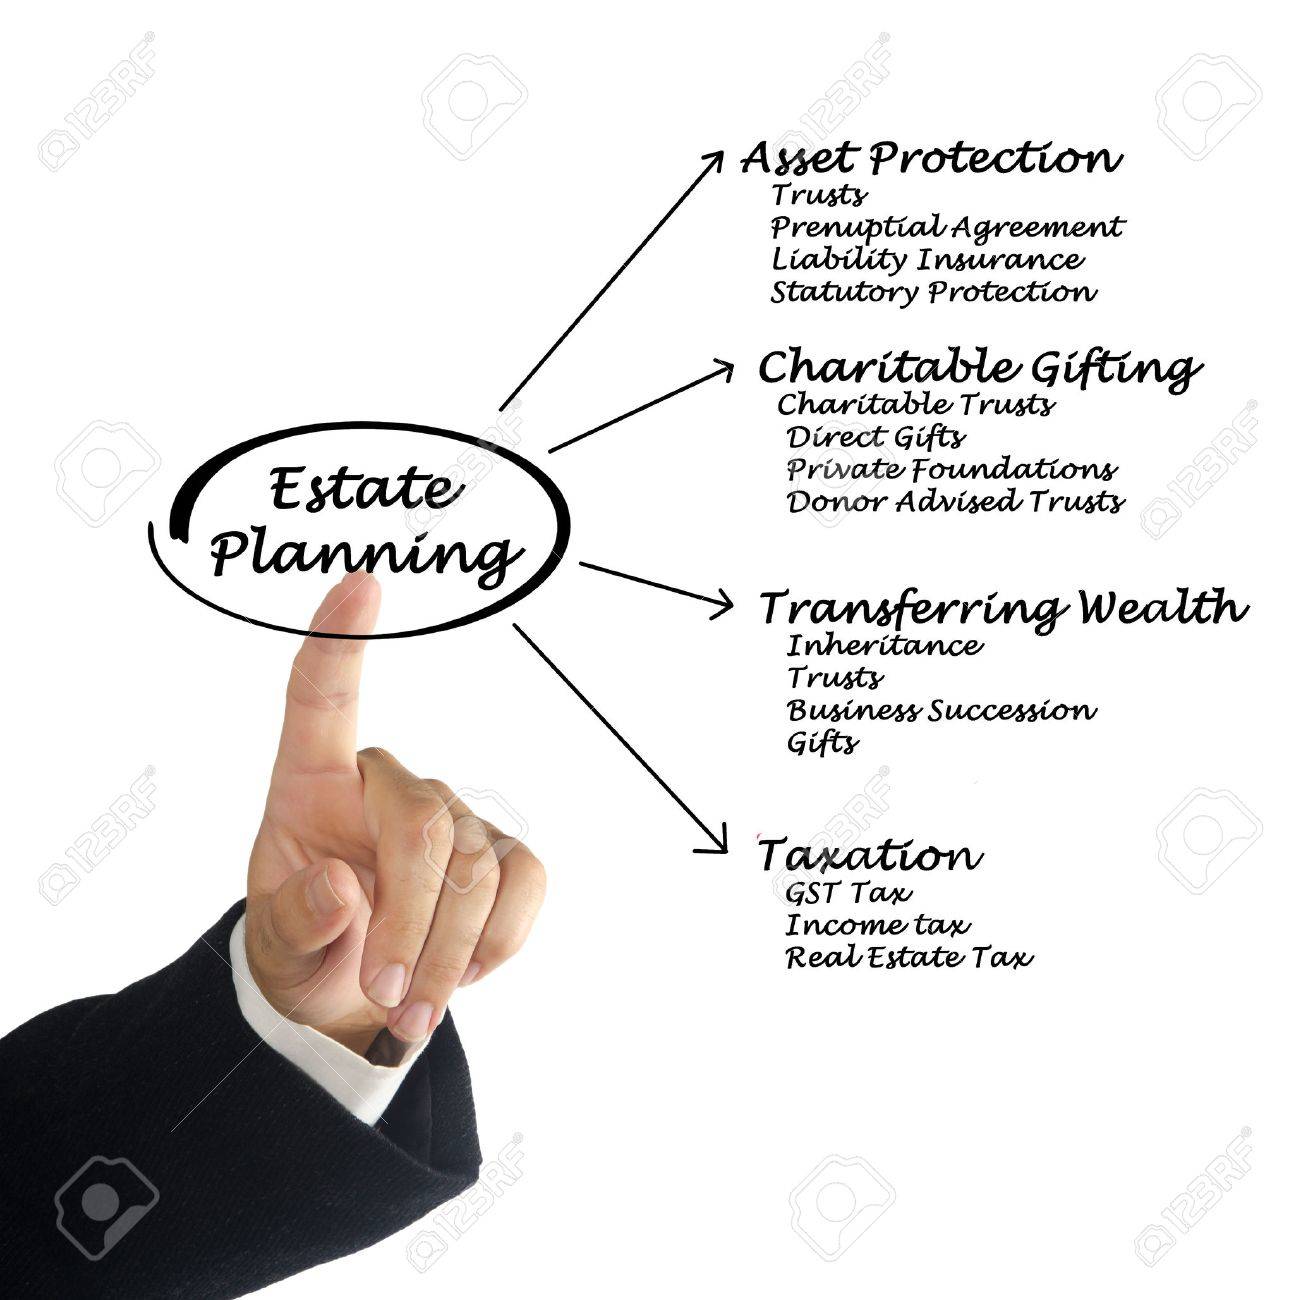
Estate Planning: More Than a Will , Protect Your Family, Your Assets
Estate Planning: More Than a Will Protecting Your Family, Your Assets and Your WishesEstate planning is often something people put off because they assume it is only necessary for wealthy families or people in poor health. In reality, estate planning is an important part of preparing for the future at almost every stage of life. A thoughtful plan can help determine who receives your assets, who can make decisions for you if you become unable to do so, how your family is protected, and how your wishes are carried out.For seniors and their families, estate planning can become especially important as circumstances change. Retirement, changing health needs, blended families, business interests, charitable goals, long-term care concerns and the desire to leave a meaningful legacy can all affect the type of plan that makes sense.The attorneys at Ahrens DeAngeli Law Group LLP emphasize that effective wealth planning is about more than simply transferring assets. Their approach includes looking at the bigger picturefamily goals, financial management, education, philanthropy, business succession and values that can continue from one generation to the next. What Is Estate Planning?Estate planning is the process of creating a legal and financial strategy for managing your affairs during your lifetime and distributing your assets after your death.A comprehensive estate plan may address: Your will and other estate documents Trusts Beneficiary designations Financial powers of attorney Healthcare decision-making Guardianship and conservatorship considerations Real estate and other property Retirement accounts and life insurance Business interests Tax planning Charitable giving Protection and preservation of family wealth Long-term care and elder law considerations The right plan depends on an individual's family, assets, goals and circumstances. There is no single estate-planning strategy that works for everyone.A Will Is Importantbut It May Not Be EnoughMany people believe that having a will means their estate plan is complete. A will is certainly an important document, but estate planning can involve much more.A will generally explains how certain assets should be distributed after death and can name individuals to serve in important roles, such as an executor. However, assets such as retirement accounts, life insurance policies and certain jointly owned property may pass according to beneficiary designations or ownership arrangements rather than simply following the instructions in a will.This is why coordinating the different pieces of an estate plan is so important.An estate planning attorney can help review how assets are titled, who is named as a beneficiary and whether the overall plan works together as intended.Trusts Can Provide Greater FlexibilityTrusts can be valuable tools in estate and wealth planning. Depending on the type of trust and the individual's objectives, a trust may help manage assets during someone's lifetime and determine how those assets are handled for beneficiaries.Trust planning can become particularly valuable when a family has: Significant assets Children or grandchildren who may need ongoing financial management A blended family A family business Real estate in multiple locations Special family circumstances Charitable goals Concerns about preserving wealth across generations Ahrens DeAngeli Law Group notes its experience with sophisticated wealth-planning strategies, including dynasty trusts designed to address goals that extend beyond simply transferring wealth from one generation to another. The firm's philosophy emphasizes thoughtful discussions involving clients, family members and trusted professional advisors. Estate Planning Can Also Protect You While You Are LivingOne of the biggest misconceptions about estate planning is that it only matters after someone dies.A good plan can also address what happens if you become unable to manage your own financial or healthcare affairs.Documents such as powers of attorney can allow a person you trust to make certain decisions on your behalf if you become incapacitated. Without appropriate planning, families may face court proceedings involving guardianship or conservatorship.These situations can be complicated, particularly when there are disagreements among family members or significant financial assets involved. Ahrens DeAngeli Law Group identifies complex guardianship and conservatorship matters as one of its practice areas and notes the importance of protecting the rights of individuals involved in these proceedings. Estate Planning and AgingAs people grow older, estate planning frequently overlaps with elder law and long-term care planning.Families may eventually need to consider questions such as: What happens if a parent needs assisted living or nursing-home care? How will long-term care be paid for? What assets need to be protected? Who will manage financial affairs? What happens if someone develops dementia or Alzheimer's disease? Are veterans benefits available? How can a family prepare for future healthcare needs? Will an existing estate plan still accomplish the family's goals? These are not questions that should necessarily be addressed at the last minute.Ahrens DeAngeli Law Group's elder law practice specifically includes Medicaid planning, elder-focused estate planning, veterans benefits planning and Alzheimer's planning, reflecting the connection between estate planning and the legal and financial issues that can arise later in life. Don't Forget About TaxesTax planning can be another important component of an estate plan.Depending on the size and structure of an estate, there may be federal, state, income, gift or other tax considerations. Retirement accounts and trusts can also create complicated tax issues.Estate planning attorneys with tax expertise can work with a family's financial and tax advisors to coordinate strategies.For families with substantial assets, this can become particularly important. Ahrens DeAngeli Law Group describes tax planning as a key component of its wealth-planning strategies and highlights experience with estate, gift and generation-skipping transfer tax matters. Your Estate Plan Should Reflect Your ValuesEstate planning isn't only about dividing up money.For many families, the bigger question is:"What do I want to leave behind?"That might mean providing educational opportunities for grandchildren, helping children purchase a first home, maintaining a family business, supporting a favorite nonprofit or establishing a charitable legacy.It can also mean passing along family values and teaching future generations how to responsibly manage the assets they inherit.Ahrens DeAngeli Law Group describes wealth planning as an opportunity to instill values and skills in future generations, including education, financial and business management, philanthropy, volunteerism and social responsibility. That broader perspective can make estate planning much more meaningful than simply deciding who gets what.When Should You Review Your Estate Plan?Creating an estate plan is only the beginning. Your plan should evolve as your life changes.Consider reviewing your estate plan after major life events such as: Marriage or divorce Birth or adoption of a child Death of a beneficiary or person named in your plan Significant inheritance Sale or purchase of a business Major change in financial circumstances Moving to another state Changes in tax laws Changes in family relationships Diagnosis of a condition that may affect future decision-making A move into retirement Significant changes in charitable goals Even if nothing major has changed, periodically reviewing beneficiary designations and important documents can help ensure they still reflect your wishes.Estate Planning Is a Conversation, Not Just a Stack of DocumentsPerhaps the most important part of estate planning is starting the conversation.Talk with your spouse or partner. Talk with your children when appropriate. Identify the people you trust to make important decisions. Gather information about your assets and liabilities. Consider what matters most to you and what you want your family to understand.Then work with qualified professionals to turn those goals into an appropriate legal and financial plan.Estate planning can involve attorneys, accountants, financial advisors, insurance professionals and other trusted advisors. A coordinated approach can help ensure that the different pieces of a family's financial life work together.Planning Today Can Bring Greater Peace of Mind TomorrowNo one knows exactly what the future will bring. But families can prepare for many of the possibilities.Estate planning is ultimately about control, protection and peace of mind. It gives you an opportunity to make decisions while you can, rather than leaving difficult choices to your family during an already stressful time.Whether your estate is modest or substantial, whether you're newly retired or helping an aging parent, thoughtful planning can help protect the people and causes that matter most to you. For Idaho families looking for guidance on estate planning, wealth preservation, elder law, trusts and estates, or related planning matters, Ahrens DeAngeli Law Group LLP's website provides information about its Boise, Meridian and Ketchum offices and its estate, wealth-planning and elder-law practices.