Beneficent: Learn How to Pay For Long-Term Care
Counties Served: Colorado - El Paso County,Teller County | Colorado - Alamosa,Archuleta,Bent,Chaffee,Crowley,Custer,Fremont,Huerfano,La Plata,Las Animas,Otero,Pueblo
Medicaid Planning




About Beneficent: Learn How to Pay For Long-Term Care
Learn How to Pay for Long-term Care Costs for Colorado Middle-class Seniors & Disabled Adults
Who Beneficent Helps
Beneficent helps middle-class seniors and adults with disabilities understand how to pay for long-term care.
The Problem
Long-term care is expensive, and programs like Medicaid and Veterans Aid & Attendance are complicated and hard to navigate and receive approval.
How Beneficent Helps
Beneficent guides seniors, adults with disabilities, and their families through their options to pay for long-term care and manages the Medicaid or Veterans Aid & Attendance application process to ensure it is completed accurately.
The Outcome
- Seniors, adults with disabilities, and their loved ones gain peace of mind knowing quality care is covered, and their savings and assets are protected.
- Beneficent has helped over 3,000 families across Colorado
- Over 200+ five-star reviews from happy clients on the BBB and Google
Why Beneficent Is Different - A Mission Built on Empathy, Integrity & Financial Wellness
- At Beneficent, we are a team committed to seniors and disabled adults in times of uncertainty. Our core values center on compassion, respect, and helping clients protect what theyve worked so hard to build.
- A blend of professional guidance and personalized attention tailored to your situation
Careful support to provide clarity every step of the way.
Beneficent 4 Step Process:
1. Schedule Your Free Consultation - 719.645.8350
- We'll discuss your care needs and review your family's financial situation to determine how we can help preserve assets.
2. Develop Your Asset Protection Plan
- After assessing your circumstances, we'll create a customized strategy showing exactly how to qualify for government benefits while protecting maximum family wealth.
3. Present Your Options
- We'll explain all available programs and asset preservation strategies, so you can choose the approach that works best for your loved one.
4. Complete Your Applications
- Once you select your preferred option, we handle all paperwork and government communications to ensure successful approval.
Frequently Asked Questions (FAQ)
Q: What kinds of care does Beneficent help with?
A: Beneficent can assist in funding or placing seniors into home care, assisted living, memory care, or skilled nursing depending on needs and eligibility.
Q: Is there a cost for the initial consultation?
A: No. The first consultation is free and helps you explore options without obligation.
Q: Can Beneficent work with Medicaid or Veterans Assistance benefits?
A: Yes. Beneficent guides clients through Medicaid eligibility, VA Aid & Attendance, asset protection, and related financial planning.
Q: What if Im worried about losing savings or my home?
A: Part of Beneficents mission is asset preservation. Their team helps structure applications in ways that aim to protect property and savings while gaining benefit eligibility.
Q: Does Beneficent only help short-term, or can they support ongoing care?
A: Beneficent offers ongoing support including redeterminations, paperwork updates, and long-term care planning so you dont have to navigate it alone.
Ready to Explore Your Options? Call 719.645.8350
If you or a loved one in Colorado is facing long-term care costs whether in-home, assisted living, memory care, or skilled nursing Beneficent can help you understand your funding options and make a plan that preserves stability and peace of mind.
See More
Videos
Continue Your Search! Explore More Local Options.
Start SearchingLet’s engage and get educated!
Browse through thousands of expert articles in over 100 different categories.
Browse NowArticles You May Like
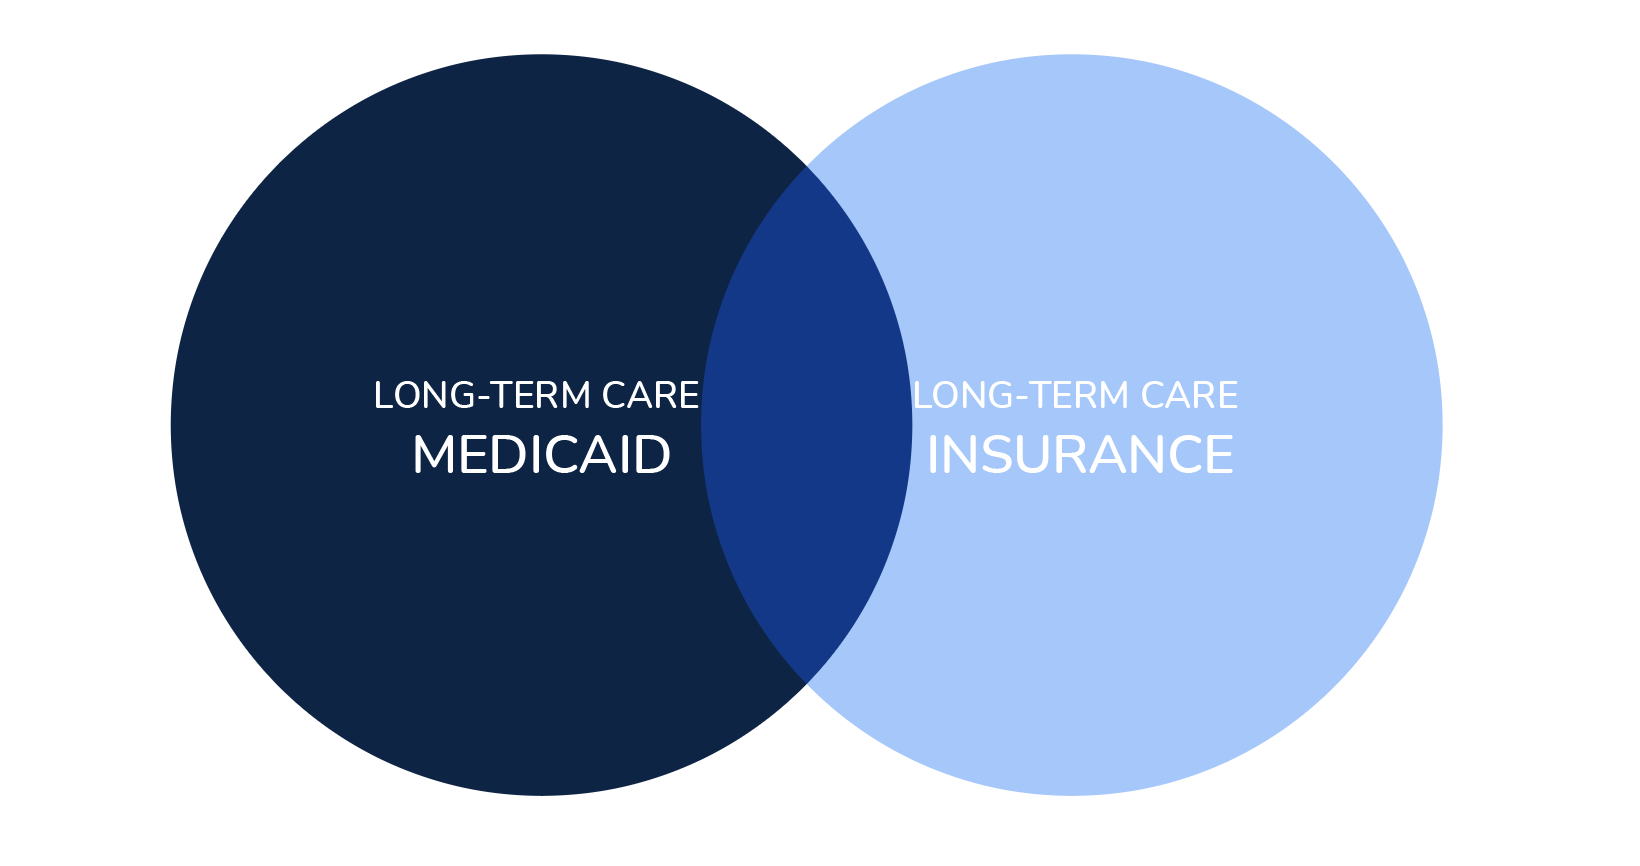
Long-term Care Medicaid vs Insurance: What's the Difference?
5 Minute ReadUnderstanding Long-Term Care Medicaid and InsuranceThe #1 cause for people filing for bankruptcy due to medical bills. A new study from academic researchers found that 66.5 percent of all bankruptcies were tied to medical issues. Therefore, the cost of long-term care is often a major concern for families. When it comes to managing the costs associated with long-term care, there are 2 primary options available to individuals and families.Long-term Care MedicaidLong-term Care Insurance Before deciding which option is the best fit, its important to understand the differences between these two types of coverage. Read on to learn more about understanding Long-term Care Medicaid and Insurance.Long-term Care MedicaidLong-term care Medicaid is a government program that provides medical and related services for people who meet certain income and resource requirements. This program is jointly funded by state and federal governments, so the details can vary from state to state. In general, eligibility requirements include being over 65 years old, blind or disabled and needing help with more than 2 of the activities of daily living. (Activities of daily living examples getting dressed, bathing, cooking, and more.) In some cases, individuals may be eligible for Long-term Care Medicaid even if their income and resources exceed the eligibility limits. Long-term Care InsuranceIn contrast to Long-term Care Medicaid, Long-term care insurance is an individual policy that you purchase from an insurance company. This type of coverage pays for custodial services such as assistance with activities of daily living like bathing and dressing as well as inpatient nursing home stays up to a predetermined amount per day. It can also cover other professional services like adult daycare programs or home health aides. Depending on your policy, you may also be eligible for additional benefits such as mental health treatment or respite services for family members who are providing care at home.Pros and ConsMany people find that they cannot afford the high premiums associated with Long-term Care Insurance, and Medicaid is a great option when it comes to paying for long-term costs. Preexisting conditions may also hinder an applicants ability to attain a Long-term Care Policy. With a lot of misinformation, many people also find it hard to determine if they are even eligible for Medicaid. Deciding which type of coverageLong-term Medicaid vs Insuranceis right for your situation can be difficult because of their complexities. Both options have their pros and cons but understanding them both can help guide you toward making an informed choice about how best to manage the costs associated with long-term care. Need to determine if you are eligible for Medicaid? Meet with Stacy Osborne, a Medicaid Certified Planner. In 1 hour, you will walk away with a Long-term Care plan in place at no charge. Stacy Osborne, MBA, CMP Beneficent CEO 719.645.8350
Apr 20, 2023
Top 5 Mistakes Families Make When Applying for Long-Term Care Medicaid in Colorado
When a loved one needs long-term care, emotions run highand so can the costs. Long-Term Care (LTC) Medicaid can be a critical lifeline, helping cover nursing home or in-home care expenses. But navigating the Medicaid application process in Colorado is far from simple, and mistakes can delay approval, trigger penalties, or cost families thousands.Here are the top five mistakes families make when applying for LTC Medicaidand how to avoid them.Mistake #1: Waiting Too Long to Start PlanningMany families only begin the Medicaid planning process once a health crisis hits. At that point, decisions are rushed, and options are limited. The truth is: Medicaid planning should start early, even years before care is needed.Planning ahead allows families to protect assets, avoid penalties, and qualify faster when the time comes. Even if your loved one is already in a facility or needs care now, there are often still legal and financial strategies availablebut the sooner you act, the better. Mistake #2: Gifting Assets Without Understanding the Look-Back PeriodIts common for people to think they can give money or property to family members to spend down assets and qualify for Medicaid. However, Medicaid has a 5-year look-back period in Colorado. This means that any gifts or asset transfers made within the past five years can lead to a penalty period during which Medicaid wont pay for care.Gifting without understanding this rule can unintentionally disqualify a loved one from coverage when they need it most. Always consult a Medicaid Certified Planner before transferring any assets. Mistake #3: Assuming All Assets Must Be Spent DownContrary to popular belief, not all assets need to be spent down to qualify for LTC Medicaid. Some assets are exempt, including: The primary residence (under certain conditions) One vehicle Personal belongings Certain types of burial arrangement Community Spouse Income Strategic planning can help preserve these assets while still achieving Medicaid eligibility. Mistake #4: Not Using a Qualified Medicaid PlannerThe Medicaid application process is technical and unforgiving. Submitting incorrect paperwork, missing documentation, or misunderstanding eligibility rules can result in a denial or delayA qualified Medicaid planner understands Colorados specific rules and can guide you through: Proper spend-down strategies Asset protection technique Gathering required documentation Communicating with Medicaid caseworkers Trying to go it alone can cost you far more in the long run. Mistake #5: Confusing Medicaid with MedicareMany families assume Medicare will cover long-term care. In reality, Medicare only pays for short-term rehabilitation (up to 100 days) after a hospital stayit does not cover custodial care in a nursing home or long-term in-home care.LTC Medicaid is the primary government program that helps cover these costs, but eligibility and benefits are very different from Medicare. Final ThoughtsApplying for Long-Term Care Medicaid in Colorado doesnt have to be overwhelming, but it does require the right guidance. Avoiding these five common mistakes can save you time, money, and unnecessary stress. Want more information? Call Beneficent Long-term Care Planning Medicaid Experts. 719.645.8350
May 07, 2025
How to Pay for Long-term Care Without Insurance
What to KNOW and What to DO NOWIt is estimated that 70% of all of us who reach age 65 will need some level of Long-Term Care. Here in Colorado the average cost for Long term care is $8758 per month according to 2020 state information. By nature, only about 15% of us are wired for advanced planning. So, this article is for the rest of us. Not planning in advance causes us to avoid the issue until we can no longer care for our loved one or worse yet, we become a caregiver who is injured in the process or worn to a frazzle by 24 hour caregiving. Often we avoid planning because we are afraid of learning that we may lose everything paying for care. Heres some practical things to know and do now so you can stop worrying about the cost of Long Term Care for yourselfor for ones you love.Things to Know:There are ways to get care paid for here in Colorado and still preserve hard-earned assets.Health First Colorado will pay for in home care, including paying a family member to provide care.They will pay for assisted living, full skilled care and adult day care.Meeting the qualifications for programs if you have assets can be tricky but, with education (and that can be free) you can quickly learn the rules that apply to your financial situation.The VA through Aid & Attendance will also help pay for costs if you served during wartime.Things to DO:Find someone who can give you accurate information. Google: VA & Medicaid Education Colorado and the BBB, www.bbb.org/southern-colorado . Read what others say about these companies. The BBB checks companies out thoroughly and the BBB has an AGE FRIENDLY designation if the company has been approved as trustworthy for the senior population.Find a firm that understands VA & Health First Colorado Programs. If the firm only knows one program, you wont get the full picture.Find a firm that can refer multiple attorneys since legal legal documents and advice may be needed.Find a firm who will give you information and options at no cost so you can decide what is best for you.Editors Note: This article was written by Stacy Osborne, MBA CMP with Beneficent. She can be reached by phone at 719-645-8350 or by email at: [email protected]
Apr 10, 2020

How to Apply for Long-Term Care Medicaid in Colorado
How to Apply for Long-Term Care Medicaid in ColoradoApplying for Medicaid can be a daunting task, especially when it comes to long-term care. However, with the right guidance and resources, the process can be much smoother. This guide is designed for seniors, caregivers, and Colorado residents to help them understand how to apply for long-term care Medicaid in Colorado. Understanding Long-Term Care MedicaidLong-term care Medicaid provides financial assistance to those who need help with daily living activities, such as bathing, dressing, and eating. It covers care provided in various settings including nursing homes, assisted living facilities, and even at home. Why You Shouldn't Apply AloneGiven the high volume of applications and the complexity of the process, we do not recommend submitting an application on your own. Mistakes can delay approval or result in denial. Should you choose to apply on your own, we will give you the information and tools you need during our free initial consultation with you. Schedule a free consultation here - calendly.com/doinggoodforothers Steps to Apply for Long-Term Care Medicaid in ColoradoStep 1: Find The Applicants DHS OfficeThe first step in applying for Medicaid in Colorado is to find the applicants local Department of Human Services (DHS) office. This is where you will submit your financial application. Find the Applicants DHS office here - cdhs.colorado.gov/contact-your-county Step 2: Submit a Financial ApplicationOnce you have located your local DHS office, you will need to submit a financial application. This form will require detailed information about your income, assets, and expenses. Step 3: Determine Financial EligibilityBefore proceeding with the application, it's crucial to determine if you qualify financially for Medicaid or VA Aid & Attendance benefits. Strategies exist to access benefits while protecting your personal assets, and a Certified Medicaid Planner (CMP) can help you maximize your benefits. Find out if you qualify - doinggoodforothers.com/financialinformation Step 4: Schedule a Health AssessmentAfter qualifying financially, you will need to schedule a level of care assessment, also known as a health assessment, with the Applicants Single Entry Point. This evaluation will determine the level of care you require. Schedule a health assessment - hcfp.colorado.gov/case-management-agency-directory Step 5: Skip the Hassle of Applying Alone Schedule an AppointmentIf you find the application process overwhelming, you can skip figuring out how to apply on your own by scheduling an appointment with our experts. Schedule an appointment with a Certified Medicaid Planner - calendly.com/doinggoodforothers Our 4-Step Process for Application AssuranceWe have developed a streamlined 4-step process to help you feel relief about your loved ones care and save money. 1. Schedule a Free Initial ConsultationLearn more about what we can do to preserve your assets by scheduling a free initial consultation. 2. Make a PlanThrough an assessment of your financial circumstances, we will create a roadmap of the best options for you. 3. Pick an OptionWe explore legitimate opportunities to preserve your assets. 4. Gain BenefitsSelect the best option, and we will complete a successful application for gained benefits. Applying for long-term care Medicaid in Colorado doesn't have to be stressful. By following these steps and seeking professional guidance, you can ensure a smoother application process and maximize your benefits.For personalized assistance, schedule a free consultation with one of our Certified Medicaid Planners (CMP) today. Learn more and schedule now! - calendly.com/doinggoodforothers
Jul 15, 2024
Smart Strategies to Protect Your Future
Smart Strategies to Protect Your FuturePlanning for long-term care is one of the most importantand often most overlookedfinancial decisions families face. In Colorado Springs, where the cost of care continues to rise alongside a growing senior population, understanding how to pay for long-term care is critical to protecting both your health and your financial future.For many families, the biggest concern isnt just where care will happenbut how it will be paid for. Without a clear plan, long-term care expenses can quickly deplete savings, impact retirement plans, and create stress for loved ones.Thats where education and guidance from experts like Beneficent come inhelping families navigate Medicaid planning and long-term care funding with clarity and confidence.The Reality of Long-Term Care CostsLong-term care includes a range of services such as: In-home care Assisted living Memory care Skilled nursing In Colorado Springs, these services can cost thousands of dollars per month. Many families are surprised to learn that: Medicare does not cover most long-term care services Out-of-pocket expenses can quickly escalate Without planning, savings can be exhausted faster than expected Understanding your options early can make a significant difference.Why Planning Ahead MattersThe earlier you begin planning for long-term care, the more options youll have.Planning ahead allows you to: Protect assets and savings Avoid unnecessary financial losses Ensure access to quality care Reduce stress for family members Waiting until care is urgently needed often limits choices and increases costs.Stacy Osborne explains: We help families understand their options so they can make informed decisions before theyre in a crisis. Planning ahead gives people more control over their future. This proactive approach is key to long-term financial security.Understanding Medicaid as a Payment OptionMedicaid is one of the primary programs that can help cover long-term care costsbut qualifying requires meeting specific financial criteria.Important factors include: Income and asset limits The five-year look-back period Rules around asset transfers Without proper planning, individuals may face penalties or delays in receiving benefits.Common Misconceptions About Paying for CareMany families have misconceptions that can lead to costly mistakes:I have to spend everything before qualifying for help.Not necessarilystrategic planning can help preserve certain assets.Medicare will cover long-term care.Medicare covers short-term medical needs, not ongoing custodial care.Its too late to plan once care is needed.Even in urgent situations, there may still be options available.Understanding these realities can help families avoid unnecessary financial strain.Exploring Funding OptionsThere are several ways to pay for long-term care, and most families use a combination of resources.Private PayUsing savings, retirement funds, or assets.Long-Term Care InsurancePolicies designed specifically to cover care costs.MedicaidAvailable for those who meet eligibility requirements.Veterans BenefitsCertain veterans may qualify for additional support.A personalized plan helps determine the best mix of these options.Protecting Assets While Securing CareOne of the biggest concerns families have is how to pay for care without losing everything theyve worked for.Strategic planning can help: Preserve a portion of assets Protect a spouse from financial hardship Ensure continuity of care Working with experts ensures that these strategies are implemented legally and effectively.The Role of Professional GuidanceLong-term care planning involves complex financial and legal considerations. Working with a knowledgeable advisor can help simplify the process.Benefits of professional guidance include: Clear explanations of options Customized financial strategies Assistance with applications and paperwork Ongoing support as needs change This expertise can save families time, money, and stress.Local Considerations in Colorado SpringsColorado Springs offers a wide range of care options, from in-home services to advanced care facilities. However, costs and availability can vary depending on location and level of care.Local expertise ensures that families: Understand regional costs Access appropriate care providers Navigate Colorado-specific Medicaid rules This localized approach leads to more effective planning.Taking the First StepStarting the conversation about long-term care may feel difficult, but its one of the most important steps you can take.Begin by: Discussing preferences with family members Reviewing financial resources Seeking professional advice These steps create a foundation for informed decision-making.A Plan for Peace of MindAt its core, long-term care planning is about peace of mind. It ensures that you or your loved one will receive the care needed without unnecessary financial hardship.With the right plan in place, families can focus on what truly mattershealth, comfort, and quality of life.Final ThoughtsPaying for long-term care doesnt have to be overwhelming. With the right knowledge and guidance, Colorado Springs families can navigate this process with confidence and clarity.Planning ahead provides more options, better outcomes, and greater financial security. Whether youre preparing for the future or facing an immediate need, taking action today can make all the difference. Visit Beneficents Seniors Blue Book listing to learn how their team can help you create a personalized plan for paying for long-term care.FAQs1. Does Medicare cover long-term care? No, Medicare only covers short-term medical care, not long-term custodial care.2. When should I start planning for long-term care? As early as possiblebefore care is needed.3. Can I qualify for Medicaid without losing all my assets? In many cases, yes, with proper planning.4. What is the Medicaid look-back period? A five-year review of financial transactions. 5. Should I work with a professional for planning? Yes, professional guidance helps avoid costly mistakes and ensures the best outcomes.
Apr 08, 2026
NEW Colorado Home Care Program: What You Need to Know
IntroductionStarting July 1, 2025, Colorado launched a new home care program through Medicaid called Community First Choice (CFC). This program is designed to help people who qualify for Long-term Care Medicaid stay safely in their own homes instead of moving into a nursing facility. Its one of the biggest changes to Colorados Medicaid long-term care system in years, and it may open new options for your family.At Beneficent, we know these programs can feel confusing. Below, well break down the essentials in plain language so you can decide whether this program might help your loved one.What Is the New Program?Community First Choice (CFC) is a new benefit under Health First Colorado (Medicaid). It gives people who need daily help access to in-home caregivers and supports. Think of it as a way to get the same kind of personal care someone might receive in a nursing home but delivered right at home.Who May Qualify?Your loved one may be eligible if they:Are already on Health First Colorado (Medicaid)Need help with everyday activities at the level a nursing facility would provide (for example, assistance with bathing, eating, mobility, or medication reminders)If your loved one is already on a Medicaid waiver, they can transition to this program during their annual review.What Services Can Families Expect?Families can expect support that makes day-to-day living easier and safer, such as:Personal Care help with bathing, dressing, using the restroom, eating, and moving around safelyHomemaker Services light cleaning, laundry, meal prep, and errands like grocery shoppingHealth-Related Support medication reminders, wound care, and teaching daily living skillsSafety Technology personal emergency response buttons, medication reminders, or home-delivered mealsTransition Assistance covering move-in costs if someone is moving out of a facility back into the communityHow Services Are DeliveredOne of the biggest benefits of this new program is choice:You can use an agency, which sends licensed caregivers to the home.Or, you can direct the care yourself hiring and managing your own caregiver (sometimes even a trusted family member).This flexibility gives families more control over who provides care and how its done.Why This Matters for FamiliesNo waitlists: Unlike many waiver programs, CFC is an entitlement. If your loved one qualifies, they can begin receiving services right away.More independence: This program is designed to help people remain at home, surrounded by family, rather than in a facility.Financial relief: Medicaid covers the costs, easing the financial burden on families who may otherwise struggle to afford care.How to Get StartedIf youre wondering whether your loved one may qualify, here are next steps:At Beneficent, we specialize in helping families understand programs like this, navigate the paperwork, and secure approval as quickly as possible. Schedule an initial consult here. doinggoodforothers.com/schedule-a-free-consultationFinal ThoughtsColorados new home care program (CFC) is a positive step for families offering more flexibility, quicker access to services, and the ability for loved ones to remain at home.If youre unsure whether your parent or loved one qualifies, reach out. Well walk you through eligibility, and help manage the application process from start to finish.
Sep 09, 2025

How Charlie and Fran Paid for Long-term Care without Insurance
Meet Charlie and Fran. They have lived on their family farm for 50+ years. To ensure their assets are safe for future generations, Charlie and Fran consulted with a Certified Medicaid Planner. Charlie and Fran have 3 children, 9 grandchildren, and 10 great-grandchildren. They have worked hard and have enjoyed 50+ years of life on their family farm. This place is important to their entire family. Knowing that over 70% of people over 65 will need some type of long-term care (LTC), Charlie and Fran needed guidance and accurate information to prepare for the uncertain future. Whether they suddenly needed LTC, or if LTC was years away, Charlie and Fran wanted to ensure future generations can enjoy the things they worked hard for their entire life including the farm.Colorado has many resources for financial help like Health First Colorado, and Colorados Medicaid Program. Medicaid helps with in-home care, assisted living, and nursing facility care. Most Colorado Seniors who need help paying for LTC feel they will not qualify for Medicaid because they have too much income or too many assets. In reality, many could qualify if they had the information from a knowledgeable professional, holding a Certified Medicaid Planner (CMP) designation. The role of a CMP is to assist, correct, and complete a Medicaid application. A CMP works with the Department of Human Services to gain approval for LTC Medicaid. Incomplete or inaccurate advice often causes Seniors to think that spend down is the only way to qualify for LTC Medicaid. This simply is not true and can lead to an unnecessary spend down and/or liquidation of the limited assets Seniors have worked a lifetime to obtain.There are legitimate means of preserving valuable or sentimental assets and income. Here in Colorado, the Medicaid guidelines afford numerous opportunities to protect income and assets. Consulting with a CMP who specializes in LTC can help you, your family, or a loved one to file a successful application and qualify for LTC Medicaid.Editors Note: This article was submitted by Stacy Osborone, MBA, CMP . She is the CEO of Beneficent and may be reached at719-645-8350 or by email at; [email protected]
Apr 08, 2021
Does Medicare Pay for Skilled Nursing in Colorado?
Does Medicare Pay for Skilled Nursing in Colorado?When a loved one needs nursing home care, one of the first questions families ask is: Will Medicare cover it? The answer is: only for a short time and only under specific circumstances.Medicares Limits on Skilled NursingMedicare was never designed to pay for long-term care. It will cover skilled nursing care only for a limited period after a qualifying hospital stay up to 100 days and only if the care requires licensed medical professionals.That short coverage window can create a serious challenge. Because Medicare stops paying so quickly, many people are discharged before theyve had enough time to fully recover. Families often face a painful choice: pay thousands of dollars out of pocket, or bring their loved one home before theyre ready.What Happens When Medicare Runs Out?Once Medicare coverage ends, so does the financial assistance unless another program steps in. Thats where Colorado Long-Term Care Medicaid can make all the difference.What Medicaid Will Pay for in ColoradoColorados Medicaid program is very different from Medicare. While Medicare focuses on short-term medical needs, Medicaid is designed to cover long-term care for people who meet certain medical and financial requirements.If your loved one qualifies, Medicaid can cover: Nursing home care both skilled and custodial, for as long as its needed. Room and board at a Medicaid-approved facility. Medical services in the facility, including medications, therapy, and supplies. Assistance with daily activities like bathing, dressing, eating, and mobility. Specialized care for dementia or other chronic conditions. In other words, Medicaid can provide ongoing coverage for both the medical and personal care your loved one needs not just for a few weeks or months.Why Families Turn to MedicaidIn Colorado, the average cost of a nursing home can exceed $9,000 per month. Even a modest savings account can be drained in months without help. Medicaid offers a safety net, but the application process is complex with strict rules about income, assets, and medical necessity.At Beneficent, we help families: Understand the differences between Medicare and Medicaid. Determine eligibility before savings run out. Navigate the application process quickly and correctly. Protect family assets while securing the care a loved one needs. The Bottom Line Medicare is a short-term solution. Medicaid is the program that can keep your loved one in a safe, supportive environment for the long term. The key is planning early before the bills become overwhelming. Call us at 719.645.8350 to get guidance on Medicaid for nursing home care in Colorado.
Aug 11, 2025

What Long-Term Care Services Does Medicaid Cover in Colorado?
What Long-Term Care Services Does Medicaid Cover in Colorado? Navigating the complexities of long-term care can be overwhelming, especially for seniors and caregivers. If you're in Colorado and exploring options, Long-Term Care Medicaid offers essential support for seniors needing extended care services. Here's what it typically covers:Services Covered by Long-Term Care Medicaid: Nursing Home Care, Assisted Living, or Memory Care: Comprehensive medical and personal care for those in living communities. Home and Community-Based Services (HCBS): Assistance with daily tasks, such as bathing, dressing, and meal preparation, provided in the comfort of your home or community. Adult Day Care: Structured programs that offer supervision, social interaction, and activities for seniors needing daytime assistance. Real-Life Example:One of our clients, with $100,000 in cash, a home, 2 cars, and a monthly income of $4,000, successfully qualified for Long-Term Care Medicaid. With professional assistance, they were able to access these vital services without exhausting their resources.Colorado's Medicaid program is designed to ensure seniors receive the care they need while protecting their financial well-being. If you're considering applying for Long-Term Care Medicaid, dont hesitate to explore how you, too, can qualify. Take the questionnaire to see if you qualify! www.doinggoodforothers.com/questionnaire
Dec 05, 2024
The Top 5 Misconceptions about Long-term Care Medicaid Eligibility
What You Have HeardAsk yourself, was the info you heard from a Certified Medicaid Planner?Medicaid Misconception #1 - You can only have $2,000.FACTSSingle applicants have a resource limit of $2,000. (in 2024) A married applicant has a resource limit of about $150,000. (in 2024)Medicaid Misconception #2 - Your home will be taken from you if you are on Medicaid.FACTSAll applicants are allowed to have 1 home and 1 car. There are ways to avoid Medicaid estate recovery, an applicant can receive Medicaid and keep their home.Medicaid Misconception #3 - You make too much money.FACTS If you are over the income limit, Beneficent can provide the legal steps using the Medicaid code to bypass being over the income limit.Medicaid Misconception #4 - You must spend down to $2,000 to qualify for Medicaid.FACTSThis is an option, however not your only option. If you want to preserve the hard-earned assets you or your loved one has worked their entire life, you can!Medicaid Misconception #5 - Why doesnt everyone apply for Long-term Care Medicaid if the other outcome statements are true?FACTSMany are deceived by misinformation and preconceived notions. There's a game-changer you need to know about - Certified Medicaid Planners (CMP) - we know the rules and regulations.You can find all the CMPs in the United States here, (https://cmpboard.org/locate-a-cmp/) there arent too many of us! Need to schedule an appointment with one of our Certified Medicaid Planners at Beneficent? Book here (https://calendly.com/doinggoodforothers) or call our office (719.645.8350) for more appointment times.
Apr 03, 2024
Smart Medicaid Planning Strategies Every Family Should Know
Smart Medicaid Planning Strategies Every Family Should Know In Colorado Springs, planning for the future often includes thinking about retirement, healthcare, and maintaining independence. But one of the most overlookedand most importanttopics is how to pay for long-term care. Whether care is needed at home, in an assisted living community, or in a skilled nursing facility, the costs can quickly add up. Without a plan, families may find themselves facing difficult financial decisions during an already stressful time. Beneficent, led by Stacy Osborne, helps families understand their options and develop smart Medicaid planning strategies to make long-term care more accessible and affordable. The True Cost of Long-Term Care Many families are surprised to learn just how expensive long-term care can be. In Colorado Springs, costs vary depending on the level of care, but they can include: In-home care services Assisted living monthly fees Skilled nursing facility costs Specialized memory care These expenses can quickly deplete savings if not planned for properly. Unfortunately, a common misconception is that Medicare will cover these costs. In reality, Medicare only covers short-term medical carenot ongoing long-term care. Why Medicaid Planning Is Essential Medicaid is one of the primary programs that can help cover long-term care costs, but qualifying requires careful planning. Medicaid eligibility is based on: Income limits Asset thresholds Medical necessity Detailed documentation Without proper planning, individuals may: Spend down assets unnecessarily Face delays in approval Lose opportunities to protect their financial legacy Stacy Osborne explains: "Families often dont realize they have options. With the right planning, we can help them access the care they need while protecting what theyve worked so hard to build." Common Misconceptions About Medicaid Many people avoid exploring Medicaid because of common myths. Lets clear up a few: I have too many assets to qualify. With proper planning, certain assets can be protected while still meeting eligibility requirements. I need to spend everything before applying. There are legal strategies that can preserve assets while qualifying for benefits. Medicaid planning is only for low-income individuals. In reality, many middle-income families benefit from Medicaid planning. Understanding these facts can open the door to better financial decisions. When Should You Start Planning? The best time to plan for long-term care is before it becomes urgent. Early planning provides more flexibility and better outcomes. However, even if care is needed soon, its not too late to explore options. Situations where planning is especially important include: A recent diagnosis or decline in health Preparing for assisted living or nursing care Concerns about affording ongoing care Wanting to protect assets for a spouse or family Strategies to Help Cover Long-Term Care Costs Medicaid planning involves a variety of strategies tailored to each individuals situation. These may include: Asset Protection Planning Structuring finances to meet eligibility requirements while preserving assets. Spend-Down Planning Using funds strategically rather than depleting savings unnecessarily. Income Planning Ensuring income is allocated appropriately under Medicaid guidelines. Application Assistance Navigating paperwork and requirements accurately to avoid delays. Beneficent provides guidance through each of these steps, ensuring families understand their options and make informed decisions. The Importance of Local Expertise Medicaid rules can vary by state, making local expertise critical. In Colorado Springs, understanding state-specific regulations and available care options is essential for effective planning. Working with a local expert like Beneficent ensures: Up-to-date knowledge of Colorado Medicaid rules Familiarity with local care providers Personalized strategies based on regional realities This local insight can make a significant difference in the success of a plan. Reducing Stress for Families Financial concerns can add significant stress during an already emotional time. Medicaid planning helps reduce that burden by providing clarity and direction. Families benefit from: A clear understanding of their options Guidance through complex processes Confidence in their decisions Peace of mind knowing a plan is in place In a family-centered community like Colorado Springs, this support is invaluable. Protecting Your Legacy While Securing Care One of the biggest concerns families have is losing everything theyve worked for. Medicaid planning allows individuals to access necessary care while protecting their financial legacy whenever possible. This means: Preserving assets for a spouse Protecting savings for future generations Ensuring access to quality care With the right guidance, its possible to balance both care needs and financial goals. Take Control of Your Long-Term Care Plan Planning for long-term care doesnt have to be overwhelming. With expert guidance, families can take proactive steps to secure care and protect their future. If you or a loved one are exploring how to pay for long-term care in Colorado Springs, visit Beneficents listing on Seniors Blue Book to learn more and connect with a trusted local expert who can guide you every step of the way. FAQs Does Medicare cover long-term care? No, Medicare primarily covers short-term medical care, not ongoing long-term care. Can I qualify for Medicaid if I have assets? Yes, with proper planning, certain assets can be protected. How long does Medicaid planning take? It varies depending on the situation, but early planning provides more options. Is Medicaid planning legal? Yes, when done properly, it follows established legal guidelines. When should I start planning for long-term care? As early as possible, but its never too late to explore your options.
Apr 13, 2026
How Colorado Springs Families Can Prepare for Long-Term Care
How Colorado Springs Families Can Prepare for Long-Term CareIn Colorado Springs, where stunning mountain views meet a growing and vibrant senior population, more families are asking an important question: How will we pay for long-term care?Its a question that often comes too lateafter a health crisis, a sudden diagnosis, or a difficult hospital stay. But the truth is, planning ahead can make one of lifes most challenging transitions far more manageableboth emotionally and financially.Understanding how to pay for long-term care isnt just about numbers. Its about protecting your independence, your family, and the life youve worked hard to build.Why Long-Term Care Planning Matters More Than EverAs life expectancy increases, so does the likelihood of needing some form of long-term care. This can include: In-home care services Assisted living communities Skilled nursing facilities Memory care for dementia or Alzheimers In Colorado Springs, the cost of these services continues to rise, making planning essential for families who want to avoid financial strain.Many people assume Medicare will cover these expensesbut thats one of the most common misconceptions.Stacy Osborne of Beneficent explains, "Families are often surprised to learn that Medicare doesnt cover most long-term care. Without a plan, the financial burden can be overwhelming."Breaking Down the Costs of CareLong-term care costs vary depending on the type and level of care needed. In Colorado Springs, families may face: Thousands of dollars per month for assisted living Even higher costs for skilled nursing care Ongoing expenses for home health services Without preparation, these costs can quickly deplete savings and impact a familys financial future.Medicaid: A Critical ResourceBut Not a Simple OneMedicaid is one of the primary programs that helps cover long-term care costs. However, qualifying for Medicaid is not always straightforward.Eligibility is based on: Income limits Asset thresholds Medical necessity Many families believe they must spend down all their assets to qualifybut thats not always true.With proper planning, its often possible to: Protect certain assets Preserve income for a spouse Qualify for benefits without financial devastation "The key is understanding the rules before you need them," says Stacy Osborne. "There are strategies available, but timing is everything."Smart Strategies for Paying for Long-Term CarePlanning ahead opens the door to more options. Here are some of the most effective strategies families in Colorado Springs can consider:1. Medicaid PlanningWorking with an expert can help structure finances in a way that meets eligibility requirements while protecting assets.2. Long-Term Care InsuranceThese policies can help cover costs, though they are most effective when purchased earlier in life.3. Veterans BenefitsEligible veterans and their spouses may qualify for programs that help offset care expenses.4. Asset Protection PlanningLegal tools such as trusts may help safeguard assets for future generations.5. Private Pay PlanningUnderstanding how to strategically use savings can help extend financial resources.The Risks of Waiting Too LongOne of the biggest mistakes families make is delaying planning until care is urgently needed.Last-minute decisions can: Limit available options Lead to rushed financial choices Increase stress for everyone involved By contrast, early planning allows families to: Explore multiple solutions Make informed decisions Reduce emotional and financial pressure Why Local Expertise in Colorado Springs MattersEvery state has its own Medicaid rules, and Colorado is no exception. Working with a local expert ensures that your plan aligns with state-specific regulations.Beneficent specializes in helping Colorado Springs families navigate these complexities with clarity and confidence.Stacy Osborne shares, "Our goal is to guide families through a process that can feel overwhelming. With the right plan in place, you can focus on carenot financial stress."Planning for More Than Just FinancesWhile finances are a major component, long-term care planning also involves: Choosing the right type of care Communicating wishes with family members Preparing legal documents such as powers of attorney Ensuring continuity of care Taking a holistic approach ensures that every aspect of the future is considered.A Real-Life PerspectiveImagine a family in Colorado Springs facing a sudden health crisis. Without a plan, theyre forced to make quick decisionsoften choosing the most immediate option rather than the best one.Now imagine that same family with a plan already in place. They understand their options, have financial strategies ready, and can focus on supporting their loved one instead of worrying about costs.Thats the difference planning makes.Take Control of Your Future TodayLong-term care planning may feel overwhelming, but it doesnt have to be. With the right guidance, you can create a plan that protects your finances, supports your family, and ensures access to quality care. Visit Beneficent on Seniors Blue Book to learn how their team can help you prepare for the future with confidence and clarity.FAQsQ: Does Medicare cover long-term care? A: No, Medicare typically only covers short-term medical care, not long-term custodial care.Q: When should I start planning for long-term care? A: Ideally, planning should begin well before care is needed.Q: Can I qualify for Medicaid if I have savings? A: Yes, with proper planning, you may still qualify.Q: Are there options for immediate care needs? A: Yes, crisis planning strategies may still be available. Q: Do I need professional help for planning? A: Yes, working with an expert can help avoid costly mistakes.
Apr 10, 2026

What to Know About Long-term Care Medicaid
5 Minute ReadDo you or someone you love need long-term care? If so, understanding the basics of Long-term Care Medicaid can be an invaluable resource. Long-term Care Medicaid helps Seniors and Disabled Adults pay for the high costs of ongoing medical and personal care services. In this blog post, Stacy Osborne, CEO of Beneficent, will discuss what Long-term Care Medicaid is and how it can help those in need of ongoing medical and personal support. What is Long-term Care Medicaid? Since April 1999, Beneficent has been privileged to successfully assist more than 3000 families and individuals through the long-term care Medicaid and VA applications while preserving assets.Long-term Care Medicaid is a financial assistance program that helps pay for medically necessary long-term care services. This includes nursing home care, home health services, assisted living facility services, adult day health services, hospice care, respite care, and more. It is available to people who are aged 65 or older; blind; disabled (as defined by the Social Security Administration); or medically needy (those who have high medical expenses which exceed their income). Eligibility for Long-term Care Medicaid in ColoradoIn order to qualify for coverage through a states Long-term Care Medicaid program, individuals must meet certain criteria regarding their residence status and citizenship/immigration status as well as a financial assessment. The financial assessment looks at things like income level and assets owned by the applicant. Since April 1999, Beneficent has been privileged to successfully assist more than 3000 families and individuals through the long-term care Medicaid and VA applications while preserving assets.Benefits of Applying for Long-term Care Medicaid Though it can take some time to navigate through all of the paperwork involved in applying for coverage under one of these programsit could end up saving money in the long run while providing much needed relief when it comes to accessing necessary healthcare services. Applying for Long-term Care Medicaid can provide numerous benefits to those needing long-term care assistance. Not only can it help cover the cost of needed medical aid such as nursing home stays or home health aides; it could also cover the cost of personal aids such as assistive devices like wheelchairs or walkers; transportation assistance; meal delivery programs; homemaking and chore services; adult daycare centers; medication management programs; personal emergency response systems; occupational therapy; physical therapy among other things that many seniors need assistance with on a daily basis. Overall, applying for Long-term Care Medicaid can be an invaluable resource if you or someone you love needs ongoing medical or personal support due to age, disability or any other qualifying factor that might make them eligible for coverage under a states specific program guidelines. Though it can take some time to navigate through all of the paperwork involved in applying for coverage under one of these programsit could end up saving money in the long run while providing much needed relief when it comes to accessing necessary healthcare services. Ultimately this could lead to better quality of life down the roadmaking it worth every step taken along the way!Skip the headache of trying to apply for Long-term Care Medicaid on your own and call 719.645.8350 Beneficent to schedule a FREE initial consultation. We work with residents across the state of Colorado. Stacy OsborneBeneficent CEO719.645.8350
Feb 05, 2023

Thank Goodness for Beneficent - Long-term Care Planners!
THANK GOODNESS FOR BENEFICENT!!!Client Testimonial by Cindy Powell5 Minute ReadI am the court-appointed legal guardian and conservator for my mother, who has dementia. What an extreme blessing it was, to meet a (expert Certified Medicaid Planning Agency) Beneficent representative at a Halloween event at Fountain Valley Senior Center in October 2021. I worked in Adult Assistance Payments at El Paso County DHS in the past, and I only knew about spend down. When I mentioned that I was working toward spending down Moms resources to $2000. (Which included cashing in on Moms life insurance policies, spending the cash surrender values toward Moms memory care), The Beneficent representative stated absolutely not, Mom could qualify for Long-term Care Medicaid without spending down, and Beneficent could instruct and assist me in applying for Long-term Care Medicaid on Moms behalf. At the Halloween event, I took Beneficents business card, made an appointment, and it was the very best thing I ever could have done for Mom, as her conservator. The resources that were preserved will definitely be helpful to pay legal fees to file Moms annual guardian and conservator reports, and an accountant to prepare and file her annual income tax returns. Long-term Care Medicaid recipients receive under $200/mo. personal care allowance. Being retired on a limited Social Security income, I certainly couldnt afford those legal and accountant expenditures.Another significant thing to mention is Moms combined incomes exceed income limits for Long-term Care Medicaid, yet, is insufficient to pay Moms memory care room and board. Without Beneficents expert guidance, I would have known nothing about Medicaid income trust accounts and might have been forced to bring Mom home after spending down all of her resources. I certainly couldnt have safely provided care for Mom and could have prematurely died from the stress. Beneficents fee is a flat fee, there isnt nickel and diming all along the way. The fee we paid was worth every penny, as the fee was a small percentage in comparison to the resources preserved. Had I not enlisted Beneficent to apply for Long-term Care Medicaid on my mothers behalf, Mom would have been destitute, with only $2000 maximum in remaining resources. I am extremely grateful to my Beneficent Case Manager for keeping me informed every step of the way throughout the application process. Even after my mother was approved for Long-term Care Medicaid, my Beneficent Case Manager welcomed my calls and emails, continuing to provide her expertise. I will forever be grateful to Beneficent for enhancing the quality of the remainder of Moms (and my) life. If you want to feel more confident about Long-term Care plans for yourself or your loved one schedule an appointment with Stacy Osborne, a Certified Medicaid Planner. In just 1 hour, you will walk away with legitimate ways to pay for Long-term care and this meeting is completely FREE. Stacy Osborne, MBA, CMP Beneficent CEO 719.645.8350
Apr 20, 2023

Trump's Changes to Medicaid
Many Colorado Seniors and Disabled Adults are concerned about the recent funding discussions about Federal, not State, Medicaid changes, and how they might impact Long-term Care Medicaid benefits here in Colorado. There are 40+ different Medicaid programs in the State of Colorado alone, which are funded differently. Some of these Medicaid programs will be impacted by Trumps changes.At this time, it is important to know that the Medicaid changes imposed do not affect Long-term Care Medicaid in Colorado. If you are currently receiving Long-term Care Medicaid benefits or considering applying, you can rest assured that your eligibility, services, and coverage remain intact. Long-term Care Medicaid has already been funded for 2025, therefore nothing will change this year. In addition, there have not been any major changes to Colorado Long-term Care Medicaid in 20 years, and we dont foresee any changes now. In the meantime, if you have any questions about your coverage or need assistance navigating the Long-term Care Medicaid process, please dont hesitate to reach out to Beneficent. www.DoingGoodForOthers.com/contactus
Feb 25, 2025
Top 5 Questions A Certified Medicaid Planner Encounters: Insights for Healthcare Pros and Caregivers
Hello, allow us to introduce ourselves! We are Beneficent, and we provide trustworthy long-term care guidance for deeply caring family members facing a critical long-term care financial crisis.Beneficent helps clients understand, prepare, and qualify for programs covering high costs of Long-term Care including assisted living, adult day care, home care, or skilled nursing homes for seniors and disabled adults.As Certified Medicaid Planers Read our Top 5 questions we hear most.Must I spend down to $2,000 to apply for long-term care Medicaid? No, reducing your assets to $2,000 is not the only route to qualify for Long-term Care Medicaid if your income exceeds the limits. By leveraging legal strategies within Medicaid regulations, we can assist in navigating the income requirements.For 2024, a single applicant is expected to have a resource limit of $2,000, while the limit for a married applicant is about $150,000 If I accept Medicaid assistance will I lose my home?Once a Medicaid recipient passes, the state may seek reimbursement of the amount they paid for in long-term care costs. However, proper planning can protect a home and other assets from a Medicaid claim.I have been told I make too much money to qualify for Long-term Care Medicaid?The best way to figure out your best options is to schedule your first free initial consultation with Beneficent on our home page. (www.doinggoodforothers.com)During that time, we'll review and evaluate your assets to determine if we can help you qualify for a long-term plan4. Is Medicaid Planning legal and ethical?Proper Medicaid planning is legal and ethical and it works to ensure that all rules and regulations are followed.Medicaid planning seeks out effective methods of securing eligibility while preserving assets for the future benefit of the applicant and the applicants loved ones5. Should I apply for Medicaid or VA Aid + Attandance on my own?We appreciate your determination to tackle the application process independently. However, it's important to note that many individuals find themselves facing denials due to the complexity of the process.To support you, we offer a complimentary 1-hour consultation where we share our expertise on how to file for and qualify for these benefitscompletely free of charge.If you feel prepared to dedicate the significant amount of time required and are ready to manage the intricate details involved, we are more than willing to equip you with all the necessary information. Our goal is to ensure that you are informed and confident in whichever path you choose to take, whether it's proceeding on your own or seeking further assistance. Remember, our guidance during the consultation is meant to empower you with knowledge, but navigating the process can still be a challenging endeavor. Call us to schedule an appointment. 719.645.8350 - OR - read more of our FAQs on our website. www.doinggoodforothers.com/faqs
Apr 03, 2024

Will Federal Medicaid Changes Affect Colorados Long-Term Care Medicaid? Heres the Answer
Will Federal Medicaid Changes Affect Colorados Long-Term Care Medicaid? Heres the Answer President Trumps One Big Beautiful Bill (OBBBA) certainly includes far-reaching revisions to Medicaidcuts to provider taxes, new work requirements, tighter eligibility checks, and billions in savings over a decade. But Colorados long-term care Medicaidcovering nursing homes, home health, and other LTSS (long-term services and supports)has unique state safeguards that ensure it remains insulated from these changes. 1. Federal Cuts Mostly Affect Expansion and Non-Elderly AdultsThe OBBBAs primary targets are Medicaid expansion, non-disabled adults, and children, via work requirements and cost-sharing policies. These reforms are expected to phase in during 20272028. In contrast, long-term care beneficiariestypically seniors and people with disabilitiesfall under separate eligibility categories that the bill doesnt restructure. 2. States Can Shield Long-Term Care FundingColorado funds long-term care services through its Medicaid waiver system. The OBBBA reduces providers taxes and places new caps on expansion enrollment, but it does not limit waivers for nursing homes or home- and community-based services. Even without adjusting, Colorado can preserve funding by prioritizing these essential services over general expansion. 3. Colorados Bipartisan Commitment to Aging ServicesColorado has a long-standing commitment to supporting seniors and people with disabilities. In recent years, the state has steadily increased its share of state funds to match or exceed federal contributions, especially for the elderly population. With broad political consensus, any state-level attempt to curtail waivers would be unlikely. 4. Historical Stability Through Waiver ProtectionsSince implementing the Home- and Community-Based Services (HCBS) Medicaid waiver in 2004, Colorado has used it to support aging in place and reduce institutional costs. These waivers have remained stable across administrations and funding changes. Theres no indication that Trump-era reforms would dismantle this proven framework. 5. National Context Supports StabilitySources like KFF confirm that while OBBBA cuts the Medicaid expansion rate from 90% to 80%, and imposes red tape on enrollment, it does not overhaul LTSS (long-term services and supports). Even health-policy experts acknowledge the targeted nature of the reformfocused on non-elderly groups, not those needing long-term care. Bottom Line for Coloradans Trumps Medicaid changes will significantly affect parts of the system serving non-disabled adults, especially in expansion states. But Colorados long-term care Medicaiddriven by federal waivers, state obligations, and a bipartisan mandatestands apart. Residents access to nursing home care, home-based services, and support for people with disabilities is not at risk.
Jul 07, 2025

3 Primary Concerns with Long-term Care
5 Minute ReadLong-term care is an important topic that affects about 70% of all of us who reach age 65 and our loved ones. That 70% represents those of us who will need some level of Long-term Care. What is long-term care exactly? Care that is available for individuals who need help with the basic activities of daily living. Long-term care services include assisted living, adult day care, home care, or a skilled nursing facility.Its important to understand the fundamentals of long-term care, so we can make informed decisions for our future and those of our loved ones. Lets explore the 3 primary concerns with long-term care and where to start when it comes time to make decisions. Availability of Services Long-term care services are in high demand today due to an aging population. This means that its important to research your options as early as possible in order to secure the best services for your needs. Knowing what services are available in your area will help you make the best decision for yourself or your loved one. Costs Costs and quality of care are the utmost concern for most family members, seniors, or disabled adults needing long-term care. Here in Colorado, the average cost for Long-term Care is $8,758 per month according to 2020 state information. You may be able to take advantage of Long-term Care Medicaid or VA Aid and Attendance which can help offset the costs of long-term care services. Most are told they do not qualify for these programs, however, its best to meet with a Certified Medicaid Planner (CMP) to discuss your options. Quality & Safety Considerations When selecting a provider for long-term care services, its essential to do your research and find out more about their reputation and track record when it comes to quality and safety standards. Look into reviews from past customers and ask questions about any accreditations they have received from third-party organizations such as The Better Business Bureau. These organizations provide independent evaluations that can give you peace of mind when selecting a provider for yourself or someone else. Long-term care is an important consideration for many people today, regardless of age or current health status. Although it can seem overwhelming at times, understanding the primary concerns associated with long-term care will help ensure that you are making informed decisions regarding availability, cost, quality, and safety considerations. If you want to feel more confident about long-term care plans for yourself or your loved one schedule an appointment with Stacy Osborne, a Certified Medicaid Planner. In just 1 hour, you will walk away with legitimate ways to pay for long-term care and this meeting is completely FREE. Stacy Osborne, MBA, CMP Beneficent CEO 719.645.8350
Mar 05, 2023
Smart Strategies Every Family Should Know
Smart Strategies Every Family Should KnowPlanning for long-term care is one of the most importantand often overlookedfinancial decisions families in Colorado Springs will face. Whether its in-home support, assisted living, or skilled nursing care, the costs can quickly become overwhelming without a clear plan in place.Many families dont begin thinking about these expenses until a health crisis occurs. By then, options may be limited, and financial decisions are made under pressure. Thats why proactive planning, like the guidance offered by Beneficent and led by Stacy Osborne, can make a significant difference.The Real Cost of Long-Term Care in ColoradoColorado Springs is known for its scenic beauty, active lifestyle, and growing retiree population. But as more people choose to age here, the demand for long-term care services continues to riseand so do the costs.Depending on the level of care needed, monthly expenses can include: In-home care: Several thousand dollars per month Assisted living: Mid-to-high thousands monthly Skilled nursing care: Often $8,000$12,000+ per month Without proper planning, even well-prepared families can see their savings depleted quickly.Why Families Struggle to Pay for CareOne of the biggest challenges is that long-term care is not fully covered by traditional health insurance.Common misconceptions include: Believing Medicare will cover long-term care (it typically does not beyond short-term rehab) Assuming personal savings will be enough Waiting too long to explore financial options Stacy Osborne explains, Families are often caught off guard by how quickly care costs add up. Our goal is to help them understand their options early, so they can make informed decisions instead of reactive ones.Understanding Your Options for Paying for CareThere is no one-size-fits-all solution when it comes to funding long-term care. Instead, families often combine multiple strategies.Private Pay (Out-of-Pocket)Many families initially rely on savings, retirement funds, or income to cover care costs.Long-Term Care InsurancePolicies designed specifically to cover long-term care expenses can significantly reduce financial burdenbut must be purchased in advance.MedicaidFor those who qualify, Medicaid can cover long-term care services. However, eligibility rules are strict and often require planning.Veterans BenefitsVeterans and their spouses may be eligible for financial assistance programs such as Aid & Attendance.Life Insurance ConversionsSome policies allow policyholders to convert benefits into funds for care.The Importance of Early PlanningTiming plays a critical role in long-term care planning. The earlier families begin exploring options, the more flexibility they have.Early planning allows you to: Protect assets Explore insurance options Avoid rushed financial decisions Ensure access to preferred care options Waiting until care is urgently needed can limit choices and increase stress.How Beneficent Helps Families Navigate the ProcessBeneficent focuses on education and strategyhelping families understand the full picture of long-term care financing.Their approach includes: Personalized consultations Education on available funding options Strategic planning based on individual goals Guidance through complex financial decisions Rather than offering a one-size-fits-all solution, they empower families to choose the best path forward.Local Insight for Colorado Springs FamiliesColorado Springs has a unique mix of retirees, military families, and long-time residents. Each group may have different financial considerations and available resources.Beneficent understands: Local care costs and trends Regional resources and programs The specific needs of Colorado Springs families This local expertise ensures that advice is both practical and relevant.Planning for Both Care and LegacyOne of the biggest concerns families face is balancing the cost of care with the desire to leave something behind for loved ones.With the right strategy, it may be possible to: Preserve a portion of assets Protect a spouses financial stability Maintain financial dignity while receiving care Avoiding Common Financial PitfallsWithout proper guidance, families may make decisions that negatively impact their financial future.Common mistakes include: Spending down assets too quickly Gifting money without understanding Medicaid rules Choosing care options without considering long-term affordability Professional guidance can help avoid these costly errors.Supporting Families Through Difficult DecisionsPlanning for long-term care is not just a financial decisionits an emotional one. Families often struggle with: Uncertainty about the future Guilt about care decisions Stress over financial responsibility Having a knowledgeable and compassionate resource can bring clarity and confidence during this process.When Should You Start Planning?If youre asking the question, When should we start?the answer is now.Consider reaching out if: Youre approaching retirement A loved one has a chronic or progressive condition Youre concerned about future care costs You want to explore your options before a crisis occurs Take Control of Your Long-Term Care PlanThe cost of long-term care doesnt have to be overwhelmingif you have a plan.With the right guidance, you can: Understand your options Protect your financial future Ensure access to quality care Take the Next Step Toward Financial ConfidenceIf youre ready to learn how to pay for long-term care without unnecessary stress or uncertainty, Beneficent is here to help.Visit Beneficents Seniors Blue Book listing today to connect with Stacy Osborne and explore your options. A proactive approach today can make all the difference tomorrow.FAQs1. Does Medicare cover long-term care? Medicare typically only covers short-term rehabilitation, not long-term custodial care.2. What is the best way to pay for long-term care? It depends on your financial situationmany families use a combination of strategies.3. Can Medicaid help pay for long-term care? Yes, but eligibility requirements must be met.4. When should I start planning for long-term care? Ideally before care is needed, but its never too late to start. 5. Are there options for veterans? Yes, veterans may qualify for benefits such as Aid & Attendance.
Apr 14, 2026

How to Pay for Long-term Care
Meet Charlie. His brother James has Alzheimer's and needed a memory care facility. They are very close and when it comes to James' care, the prospect of compromising care because of James' limited income was not an option. Funds to pay for the care James needed were a real concern solved by getting information on programs that would assist with the costs of care. Sigh of relief. This family will no longer have to worry about how they are going to pay for James' Care.It is estimated that over 70% of people over 65 will need some type of Long-Term Care (LTC) according to the US Department of Health & Human Services. Colorado has many resources for financial help like Health First Colorado, and Veterans Aid and Attendance Pension that will help pay for in-home care, assisted living, adult day care, and nursing facility care.Most Colorado elderly who need help paying for LTC feel that they will not qualify for these programs because they have too much income or too many assets. Many families are told this by people they feel should be in the know on this topic. There are a lot of myths out there, online and relayed from health professionals. In reality, many could qualify if they had accurate information from a knowledgeable professional, holding a VA Accreditation or a Certified Medicaid Planner (CMP) designation. With uncertain care costs it is valuable to have one person or firm who understands multiple programs for assistance to ensure that all options are considered for the outcome a family desires. Gaining access to programs that assist in paying for long-term care costs will greatly reduce the erosion of hard-earned cash and other valuable assets like family property. Incomplete or inaccurate information often causes people to think they must spend or sell things they own to avoid losing it. This simply is not true and can lead to an unnecessary liquidation of the assets people have worked a lifetime to obtain.There are legitimate means of preserving valuable or sentimental assets and income. Here in Colorado, to the surprise of many, following guidelines carefully afford numerous opportunities to protect income and assets. Consulting with a CMP that specializes in LTC financial solutions can help you and your family to file a successful application and qualify for the program that has the best financial outcome for your family.Editors Note: This article was written by Stacy Osborne, MBA CMP with Beneficent. She can be reached by phone at 719-645-8350 or by email at: [email protected].
Nov 15, 2019
.png)
Practical Solutions to Pay for Long-term Care
70% of people over 65 will need some type of long-term care (LTC). 70% of applicants applying for LTC Medicaid on their own are denied due to inaccurate information. Here in Colorado, the average cost for LTC is $8,758 per month according to 2020 state information. However, there are solutions for how to pay for the high costs of LTC that protect income and assets. Based on the statistics above there is a huge need for services that help people navigate the LTC Medicaid application. A Medicaid planning agency can educate on the financial programs available and expose the plethora of inaccurate LTC Medicaid information. Most Colorado Seniors who need help paying for LTC feel they will not qualify for Medicaid because they have too much income or assets. Some Seniors believe they must spend down (myth #1). In reality, many could qualify if they had the information from a knowledgeable professional, holding a Certified Medicaid Planner (CMP) designation. A CMP assists and educates on how to meet all qualifications and can provide numerous opportunities to protect income and assets! Editor's Note: This article was written by Stacy Osborne, MBA CMP with Beneficent. She can be reached by phone at 719 645-8350 or by email @[email protected].
Jun 26, 2023
Practical Solutions to Pay for the High Cost of Long-term Care
If the high cost of long-term care was not an obstacle, how much care would you or your loved one need? Beneficent has been privileged to successfully assist more than 3000 families and individuals through asset preservation in the face of high long-term care costs for over 20 years. Our work is much more than just a business. It is an opportunity to practice our faith through compassionate service that sees every individual as one of infinite worth. Did you know that 70% of all of us who reach age 65 will need some level of Long-Term Care? Weve heard hundreds of stories all with the same concern how to get the best long-term care in place for themselves or loved ones. Children worry about their parents falling. Spouses are concerned about how they can continue to care for their partner who is rapidly mentally and physically declining. Adults want to know about a financial plan because the average cost for Long-term care is $8758 per month according to current Colorado state information. Families are stressed about losing everything in order to pay for long-term care. We have heard it all. No matter what your circumstance, 100% of our clients who are seniors and disabled adults have leveraged the programs to pay for the best care they need, not how much they can afford. These programs cover assisted living, adult day care, home care, nursing homes, or senior living. As Certified Medicaid Planners, our clients benefit from step-by-step guidance which results in financial solutions to minimize spend down, preserve assets and limit out-of-pocket expenses. We give families peace of mind and predictability regarding the financial concerns surrounding long-term care expenses of their loved ones. Learn more and schedule an appointment here: Editors Note: This article was written by Stacy Osborne, MBA CMP with Beneficent. She can be reached by phone at 719-645-8350 or by email at [email protected].
Jul 13, 2022

Feel Relief About Long-term Care Costs in 5 Minutes
Seniors, disabled adults, and our friends working with seniors all feel the same sense of chaos as being in a busy coffee shop with just one employee. Understanding the programs that pay for long-term care for seniors or disabled adults can be overwhelming and stressful because there are so many misconceptions about the qualifications. Long-term care programs coverassisted livingadult day carehome careand nursing homesBeneficent Cuts through the Complex Long-term Care Program Qualification in 4 Steps1. Schedule a Free Initial ConsultationLearn more about what we can do for you to preserve assets.2. Make a PlanThrough an assessment of financial circumstances, we will begin to make a road map of the best options for you.3. Youll Have OptionsWe explore legitimate opportunities to preserve assets.4. Financial Application Confidence and AssuranceYou can select the best option. We will complete a successful application and outcome. Beneficent provides a stress-free experience with information you can trust. Contact our office at 719.645.8350 to learn more.
Oct 01, 2023

Caregiving for the Caregiver
Caregiving for the Caregiver Have you had a chance to pick up the October issue of Real Simple magazine yet? If not, it's time you did! In fact, it's our CEO's favorite magazine read because it is all about how to make life just a little bit simpler. Dont we all need that! This month, there's a particular article that speaks directly to youthe caregivers. Now, some of us have been on this caregiving journey for years, while others may have recently embarked on this path. And if you arent a caregiver yourself, chances are you know someone who is. According to Real Simple, in 2020 alone, approximately 53 million Americans were caregivers. That number is set to grow, with projections suggesting that one in five of us could be caregivers by 2030. Its a humbling statistic that reminds us all of the broader support network we might one day be a part of. At Beneficent, we're currently immersed in a book called The Go-Giver. It's an inspiring read that highlights how givingin any formcan lead to business success and personal fulfillment. Without giving away too much, the book emphasizes creating more value for others than what you receive in return. For us, this means offering more than just our services to caregivers like you. We want to provide you with certainty and peace of mind, ensuring that your financial resources are sufficient to care for your loved ones, allowing you to finally take that long-deserved vacation. Whether you are a caregiver or you know someone who is, its important to remember to give a little care back to yourselves. Caregiving is an incredibly rewarding but often challenging role. It can sometimes feel isolating, physically demanding, and emotionally taxing. If you're a caregiver, remember to carve out time for yourself, even if its just a few precious moments each day. And for those of you who know a caregiver, think about ways you can support them. A small gesture, a listening ear, or some practical help can go a long way in easing their load. Ultimately, whether you're the caregiver or the one supporting them, remember that were all here to support each other in this community. Taking care of those who take care is a gift in itself.BeneficentWe provide trustworthy long-term care guidancefor deeply caring family members facing a critical long-term care financial crisis. We help clients understand, prepare, and qualify for programs covering high costs of Long-term Care including adult day care home care assisted living memory care nursing homes.
Nov 07, 2024
How to Preserve Assets When Faced with Long-term Care Costs
Meet Charlie and Fran. They have three children, 9 grandchildren and 5 great grandchildren so far! They have hopes and dreams for their future generations and have worked hard to ensure their legacy is passed on. As they age, they realize that if either one of them needs Long-term Care, that their property and other assets could be at risk. They need accurate information they can trust so that if Long-term Care needs come on suddenly, they are prepared and able to protect their assets.It is estimated that over 70% of people over 65 will need some type of Long-term Care (LTC) according to the US Department of Health & Human Services. Colorado has many resources for financial help like Health First Colorado, Colorados Medicaid Program and Veterans Aid and Attendance Pension that will help pay for in-home care, assisted living, and nursing facility care.Most Colorado elderly who needs help paying for LTC feel that they will not qualify for these programs because they have too much income or too many assets. In reality, many could qualify if they had the information from a knowledgeable professional, holding a VA Accreditation or a Certified Medicaid Planner (CMP) designation. The problem is that often plans for one program will conflict with good planning for the other. With uncertain care costs it is valuable to have one person or firm who understands multiple programs for assistance to ensure that in planning for one solution, an applicant isn't disqualifying themselves for future aid from other programs. Aid and Attendance is available only to veterans who have served during wartime. It has a cap to benefits and if costs of care exceed the VA maximum benefit, then other programs will offer a better solution.The rules of eligibility are readily available online. However, incomplete or inaccurate advice often causes people to think they must spend down to qualify for these programs. This simply is not true and can lead to an unnecessary liquidation of the assets people have worked a lifetime to obtain.There are legitimate means of preserving valuable or sentimental assets and income. Here in Colorado, to the surprise of many, following guidelines carefully afford numerous opportunities to protect income and assets. Consulting with an accredited firm and CMP that specializes in LTC financial solutions can help you and your family to file a successful application and qualify for the program that has the best financial outcome for your family.Editor's Note: This article was written by Stacy Osborne, MBA CMP with Beneficent. She can be reached by phone at 719-645-8350 or by email at: [email protected]
Sep 07, 2019
Can I Preserve Assets and Still Qualify for Medicaid?
Meet Charlie and Fran. They have three children, 9 grandchildren and 3 great grandchildren. They have worked hard and enjoy life on their small family farm. This place is important to their entire family. As they age, they realize that if either one of them needs Long Term Care, that their property and other assets could be at risk.They need accurate information they can trust so that if Long Term Care needs come on suddenly, or if Long Term Care is some years away, they are prepared and are doing all they can to ensure that their future generations can enjoy this farm and other things they have worked hard for.It is estimated that over 70% of people over 65 will need some type of Long Term Care(LTC) according to the US Department of Health & Human Services. Colorado has many resources for financial help like Health First Colorado, Colorados Medicaid Program. Medicaid will help with in home care, assisted living and nursing facility care.Most Colorado elderly who need help paying for LTC feel that they will not qualify for Medicaid because they have too much income or too many assets. In reality, many could qualify if they had the information from a knowledgeable professional, holding a Certified Medicaid Planner (CMP) designation. The role of a CMP is to assist an applicant file a complete and correct Medicaid application and work with the Department of Human Services to gain approval for LTC Medicaid.The rules around Medicaid eligibility are readily available online. Incomplete or inaccurate advice often causes people to think that spend down is the only way to qualify for LTC Medicaid. This simply is not true and can lead to an unnecessary spend down and/or liquidation of the limited assets people have worked a lifetime to obtain.There are legitimate means of preserving valuable or sentimental assets and income. Here in Colorado, to the surprise of many, the Medicaid guidelines afford numerous opportunities to protect income and assets. Consulting with a CMP who specializes in LTC can help you and your family to file a successful application and qualify for Long Term Care Medicaid.Editors Note: This article was written by Stacy Osborne, CMP with Medicaid Consulting Group. She can be reached at 719-645-8350 or by email at [email protected].