Bellomo & Associates
3198 E Market St, York, Pennsylvania, 17402
Counties Served: Pennsylvania - Adams, Cumberland, Dauphin, Franklin, Lancaster, Lebanon, Lehigh, Perry, York
Estate Planning


About Bellomo & Associates
See More
Videos
Continue Your Search! Explore More Local Options.
Start SearchingLet’s engage and get educated!
Browse through thousands of expert articles in over 100 different categories.
Browse NowArticles You May Like
One Small Decision Costs You Medicaid: The Mistakes Families Never See
We Thought We Were Doing the Right Thing. That is how these conversations almost always begin. A daughter sits across from our team, frustrated and confused. A few years earlier, she helped her mother by moving money into her own account for safekeeping. It felt responsible. It felt protective. But now her mother needs nursing home care, and Medicaid is reviewing that transfer. What seemed like a simple act of helping may now delay the very benefits her mother depends on. This situation is far more common than most people realize. Families do not set out to break Medicaid rules. They make thoughtful, well-intentioned decisions without understanding how those decisions will be viewed later. And unfortunately, Medicaid does not evaluate intent. It evaluates transactions. To understand how families accidentally disqualify themselves from Medicaid, you first need to understand how the system actually works. The Rules Most Families Never See ComingMedicaid has become the primary payer for long-term care in the United States. With nursing home costs often reaching thousands of dollars each month, many families eventually rely on Medicaid to help cover the expense. What surprises people is that Medicare, which many assume will step in, typically only covers short-term skilled care under limited conditions. Long-term custodial care is almost always a Medicaid issue. Because of the scale of this responsibility, Medicaid enforces strict eligibility rules. These rules are designed to ensure that benefits go to those who truly need them. But in practice, they often catch families off guard. People who have spent years saving, helping loved ones, or making practical financial decisions suddenly find themselves facing penalties for actions they never realized could be a problem. The Five-Year Look-BackAt the center of this is the Medicaid look-back period. In most states, this period covers the five years leading up to a Medicaid application. During that time, the state reviews financial records to determine whether assets were transferred for less than fair market value. This includes gifts, property transfers, changes in ownership, and even informal financial arrangements within a family. From Medicaids perspective, the question is simple: Were assets given away or moved in a way that reduced what was available to pay for care? From a familys perspective, the answer is rarely that straightforward. Everyday Decisions That Create Big ProblemsThink about the decisions families make every day. A parent helps a grandchild with tuition. A car is sold to a family member at a discounted price. A child is added to a bank account to make bill-paying easier. A daughter receives occasional payments for helping care for a parent. Each of these choices feels normal. In many cases, they feel necessary. But without the right structure and documentation, Medicaid may view these actions as gifts or uncompensated transfers. One of the most common misunderstandings involves gift rules. Many families believe that as long as a gift falls within the IRS annual exclusion, it is safe. It is not. Medicaid does not follow IRS guidelines. A gift that is perfectly acceptable for tax purposes can still create a penalty when it comes to Medicaid eligibility. When Good Intentions BackfireOther issues show up in ways families never expect. Assets may be sold without clear documentation. A family may believe they received fair value, but without proof like an appraisal or written agreement, Medicaid may see it differently. Trusts can also create confusion. Many people hear that trusts protect assets from Medicaid. While that can be true, timing and structure matter. Transfers made during the look-back period can still trigger penalties. Even paying a family member for care can create problems if there is no formal caregiver agreement in place. What was meant as support can be treated as a gift. This is where the disconnect becomes clear. Families act out of care, trust, and responsibility. Medicaid evaluates those same actions through a strict financial lens. The Cost of Getting It WrongWhen a disqualifying transfer is identified, Medicaid imposes a penalty period. This does not mean someone is permanently denied benefits. Instead, coverage is delayed based on the value of the transfer. The result can be devastating. During that penalty period, the individual may otherwise qualify for Medicaid but receives no assistance. The family is left covering the cost of care out of pocket, often during an already stressful and emotional time. The Good News: This Is PreventableWhat makes this especially frustrating is that many of these situations could have been avoided. The difference between a smooth Medicaid approval and a costly delay often comes down to three things: timing, documentation, and proper planning. When families plan ahead, they have options. They can structure decisions correctly, protect assets, and avoid unnecessary penalties. When planning is delayed until a crisis, those options become much more limited. At Bellomo & Associates, we see both sides of this every day. And we know how much easier this journey can be when families have the right guidance in place early. A Simple Step That Can Make All the DifferenceBefore you move money, add someone to an account, sell property, or try to help a loved one qualify for care, take a moment to consider how that decision might be viewed years from now. Because when it comes to Medicaid, the smallest decisions can have the biggest consequences. If you are not completely confident that your current plan would hold up under Medicaid rules, this is a great time to get clarity. We invite you to register for a workshop with Bellomo & Associates, where you can learn how to protect what you have worked so hard for and make things easier for your family when it matters most.
Jun 05, 2026
I Am a Beneficiary of an Estate. How Long Will it Take For Me to Get My Money?
This is a question that we receive at least once a month if not more in our office. Individuals who were named in a Last Will and Testament as a beneficiary, once they realize that they are a beneficiary, want to know how long it will take for them to receive their inheritance.The probate process in the Commonwealth of Pennsylvania is actually a very straightforward process. Many states in the country have a very complicated process that individuals have to go through, but Pennsylvania is not one of them. However, that does not mean that an individual who is named as a beneficiary will receive their money overnight because there are a lot of things that have to occur before a beneficiary can get the money that they are entitled to under the Will.In the Commonwealth of Pennsylvania, there are requirements of an executor that he or she must comply with in order to ensure that he or she will not be personally responsible or liable for the taxes or to the beneficiaries. For example, an executor must provide notices to heirs as well as advertise the estate in the local newspaper and local legal journal to provide notice to creditors to start the statute of limitations for creditors to come forward with a claim. The executor must also get the date of death valuation letters from every institution that holds an account or had an asset of the decedent at the time of their death.Once the executor and the attorney for the estate receive all the date of death letters, they are then in a position to begin to prepare the Pennsylvania inheritance tax return. Once the Pennsylvania inheritance tax return is prepared and filed it can take the Department of Revenue up to one year to review and approve the return. It typically takes 6 to 9 months for the approval process but can take up to 1 year. Typically the attorney will prepare receipts and releases for each and every beneficiary if the estate is going to make a partial distribution to the beneficiaries prior to receiving approval from the Department of Revenue.It is always my recommendation to the executor not to distribute all monies to the beneficiaries at this point because the Department of Revenue still has to sign off on the appraisement and the tax return agreeing that they are not looking for any additional tax in the estate.It is also worth noting that there is a significant time delay currently with the Department of Revenue and receiving notice back of the inheritance tax and that the appraisements are okay. As of September 2020, we had filed appraisements in October 2019 that we still had not gotten final approval back on. This is significant because although the normal lag time is five to six months, we are currently seeing about a 10 to 12-month delay in receiving the appraisements back from the Department with final approval currently.I always recommend to my executors that they not make final distributions and have the beneficiary sign off on the receipts and releases/family settlement agreement until we have the final paperwork back.It is obvious that in the current times, In light of COVID and the state having to close for a period of time and not getting to any tax returns, the time frame from a beneficiary to receive their money under current times is fairly significant. However, this is not normal, and under normal circumstances, the final appraisal certainly would be quicker.It also is a case-by-case basis as to how much we can distribute before receiving the final word from the government. In some situations, when theres a close family, they will distribute more with partial distribution than in other situations. In a case where it is contentious and there are beneficiaries who are not family or who have caused nothing but issues, we will often recommend that we not distribute anything until we get the final word from the Department. In these cases, under the current situation, it could take a year or more before we are in a position to be able to do that.It is important to know that in a situation where somebody does a living trust or a Grantor trust in the Commonwealth of Pennsylvania and retains control, an inheritance tax return is still required to be filed. That means that even under a trust administration if we are waiting on the Department to approve the inheritance tax return, the time frames would remain the same. I say this because many people think that probate is the problem, or that it is the fault of the local Register of Wills or Orphans Court, but in reality, that is not it at all, we are at the mercy of the Department of Revenue for final approval of the inheritance tax return.For any questions or assistance through this process, please contact us at (717) 844-9218. We would love to help you.
Jul 28, 2023
Estate planning and the Dysfunctional Family
Over my career as an estate planning and elder law attorney, I swear I have seen just about everything. I cannot remember a fact pattern that surprised me or took me aback. I am honestly at the point now where I think that dysfunctional is the norm for the common family that we assist. Im not sure if its because we specialize in estate planning and elder law and we get referrals and cases that are more complex and more advanced than others, or if that is just the norm these days. My gut says it is probably the latter. I did some research to define the word dysfunctional, and there is no clear-cut definition. But my gut would say that dysfunctional would include families such as second marriages with kids to different relationships, as well as addictions or spendthrift issues, or just family dynamics in in-tact families where people do not care for each other. Again, I think this is probably the norm more than any exception. It is imperative that families are open and honest with their attorney so that the attorney can put a plan in place that addresses what they need for their specific situation. Dysfunction does not present as the same fact pattern in any two cases, and therefore an experienced estate planning attorney is needed to be able to dot the Is and cross the Ts. Be very wary of the do-it-yourself sites or general practice attorneys who dont specialize in this area if there is a complex fact pattern for you and your family. We love assisting any and all families and certainly love putting the fun in dysfunctional. We look forward to providing an estate plan that is unique for you and your family, whether you are dysfunctional or as functional as anyone else. Please feel free to give us a call if you have any questions or comments at 717-845-5390.
Dec 26, 2022
.png)
Its Not Enough Just to Have Documents
Protecting your health and well-being is a top priority, especially as we get older. One important way to safeguard yourself is by creating a health care power of attorney document. This legal document designates a trusted individual to make health care decisions on your behalf if you become incapacitated. But as important as creating this document is, its not enough to simply have it you also need to make sure its in the right hands.A recent story shared by a friend highlights just how critical it is to ensure your healthcare power of attorney is given to the appropriate parties. In this case, a woman was acting as the power of attorney for her mother but didnt have the document on hand when her mother needed medical attention. The hospital demanded the document immediately, and in the chaos of the moment, the daughter ended up agreeing to have her mother fill out a new one on the spot.The problem arose when the nurse asked who should be listed as a power of attorney. The daughter suggested including herself and her mothers husband, who had raised her and was like a father to her. But her mother insisted that only her daughter be listed, causing tension and awkwardness between the family members. It was a situation that could have been avoided if the daughter had simply provided the existing document to the hospital.This story underscores the importance of not only creating a healthcare power of attorney but also ensuring that it is given to the appropriate parties. At Bellomo & Associates, we urge our clients to not only create these documents but to also provide copies to their doctors and keep them on file at hospitals. We provide extra copies so family members can have them as well. Taking these steps can help you avoid any unnecessary stress or heartache should an emergency situation arise.Creating a healthcare power of attorney is a smart move, but its only half the battle. To ensure that your wishes are carried out properly, its crucial to share the document with your healthcare providers and loved ones. Dont let a lack of preparation cause unnecessary tension or problems for your family take the necessary steps to protect yourself and your loved ones.Please give us a call at 717-845-5390 and well set you up with a free consultation or register for a free workshop by clicking here.
Feb 23, 2024
Managing Long-Distance Caregiving: Practical Guidance for Adult Children Living Out of State
Managing Long-Distance Caregiving: Practical Guidance for Adult Children Living Out of StateCaring for a parent from another state is increasingly common. According to AARP, approximately 11% of family caregivers live an hour or more away from the loved one they support. Distance doesnt mean disengagement, but it does require a different approach to caregiving, one rooted in organization, awareness, and thoughtful planning rather than proximity.When done well, long-distance caregiving can support independence and dignity for years. The key is knowing what to stay on top of, what to watch for, and when local insight becomes essential.Staying Organized Is the FoundationDistance makes organization critical. When information is scattered, even minor issues can feel overwhelming.Important details to keep accessible include:Medications and pharmacy informationHealth care providers and recent appointmentsInsurance detailsEmergency contactsLegal and financial documentsMany families use shared digital folders so information can be accessed quickly when questions arise.Establish Consistent, Meaningful Check-InsRegular communication matters, but it is most effective when it goes beyond quick updates.Helpful strategies include:Scheduling predictable phone or video callsAsking about daily routines, not just healthUsing video periodically to observe mobility, appearance, and surroundingsNoticing changes in tone, energy, or engagement over timePatterns often reveal more than single conversations.Build a Local Circle of Support EarlyEven when a parent is independent, local connections add stability.This may include:A trusted neighbor or friendA faith or community contactA primary care provider familiar with baseline healthLocal professionals who understand senior resources in the areaThese relationships provide perspective when distance limits visibility.Use Technology ThoughtfullyTechnology can be a helpful bridge for long-distance caregivers. Video calls, shared calendars, medication reminders, and emergency alert systems can support independence.However, technology mainly responds after something happens. It cannot assess emotional well-being, social isolation, or whether daily routines are becoming more difficult to manage.Technology informs. People notice patterns and intervene early.Know What to Watch For When Things Feel OffChanges often appear gradually.Long-distance caregivers may notice:Missed appointments or medication confusionIncreased reliance on neighbors or informal helpShorter or less engaged conversationsDeclining home upkeep during visitsFatigue, hesitation, or balance issues that were not present beforeIndividually, these may not signal immediate change. Together, they often indicate evolving support needs.Visit With PurposeIn-person visits offer insight that phone calls cannot.During visits, observe:How easily daily routines are managedWhether the home still supports independenceChanges in stamina, balance, or cognitionHow meals, medications, and social activity fit into daily lifeThese observations help clarify how independence is functioning, not just whether it exists.When Planning for a Possible Move, Local Insight MattersAs families begin to consider whether additional support or a future move may be appropriate, understanding the local senior care landscape becomes essential.This includes knowing:What types of senior living exist locallyHow care levels differWhat availability typically looks likeHow transitions are commonly handled in that areaFor many long-distance caregivers, this understanding comes most clearly through conversations with a local senior placement advisor who knows the communities and care models in that specific region.For example, an adult child living out of state may assume assisted living is the next step, only to learn that one nearby community emphasizes social independence with limited medical oversight, while another offers flexible support that allows a parent to remain more autonomous. These distinctions are rarely obvious online, yet they can significantly affect comfort and fit.Local insight provides clarity even when no immediate decision is planned.Planning Ahead Preserves ChoicePlanning does not mean committing to a move. It means understanding options before urgency narrows them.When planning happens early:Loved ones can participate in conversationsPreferences are clarified while decisions are easierFamilies are not starting from scratch if circumstances changePreparation allows distance to feel manageable rather than overwhelming.A Thoughtful Approach to Care From AfarLong-distance caregiving works best when it is intentional, informed, and supported locally. Staying organized, maintaining meaningful communication, building local connections, and knowing when to seek local guidance all help families support independence while remaining prepared.Distance does not prevent good caregiving. With the right structure and awareness, it can be managed thoughtfully and with confidence.
Jan 05, 2026
Why is it Important to Understand or Learn Probate in the Commonwealth of Pennsylvania?
This is a question that we receive all of the time in our office. The answer is that you could have personal liability as an executor because there may be ways to avoid probate if you understand it and plan ahead.Probate is merely the Commonwealths rule book and the process that you must go through if there is an asset in a persons sole name at the time of their death. This excludes jointly held accounts and accounts with a beneficiary designation on the account. Probate is not good or bad. It is simply the process the Commonwealth requires us to follow in order to properly distribute assets to beneficiaries.A personal representative, also known as an executor (or executrix if they are female), if they are named in a Will, or an administrator if they are taking authority under the intestate succession under the statute, is personally liable to the beneficiaries and to the government to properly administer the estate, make certain all debts and expenses of the decedent are paid, pay all inheritance tax and other taxes owed and to distribute the remainder of the assets to the beneficiaries pursuant to the Will or the intestate statute. A personal representative must understand the entire process and all of the legal requirements that the Commonwealth imposes, such as notices to heirs, notices to creditors, advertising of the appointment of a personal representative and filing with the Orphans Court, Register of Wills certifications and notices as items are completed or when the estate is complete. There is also a requirement for a Pennsylvania inheritance tax to be prepared and filed and, in some cases, a fiduciary income tax return as well. If any of these steps are not properly completed and a beneficiary, a government entity, or a charity receives less money than what they were entitled to there can and will be personal liability imputed on the personal representative.It is essential to understand this liability to make a decision as to whether to hire an attorney to assist in the process. There is very little upside to not hiring a professional but a lot of potential downsides to not doing so, and therefore, typically, it is a much smarter decision to engage an attorney to assist you.Probate can be avoided by either making an asset jointly owned or designating a beneficiary for that asset. However, before somebody makes an asset jointly owned or designates a beneficiary for an asset they should understand the legal implications of doing so as there may be considerations beyond probate in doing so. Remember jointly owned assets or assets with designated beneficiaries dont avoid inheritance tax, only probate is avoided.If you have any questions concerning probate or whether you need to probate please call the office at (717) 844-9218 or visit our website at www.bellomoassociates.com
Jun 16, 2023
I Am a Parent of a Child With Special Needs; Where Do I Start?
We are often in the community giving workshops or presentations at community events or local churches and nonprofit organizations. It is typically fairly obvious based on the angst on the person's face and the pure emotion when they are the parent of an individual with a disability and special needs. They don't know where to start, they don't know what questions to ask, and they do not know where to turn for the answers. While we believe in education for all of our clients, regardless of the situation, it is absolutely the key and the first step for a family with an individual with special needs. It's never too early to start getting information and understanding the different options for dealing with where you are and what options may be available in the future. In the Commonwealth of Pennsylvania, when a person reaches the age of majority, which is 18 years of age, they are presumed to have the capacity to make decisions on their own. I advise individuals with special needs family members to contact us prior to the individual's 18th birthday so that we can determine whether or not we are going to be able to enter into a power of attorney or if we are going to have to go through the steps of a guardianship proceeding. Once we get over that first hurdle and have evaluated the level of involvement another person will need to have to best protect the interests of the individual we can then start mapping out a route and start planning for the future. We will then discuss different options such as special needs trusts, ABLE accounts, and how life insurance may fit into the plan. Please get in touch with an expert in the area of special needs planning to start the conversation and determine the best path to move forward. We offer a special needs planning workshop, not only live, but also via an on-demand link for you to watch at your convenience. If you would like more information about our special needs planning workshops, please contact our office at 717-845-5390.
Oct 13, 2023

Adventures in Soap Making Part II
As one of my new favorite YouTube soap-making friends, Katie Carson of Royalty Soaps, would say, lets make some soap!What exactly do you need to make soap?Pretty simple ingredients it turns out. Distilled water, lye, and olive oil will get you a basic Castile soap. This type of soap was made famous by the city of Castile in Spain. Because this soap uses only olive oil it takes a long, long time to cure. The best Castile soaps are aged for a year or more. So for those of us who are impatient, there are other oils that you can add to make your soap cure more quickly because they are hard versus the liquid olive oil. The most frequently used of these hard oils are coconut oil and palm oil. You can find many recipes online that use only olive oil and coconut oil which you can purchase at the grocery store or Sams Club or lard can be used as well and is pretty easy to find. And you can use a cardboard box lined with freezer paper for a mold so you can get started pretty inexpensively. The process is simple. You mix lye with distilled water in a prescribed proportion, melt your hard oils and mix them with your liquid oils, again a prescribed ratio, and mix the lye water into your oils until it reaches trace or thickens (but not too much, about the consistency of thin pudding) and pour into a mold. Let it sit until is saponified, about 24 hours, remove it from the mold, cut, and cure for 6 weeks and, voila, you have soap.Easy right?Yes, it actually is pretty easy but it takes some practice to make sure you mix it enough but not too much. And this isnt like your grandmothers or great-grandmothers lye soap which could just about eat through your skin. You have the advantage of being able to purchase lye and measure it in exact amounts to produce a good product every time. The lye soap most people remember was harsh because folks made their own lye solution by boiling ashes from a hardwood fire in rainwater, allowing the ashes to settle to the bottom and skimming the liquid lye off the top. Using that method you had no way of knowing the concentration of the lye so many times it was too strong. But the fun part, the part that made me want to make soap, is all of the colors and fragrances you can use in your soap. And how you can mix the colors to make patterns and scenes or just the happy accidents in mixing colors that can happen. There are also many other oils you can experiment with to make your soap more moisturizing or have a different consistency and many other things. There is actually a lot of science behind soap. Maybe if we had made soap in chemistry class in school I would have been much more interested!Check out Royalty Soaps Creative Academy on YouTube if you want to try your hand at soap making, it is a free series of video tutorials. You can find lots of pictures online of the awesome soaps people have created. The one included here is a picture of one of mine!
Jan 19, 2024
Having The Conversation or The Talk With Your Adult Children About Their Inheritance
It is very rare for us to assist a family with their estate planning we are not asked by the parents whether or not they should talk to their adult children about their estate planning and about the inheritance. For years, I always recommended to clients that they have the conversation up front early and often with their kids. I always believe in full transparency and no surprises. Particularly in a situation where you may be providing for charities or other outside individuals, or maybe are not providing for your children equally. I would always recommend to the parents that they try to let the children know that they plan to have the conversation and when. Giving the children a chance to come to grips with the fact the mom and dad are going to be talking to them about death and potentially the future. I always recommend that they do it around the period when there is not a lot going on in the childrens lives such as buying a new home, having a new child, or some major life event.For years I would hear from clients who were so glad that they did have the talk with their kids and maybe even had several conversations. Although kids are typically skittish about talking about death, once you have the conversation theyre grateful to have an insight into your thoughts, ideas, and where you are headed. I rarely found children who didnt want to carry out the wishes that Mom and Dad intended. Typically, the problem that we run into is if mom and dad did not tell the children clearly about what they intended the children end up fighting over the intent of the parent. Having the conversation ahead of time typically eliminates the issue of fighting about intent later. I recently had several clients come back to me and tell me that the conversation did not go well and that the children and their relationship changed because of it. I tried in several of the conversations to dig a little deeper to figure out exactly what happened and where things went wrong, but unfortunately, I was unable to get enough detailed information to ascertain where the issue arose, what the issue was actually all about, and why it has changed the relationship. Due to the fact that I was unable to truly dig to find out what happened in the context of the conversation, I am hesitant to still not recommend having an open and honest conversation. My one client specifically said that he wished he would not have had the conversation ahead of time and it wouldve been better just to allow the documents to speak for themselves and allow him to die. I understand where he is coming from, especially since he believes that having the conversation changed the relationship.I still believe that it is better to know that up front, and to be open and honest and know where you stand. The bottom line is that it is your estate planning, and you do not need permission from anybody, including your children, about doing it. Having the talk with them is more to make their lives easier after you are gone, and honestly is about them and assisting them moving forward, and also making mom and dad feel good. I do feel bad that a couple of the conversations didnt go as planned, but maybe it opened up other issues that were there anyway, that were going to come up, and maybe now better than later. We wish you nothing but the best in having a conversation with your kids about the inheritance and your estate planning. It is always a good idea to have your attorney have the conversation with them as well as to have a third party provide the information. We often have this conversation at no additional charge for our clients to help guide the conversation.Please contact our office if you would like to discuss your estate planning or have us assist you in discussing these issues with your children. For any questions or help having this difficult conversation with your family, contact us at 717-208-4546.
Aug 10, 2023

Planning Options for Unsupported Elders or Elder Orphans
Unsupported elders or elder orphans are individuals in the elder community who face social and/or physical isolation without any available known family members or designated surrogates or caregivers. This growing phenomenon is becoming more common, with AARP reporting that one in five Americans over the age of 65 are at risk of becoming elder orphans. Factors such as higher divorce rates, the decision not to have children, and the boom in this demographics population contribute to this trend. At Bellomo & Associates, an estate planning and elder law firm in Pennsylvania, we understand the unique challenges faced by unsupported elders and offer solutions tailored to their needs. Seeking Support:Being an elder orphan does not imply a lack of financial resources but rather a lack of social support. Fortunately, various support groups and initiatives are emerging to address this issue. Adopting a family, finding a roommate exploring co-housing options, considering intergenerational housing, joining life plan communities, or becoming a member of online communities like Facebook groups for elder orphans (with over 6,000 members already) are some basic solutions to combat isolation. Additionally, we advise clients in similar situations to explore retirement communities or other living arrangements promoting social interaction. Its also worth noting that professional individuals can serve as Healthcare Power of Attorney agents and financial Power of Attorney agents, even if they are not family members, ensuring that essential needs are met if the means to pay for them are available. Exploring Alternative Opportunities:For individuals in this situation, it is crucial to seek out alternative options and establish reliable connections actively. This article highlights the importance of finding people they can rely on or paying for services if they have the means to do so. By engaging with a supportive community, whether through personal relationships or professional assistance, unsupported elders can enhance their quality of life and ensure their well-being as they age. At Bellomo & Associates, we understand the concerns and challenges faced by unsupported elders or elder orphans. We are here to provide comprehensive estate planning and elder law services tailored to your unique situation. Dont navigate this journey alone. Take charge of your future by seeking out the opportunities and support available to you. Visit our website today to learn more about how we can assist you. Be sure to register for our free educational workshop to gain valuable insights and guidance. Together, we can ensure peace of mind and a secure future for you or your loved ones.
Feb 07, 2025
Do You Need a Trust?
This question is by far the most asked question that we receive in our office. However, there is absolutely no standard or right answer for everyone. Trusts are typically used for either probate avoidance purposes, tax avoidance purposes, or asset protection. Trusts are often used for disability planning but generally, that is not the sole reason for peoples use of trusts.The federal estate tax limit currently provides an $11.7 million exemption per person. This means that an individual currently will not pay federal estate tax unless their estate, per person, goes over $11.7 million or $23.4 million for a husband and wife. This law is set to go back to $5 million in 2025, set for inflation which predictions are that it will end up being around $5.8 million. Even with the reduction in 2025, most people in our local community will not need to do a trust for tax purposes. Certainly, there are rumors each and every day about Congress changing the laws and lowering the exception amounts, but until that happens, I would not make plans for something that may or may not occur. History tells us that all of the rumors that we are hearing, probably none of them will actually look like the actual law if it is ever enacted, and we have always taken the position to plan for the law as it is in effect, and if and when it changes, then we can pivot. With that said, there is not a high percentage of people who will need to do trusts for tax purposes as we sit here today in May of 2021.Probate avoidance is usually a situation where there are properties in several different states across the country. While every state has different laws as to whether a person needs to open an estate in their specific state, generally speaking, if the property is in a persons name alone at the time of their death, the state will require them to go through that states probate process. We find that many people like to avoid probate in these situations so that they do not have to hire attorneys in each state to finalize for their families. In a situation where a family does not have properties in multiple states, generally, probate avoidance is not something that people are overly concerned about unless theyre in a state that the probate process is very burdensome and overwhelming, which currently, it does not happen to be in the Commonwealth of Pennsylvania.Asset protection is one reason that people will often do trusts in the Commonwealth of Pennsylvania, to avoid potential creditor issues and long-term care costs. These are a very specific animal of trusts and the rules are very unique to these trusts alone since they are not being set up for tax purposes. It is our recommendation that you speak to a professional well-versed in these types of trusts before completing one. They are very unique and there are very simple rules; however, it is very easy to make mistakes in this area. An elder law attorney well versed in these types of trusts will be able to provide advice as to whether this type of trust makes sense for you. There is no one size fits all answer to the question of do I need a trust?. It is important to get very clear on your personal goals and what your goals are for your family. Once you have a very clear picture of that, then a professional will be able to advise you, based upon your current situation, as to whether it makes sense. We would certainly be honored to assist you through this process, and we offer weekly workshops which will give you insight into the thought process in regards to whether trust is right for you. We look forward to seeing you in the future.If you are looking for advice in regards to estate planning, please call our office at 717-844-9639 or click the link here and we will contact you.
Apr 19, 2023
What If the Will Is Contested?
Everything was supposed to be settled. I have had families sit across from me at Bellomo & Associates who say exactly that. The documents were signed. The will was in place. They expected the process to be simple and straightforward. Then someone raises a concern, This doesnt seem right. In that moment, everything changes. What should have been a smooth process can quickly become complicated. Emotions rise. Questions surface. And families who are already grieving suddenly find themselves in conflict. A contested will can delay probate, increase costs, and create tension that lasts far beyond the legal process. What many people do not realize is that this is not just a disagreement. It is a formal legal challenge that follows a very specific process. Understanding what happens next can help you prepare and, in many cases, avoid it altogether. What It Means to Contest a Will When someone contests a will, they are not simply expressing frustration or disappointment. They are asking the probate court to step in and determine whether the will is legally valid. The court does not automatically invalidate the document. Instead, it takes a closer look at how the will was created and whether it truly reflects the persons intentions. That distinction matters. A challenge does not mean the outcome will change. It simply opens the door for the court to review the situation more closely. And not everyone has the right to bring that challenge. Who Can Contest a Will This is one of the first surprises for many families. Not everyone can contest a will just because they feel upset or left out. To bring a legal challenge, a person must have what is called standing, meaning they have a direct financial interest in the outcome. This could include someone who was left out of the will, someone who would inherit if there were no will, or someone who was named in a previous version of the estate plan. It is not enough to feel hurt or confused. There must be a legitimate legal interest and a valid reason to move forward. The Real Reasons Wills Are Contested Courts do not overturn wills simply because someone disagrees with the outcome. They look for specific legal issues tied to how the will was created. One common reason is a lack of capacity. This refers to whether the person understood what they were signing at the time. They must have been aware of their assets, the people in their life, and the nature of the decisions they were making. Another major reason is undue influence. This occurs when someone pressures or manipulates the person creating the will, often resulting in decisions that raise questions. Fraud or forgery can also lead to a challenge, though these cases are less common. In those situations, the concern is that the document was altered or misrepresented. There are also cases where the will was not executed properly. Each state has strict requirements for signing and witnessing a will, and if those steps are not followed, the document may be vulnerable even if the intentions were clear. Among all of these, undue influence often creates the most tension within families. When Influence Becomes a Problem Helping a loved one is not unusual. In many families, it is necessary and done with the best intentions. The concern arises when that help slowly turns into control. One person may become increasingly involved in daily care, appointments, or finances. Over time, other family members may step back. Then changes to the will appear, often heavily favoring the person who has been most involved. This does not automatically mean something improper occurred, but it does raise concerns. Courts often look for patterns in these situations. Was the individual isolated from others? Did one person control access or information? Were significant changes made later in life? These are the types of questions that can lead to a will contest. These situations are often closely tied to another important issue, which is capacity. When Capacity Is Questioned Capacity focuses on whether the person truly understood their decisions at the time the will was signed. This often becomes an issue when someone is dealing with dementia, illness, or the effects of medication. Timing plays a critical role. A will signed during a period of clarity may be valid, while one signed during confusion may be challenged. Courts will typically rely on medical records, witness testimony, and the circumstances surrounding the signing to evaluate these claims. Capacity and undue influence frequently overlap. A vulnerable person may also be more susceptible to pressure, which makes these cases more complex. When Technical Mistakes Lead to Disputes Sometimes the issue is not what the will says, but how it was created. Each state has specific rules for signing and witnessing a will. If those rules are not followed exactly, the document may not hold up in court. This is where do-it-yourself planning can create real risk. Online templates or handwritten documents may seem convenient, but they do not always account for state-specific requirements. I have seen families discover a document after a loved one passes away and believe it reflects their wishes. But if it was not properly executed, it can lead to confusion, disagreement, and ultimately a legal challenge. Even small technical mistakes can have significant consequences. What Happens When a Will Is Contested When a will is contested, the probate process becomes even more complex and often slows down significantly. Before the estate can move forward, the court must resolve the dispute. This may involve reviewing documents, hearing testimony, and evaluating evidence from both sides. The outcome can vary. The court may uphold the will, reject it, recognize a prior version, or treat the estate as if no valid will exists. During this time, distributions are often delayed, leaving families waiting for answers and resolution. The Real Cost of a Contested Will A contested will can take a significant toll on a family. Legal fees can quickly reduce the value of the estate, and the process can stretch over months or longer. But the most lasting impact is often emotional. I have seen families stop speaking to one another. I have seen trust break down in ways that cannot easily be repaired. What begins as a legal issue can quickly become something deeply personal. That is why prevention matters so much. How to Reduce the Risk of a Will Contest The most effective way to deal with a will contest is to reduce the chances of one happening in the first place. It starts with a clear and up-to-date estate plan. Your documents should reflect your current wishes and relationships. If you are making decisions that may come as a surprise, it can be helpful to explain your reasoning. Working with experienced professionals helps ensure that your will is properly executed and legally sound. In some situations, documenting capacity at the time of signing can provide additional reassurance. Open communication also plays a key role. When family members understand the reasoning behind decisions, they are less likely to question them later. No plan can eliminate every risk, but strong planning can significantly reduce it. Clarity Prevents Conflict A contested will can change everything. What should be a straightforward process can become complex, costly, and emotionally overwhelming. Yet in many cases, these situations are not caused by unusual legal issues. They are the result of uncertainty, lack of communication, or circumstances that raise questions. At Bellomo & Associates, we believe the goal is not perfection, but rather clarity. If your will were challenged tomorrow, would your wishes be clear? Would your plan stand up to scrutiny, or leave room for doubt? Because estate planning is not just about passing on assets. It is about protecting your family from conflict when they need peace the most.
May 19, 2026
The 5 Essential Documents Every Estate Plan Should Include
If you only have a will, you may not have a complete estate plan.This is something we gently explain to families all the time. Many people believe estate planning is a single document. They think once a will is signed, everything is handled. In reality, a complete estate plan is a coordinated set of documents that protects you during life and after death.At Bellomo & Associates, we regularly meet families who assumed they were covered, only to discover important gaps. Often, they do not realize those gaps exist until a medical emergency or loss forces the issue.Estate planning protects against two major risks: death and incapacity. If even one key document is missing, your family could face court involvement, delays, and unnecessary stress.Lets walk through the five essential documents every adult should have and how they work together to create real protection.Why Estate Planning Is More Than Just a WillA common belief is, I have a will, so Im covered. A will is important, but it does not address everything.Estate planning must prepare for two realities: What happens when you pass away What happens if you become unable to make decisions We have seen situations where a parent suffers a sudden stroke and cannot manage finances. There is no power of attorney in place. The family assumes they can step in, but banks refuse access without proper legal authority. The only option becomes a court-supervised guardianship proceeding. That process takes time, costs money, and adds stress during an already emotional season.Estate planning is not just about distributing property. It is about maintaining control and ensuring continuity. The right documents allow trusted individuals to step in seamlessly when needed.Here are the essential documents that make that possible.1. Last Will and TestamentA last will and testament directs how your assets are distributed after your death. It allows you to: Name an executor Appoint guardians for minor children Direct how property should be distributed A will matters because it prevents state law from deciding for you. If you pass away without one, the state determines who inherits your property. That outcome may not reflect your wishes.For parents, naming guardians is especially important. Many couples assume family members would simply step in. Without written instructions, the court must make that decision. Naming guardians in your will ensures your voice is heard even when you are not here to speak.2. Revocable Living TrustA revocable living trust holds assets during your lifetime and directs their distribution after your death. It can also protect during incapacity.One of the primary benefits of a revocable living trust is avoiding probate for assets properly titled in the trust. Probate can take months or longer and becomes part of the public record. A trust helps maintain privacy and often allows assets to be distributed more efficiently.Trusts can be especially helpful for: Blended families Families with property in multiple states Individuals who want structured distributions over time For example, if you own property in two different states, your family may otherwise face separate probate proceedings in each state. Proper trust planning can simplify that process.Not everyone needs a trust, but when it fits, it can provide significant clarity and protection. 3. Durable Financial Power of AttorneyA durable financial power of attorney allows you to name someone to manage your financial affairs if you become unable to do so.This document typically covers: Paying bills Managing investments Accessing bank accounts Handling real estate transactions Without this document, your loved ones may need to seek a court appointment to manage your finances. That process can be public, expensive, and slow.We have seen families struggle with frozen accounts and unpaid bills simply because this document was missing. A properly drafted power of attorney prevents that disruption and keeps life moving forward. 4. Health Care Power of AttorneyA health care power of attorney allows you to designate someone to make medical decisions on your behalf if you cannot communicate.Medical emergencies do not give advance notice. This document ensures that someone you trust has clear authority to speak with doctors and make decisions consistent with your wishes.Without it, medical providers may rely on default state laws to determine who can act. Family members may disagree about treatment decisions, which can delay care and create tension.Choosing your decision-maker ahead of time brings clarity during moments that are already emotionally heavy. 5. Living Will or Advance DirectiveA living will provides written instructions about life-sustaining treatment and end-of-life care.Even with a health care power of attorney in place, loved ones may struggle with difficult decisions. A living will guides them. It clarifies your preferences regarding resuscitation, life support, and other critical treatments.Without written instructions, families are often left relying on memory. One sibling recalls one conversation. Another remembers something different. Disagreements can intensify during grief.Putting your wishes in writing is a gift of clarity and peace to the people you love.How These Five Documents Work TogetherEach document serves a distinct purpose, but they are strongest when coordinated. A will directs distribution after death A trust may streamline or avoid probate A financial power of attorney protects you during incapacity A health care power of attorney addresses medical decisions A living will clarifies treatment preferences Together, they create a comprehensive plan that protects both you and your family.We do not treat these documents as isolated pieces of paper. We design plans that work together seamlessly and reflect your goals.Common Estate Planning Mistakes to AvoidEven when people create documents, certain mistakes weaken their plan: Failing to update documents after marriage, divorce, or birth Creating a trust but never funding it Ignoring beneficiary designations on retirement accounts Naming decision-makers without backups Believing estate planning only matters later in life Life changes. Laws change. Your plan should evolve as well. Is Your Estate Plan Complete?Take a moment to reflect: Do you have documents that address both death and incapacity? Have you named backup decision-makers? Have you reviewed your plan in the past three to five years? Do your beneficiary designations match your wishes? If you are unsure about any of these questions, your plan may need attention. Estate Planning Is About ProtectionThese five documents are not just legal forms. They are tools that protect your family from uncertainty, delay, and unnecessary stress.A will alone is not enough.A trust alone is not enough.A power of attorney alone is not enough.Each protects against a different risk. Together, they provide clarity, continuity, and peace of mind.If something happened tomorrow, would your family know exactly what to do?
Apr 10, 2026
Estate Planning Basics
Many people come into our office wanting to know what planning they need. We often are able to demonstrate very quickly that it is impossible for someone to know exactly what another person needs, because each person is different, and everybodys goals are different. Although I cannot precisely tell every person what they need without knowing the details, there are certainly some basics that everybody should have in place regardless of their age or their wealth.A Last Will and TestamentA Last Will and Testament will allow an individual to determine where the assets will go upon their death. This document will specifically govern assets that are in the persons name but not jointly owned assets or assets that have a designated beneficiary.Financial Durable Power of AttorneyThis document will allow another individual to make financial decisions for you if you are unable to manage your own financial affairs. Unable can be because of unconsciousness, being out of the country, or just simply not being able to make those decisions. This will allow your bills to be paid while you are incapacitated, and allow your life to continue, even if you are not able to make decisions for yourself. The key to this document is having it in place before losing capacity because the alternative of guardianship is certainly not a perfect choice.A Health Care Power of AttorneyA healthcare power of attorney will allow you to have your medical decisions made by another individual in the event that you are not able to make them for yourself. If this document has a living will embedded in it, also called an advanced health care directive, that would also allow someone to know what your wishes are at the end of life or end-stage medical condition so that your wishes are carried out in that instance. The FINANCIAL POWER and Medical Power of Attorney do not have to be the same person or people and often people tend to have them be different because one person is better with finances and maybe the other is better with medical decisions.Beneficiary designationsMany people forget about the fact that there are assets and accounts that require the designation of a beneficiary. For example, life insurance, 401(k)s, IRAs, annuities, etc. will allow you to name a beneficiary right on the contract or policy. Whoever you name as the beneficiary will receive those items outright. It is essential that everybody check their beneficiary designations and make sure that it is consistent with their other estate planning. For example, if you name everything to one person in your will but your beneficiary designations name someone else when you die, everything would be going to who is named as the beneficiary designations, and nothing will be going pursuant to the Will. This is often a case or a situation where people dont understand the implications, and it is imperative that you check your beneficiary designations often to make sure that they are up to date with the rest of your planning.Guardianship designationIf you have a child who is under the age of 18, it is crucial and essential that you name who you want to care for that child in the event that you were to pass. The guardian of your child will physically raise and take care of your child until they reach the age of 18. It is important not only to name that person but to name a backup, in case something happens to the person initially named. Without naming your preference in the document, it can certainly get ugly and may lead to a fight in a courtroom with a judge that is totally unnecessary and avoidable.If you have these basics taken care of and make sure that everything is consistent with your wishes, your bases will be covered, regardless of your age, health status, or wealth. To the extent that you do have significant wealth or that there are complications to your situation, then certainly there are other estate planning techniques that may be used. But as a basic rule of thumb, these are the essentials that everybody needs, regardless of age and wealth.If you would like to learn more about the basics or the essentials of estate planning, please give our office a call at (717) 208-2899 to learn more.
Aug 17, 2023
Why Arent More Older Adults Planning for Long-Term Care?
At Bellomo & Associates, one of the biggest surprises we see in families is just how unprepared many older adults are for the reality of long-term care. Its understandable. Most of us want to believe we wont need it, or that Medicare will take care of everything. But the truth is much more complicated. Research shows that about 1 in 7 adults over the age of 65 will eventually need help with daily activities like bathing, dressing, or eating. This kind of support is what we call long-term care. And yet, too many people underestimate their chances of needing it, or assume its something to worry about later. Unfortunately, waiting often leaves families caught off guard when a crisis hits. Common Misconceptions About Long-Term CareRecent surveys show just how unprepared many adults are:Less than half of adults over 50 believe theyll ever need long-term care.Only about one-quarter have named a potential caregiver or put a medical power of attorney in place.Just 11% have purchased long-term care insurance.Nearly two-thirds mistakenly believe that Medicare will pay for permanent nursing home care.That last one is especially concerning. Medicare was never designed to cover long-term custodial care. It may help with short-term skilled nursing care after a hospital stay, but it will not cover permanent nursing home costs. Medicaid, on the other hand, can cover these expensesbut only if you meet very strict income and asset requirements. Without careful planning, families often find themselves needing to spend down what theyve worked so hard to save to qualify. Why Early Planning MattersWaiting until a health crisis forces the issue leaves families scrambling emotionally, legally, and financially. Planning, on the other hand, gives you options and peace of mind. With the right strategies in place, you can:Protect your home and savings from being lost to care costsQualify for Medicaid without last-minute spend down stressPut the right powers of attorney in place so trusted loved ones can step in if neededHave open, guided conversations with your family about your wishes before a crisis occursHow We Can HelpWe understand how difficult it is to picture needing help with daily life after being independent for so long. Thats why we approach long-term care planning with compassion, honesty, and realistic solutions. Whether its reviewing your options for Medicaid eligibility, setting up powers of attorney, or exploring long-term care insurance, well walk beside you every step of the way. Long-term care planning is one of those things that feels easy to put offuntil its too late. The earlier you prepare, the more control youll have over your care, your finances, and your familys future.
Oct 31, 2025
I Am Named As An Executor In A Will. Is That A Good Thing?
I often find in my estate planning and elder law practice that every child or family member wants to be named as an executor in their loved one's documents.However, I often find that nobody actually knows what that means and has absolutely no idea how much work it entails. I think people believe it is a rite of passage or an honor to be named, which it can be, but it also comes with a lot of work and some significant responsibility.The person who is named as the executor in a Last Will and Testament is a fiduciary and is held to a higher standard than an ordinary individual or beneficiary. If the executor does not carry out his or her duties and obligations appropriately, if the appropriate taxes are not paid or if the beneficiarys interests are not protected like they were supposed to be the executor can be held personally liable in the Commonwealth of Pennsylvania.Furthermore, it is imperative that the person who is being named as the executor is a very organized individual, who can handle balancing and managing a checkbook and also multi-tasking. The relationship of a person to another individual does not make them the right choice or the right candidate for the position.If you are named, my recommendation would be to start understanding now what that entails, and what you will be asked to do. If you are not comfortable serving, I would advise that you let the person know so that they can make alternate or contingent plans in their estate planning.If you find yourself named as an executor, I would highly recommend that you seek advice from an attorney who has lots of experience in this area. Oftentimes, people are lulled into thinking that acting as the executor and opening the estate is a very simple process and that an attorney is not needed.While I agree that the original meeting at the courthouse and getting the grant of Letters Testamentary are not difficult things, that is merely the first step, from that point forward there is a myriad of requirements of notices to not only beneficiaries and heirs but also creditors. There is a Pennsylvania inheritance tax return required to be filed as well as potentially a fiduciary income tax return. Being named is only the first step, and that is by far the easiest.Since an executor is a fiduciary and is held to a higher standard and can be held personally liable to creditors and to other beneficiaries, I highly recommend seeking the advice of counsel. Not any counsel, but counsel who is familiar with the inner workings of the estate administration process in Pennsylvania, including but not limited to, the priority statutes, understanding who gets paid first, second, third, etc., which can undoubtedly cause issues if the estate does not have a lot of money or happens to be an insolvent estate.While it can be an honor to be named as an executor, we urge you and encourage you to understand all the expectations that come with it and what you can do ahead of time to be prepared. If you find yourself named, plan to seek the counsel of a qualified individual to walk you through the process so that you do not have to worry about any potential liability or any potential pitfalls of which you may be unaware.If you would like to learn more about being an executor in the Commonwealth of Pennsylvania, please give our office a call at 717-208-4546 or come to one of our upcoming workshops to learn more.
Sep 15, 2023
The Bellomo Name
Growing up Italian is something I am very proud of. I love my family with all of my heart. The last name Bellomo means the world to me. I can see my Grandpa Bellomo in my head like it was yesterday saying our last name Bellomo like it was worth a million dollars. That sense of pride has certainly continued down through my parents as well. My parents gave me this poem when I was just a kid. I cherished that plaque and still keep it in a safe place these many years later. I hope youll agree that this gift is among your most valuable.Your Family Name by Nelle A. WilliamsYou got it from your fatherIt was all he had to giveSo its yours to use and cherishFor as long as you may liveIf you lost the watch he gave youIt can always be replacedBut a black mark on your nameCan never be erasedIt was clean the day you took itAnd a worthy name to bearWhen he got it from his fatherThere was no dishonor thereSo make sure you guard it wiselyAfter all is said and doneYoull be glad the name is spotlessWhen you give it to your sonI cherish the plaque with this poem. Thank you, Mom and Dad, for sharing this with me. I am proud of the Bellomo name and what it means.
Mar 31, 2023
Having a talk with your parents about their long term living situation
No, we are not talking about the birds and the bees but rather talking about having a conversation with your parents about what their wishes are in regard to their long-term care living situation. I find in my practice that oftentimes parents will think a lot about where theyre going to live as they age and what type of situation they would prefer to be in. Unfortunately, many parents do not feel comfortable having the conversation with their children ahead of time for many reasons. I also find that the opposite is equally true: the kids often wonder what will happen but dont feel that its right to bring it up and dont want to push mom and dad into having to discuss and make decisions about that determination.I cannot begin to tell you how important it is to discuss these situations early and often. Both parties are hesitant, but it is better for everybody involved to know what Mom and Dad think and what their wishes and hopes are for their living situation at the end of the day. To the extent that mom and dad want to remain home, there are plenty of things that can be done including modifications to the home or purchase of a new home to make that happen. To the extent that they want to go to an assisted living community and live independently now or to a continuing care retirement community, there are many tours and interviews to take with mom and dad to see where they feel the most comfortable. The options are plentiful and regardless of what mom and dad are hoping for, it is typically pretty straightforward in finding an option. A friend of mine recently told me that she does not want to have the conversation because she is afraid that Mom and dad are expecting they will be able to move into her house with her and her family. My response to her was wouldnt you rather know that now and have the conversation now with them rather than wait until they need assistance and cause not only them extra stress but you and your family extra stress? She definitely came around after about a 25-minute conversation explaining that it wasnt about her and her family but rather about her parents wishes. Just because they wanted to do that doesnt mean that it would work for her and her family nor does it mean that that is what has to happen, but having the conversation will at least open up the dialogue and allow her to express her concerns and reasons why she doesnt think that would happen or be able to work and look for another alternative. Ultimately, she did have the conversation with her family, which is not what they were looking for or expecting, so it was nothing more than a miscommunication. I urge adult children to have a conversation with their parents about aging and their wishes sooner rather than later. This conversation will avoid lots of heartache and misunderstanding later and allow for plenty of time to plan for the future. If you are interested in learning more about long-term care living, please call our office at 717-844-9218
May 04, 2023
Common Estate Planning Mistakes and How to Avoid Them
Most people think estate planning mistakes are complicated legal failures. They picture technical errors, courtroom battles, or confusing loopholes.That is not what usually happens.At Bellomo & Associates, I can tell you the biggest problems we see are much simpler than that. They come from everyday oversights. A document that was never created. A beneficiary that was never updated. A conversation that never happened.And those small gaps are the ones that create the most stress, conflict, and expense for families later.The good news is this. You do not need a complicated plan to avoid the biggest mistakes. You need the right foundation, regular updates, and a plan that works together as a whole.Lets walk through the most common estate planning mistakes and how to avoid them. The Biggest Mistake: Not Having a Plan at AllThis is still the most common issue. More than half of Americans do not have a will, and many believe they do not have enough to justify planning.I have heard that countless times. We do not have a big estate, or We will get to it late, or even, It is not urgent.But here is the reality: if you do not create a plan, the state will create one for you.That means the court may decide who receives your assets, who manages your affairs, and how everything is handled. Your family is left navigating a process they were never prepared for, often during an already difficult time.Avoiding this mistake does not require perfection. It simply requires getting started. A will or trust A financial power of attorney A healthcare directive A review of your beneficiary designations You do not have to solve everything at once. You just need to take the first step.Mistake #2: Thinking Estate Planning Is Only for the WealthyThis is one of the most common myths I hear.People assume estate planning is only for those with significant wealth. But estate planning is not really about money. It is about control. If you have children, a home, a retirement account, or even preferences about your medical care, you already have decisions to make. Estate planning answers important questions: Who makes decisions if you cannot Who receives your accounts Who cares for your children How your family avoids unnecessary stress It is not about how much you have. It is about protecting what matters most. Mistake #3: Believing Your Will Controls EverythingThis one surprises a lot of people. A will does not control all of your assets. Certain accounts pass based on beneficiary designations. That includes retirement accounts, life insurance policies, and some bank accounts. Whoever is listed on those forms receives the asset, regardless of what your will says. I have seen situations where someone updated their will but forgot to update their beneficiaries. The result was not what they intended. To avoid this mistake: Review beneficiaries on retirement accounts and life insurance Check payable-on-death and transfer-on-death accounts Make sure everything aligns with your overall plan Your documents should work together, not against each other. Mistake #4: Failing to Update Your Estate PlanCreating a plan is only the beginning. Life changes, and your plan should change with it. I often tell families that an outdated plan can be just as risky as having no plan at all. Think about how much can change over time. Marriage, divorce, births, deaths, new assets, or even moving to a new state can all affect your plan. If your documents do not reflect your current life, they may not produce the outcome you want. To stay on track: Review your plan every three to five years Update it after major life events Estate planning is not something you do once and forget. It is something you maintain over time. Mistake #5: Ignoring Incapacity PlanningMost people think estate planning only applies after death. But some of the most important decisions happen while you are still living. If you become unable to make decisions due to illness or injury, who steps in to help? Without the right documents, your family may need to go to court just to gain the authority to manage your finances or make medical decisions. That process can be stressful, time-consuming, and expensive. To avoid that situation, make sure you have: A durable financial power of attorney A healthcare power of attorney A living will or advance directive These documents give your family clarity when they need it most. Mistake #6: Choosing the Wrong Person to HelpChoosing who will act on your behalf is one of the most important decisions you will make. Many people choose based on emotion or family expectations. But these roles require more than trust. They require responsibility, organization, and the ability to handle difficult situations. The wrong choice can lead to delays, confusion, and even conflict. To make a thoughtful decision: Choose someone capable and dependable Have a conversation with them ahead of time Name backup options The right person can make everything run smoothly. The wrong person can make an already difficult time even harder. Mistake #7: Leaving Assets Directly to a Loved One with Special NeedsThis is one of the most well-intentioned mistakes I see. Families want to provide for a loved one with special needs, so they leave assets directly to them. But doing so can unintentionally affect eligibility for important benefits. What was meant to help can create complications. With proper planning, there are better options. A special needs trust can allow you to provide support without disrupting those benefits. If this applies to your family, it is important to plan carefully and not make assumptions. Mistake #8: Forgetting About Digital AssetsYour estate is no longer just physical. It includes a growing number of digital assets. Email accounts Online banking Photos and cloud storage Cryptocurrency Social media accounts Without a plan, your family may not be able to access these accounts. To stay ahead of this: Create an inventory of your digital assets Store access information securely Use tools like legacy contacts when available This is one of the most overlooked areas of planning today, but it is becoming more important every year. Mistake #9: Overlooking Retirement Account RulesRetirement accounts often make up a large portion of a persons assets, but they come with unique rules. Naming a beneficiary is important, but it is not always enough. Recent changes have affected how these accounts are distributed, especially for non-spouse beneficiaries. Without proper planning, families may face unnecessary taxes or complications. To avoid this: Coordinate retirement accounts with your overall plan Be cautious when naming minors or trusts Seek guidance when needed These decisions should not be made in isolation. They should be part of a larger strategy. The Real Problem Is Not Complexity, It Is CoordinationWhen you step back and look at these mistakes, a pattern becomes clear. Most of them are preventable. They are not caused by complicated legal strategies. They come from delay, outdated documents, and a lack of coordination. At Bellomo & Associates, we focus on helping families bring everything together in a way that is clear, organized, and aligned with their goals. A strong estate plan does not need to feel overwhelming. It just needs to be complete, updated, and working as one. If you are not sure where you stand, that is okay. Start by reviewing what you have. Identify what might be missing or outdated. Then take the next step. Because in the end, estate planning is not about paperwork. It is about making life easier for the people you care about most.
May 08, 2026
Would Your Estate Plan Hold Up in a Crisis?
Most people think of estate planning as something that matters after death. You sign a will, create a trust, name the people you want to make decisions, and hopefully walk away feeling like you have taken care of your family. But one of the things I have learned over the years is that the true test of an estate plan often comes much sooner. What happens if you are suddenly hospitalized and cannot manage your finances? What if your spouse or adult child needs to speak with doctors on your behalf? What if your trustee knows they are supposed to help, but has no idea where your important information is located? These are not situations any of us enjoy imagining, but they are exactly why good estate planning matters. At Bellomo & Associates, we believe estate planning is about much more than preparing for what happens someday. It is about giving the people you love clarity, confidence, and direction when life does not go according to plan. A Strong Estate Plan Plans for Incapacity, Not Just DeathOne of the biggest misconceptions about estate planning is that it is primarily about what happens after someone dies. In reality, some of the most stressful situations families face happen while someone is still very much alive. A stroke, serious accident, dementia diagnosis, or unexpected illness can quickly leave a family wondering who is allowed to pay bills, manage property, speak with financial institutions, communicate with doctors, or make healthcare decisions. And this is where we often see families surprised. Being someones spouse, son, daughter, or sibling does not necessarily give you automatic legal authority to step in and handle everything. Imagine a daughter whose mother has suffered a serious stroke. She knows her mom incredibly well. She knows what bills need to be paid. She knows where she banks. She knows what her mother would probably want. But knowing what needs to happen and having the legal authority to make it happen are two very different things. A properly prepared durable power of attorney and appropriate healthcare documents can help close that gap. They allow the people you trust to step in when needed, rather than forcing your family to figure everything out during an already frightening time. That is what good planning is meant to do. Choosing the Right People MattersEstate planning documents are only as effective as the people chosen to carry them out. Depending on your plan, you may need to select someone to serve as your financial agent, healthcare decision-maker, executor, trustee, successor trustee, or guardian for minor children. Most people begin with a simple question: Who do I trust the most? That absolutely matters. But I often encourage families to go one step further and ask, Who could realistically handle this responsibility during a difficult time? The person you love the most may not always be the person who is best equipped to manage finances, communicate with family members, work with attorneys and accountants, keep records, or make difficult decisions under pressure. You want people who care about you, but you also want people who can carry out the job. It is equally important to name backup decision-makers. Life changes. Someone willing and able to serve today may not be able to do so years from now. A strong estate plan thinks through those possibilities before they become a crisis. Give Your Decision-Makers the Information They NeedNaming someone in a legal document is an important first step, but it should not be the last one. Imagine learning that one of your parents is hospitalized and you are now responsible for helping manage their affairs. You know you are the person they selected. The problem is, you do not know where they bank. You cannot find the insurance information. You are not sure where the original estate planning documents are located. You do not even know which attorney helped prepare them. That creates unnecessary stress at the exact moment your family needs less of it. The people you select do not necessarily need every password and account number today. But they should know where important information can be found, who they should contact, and what responsibilities they may someday be asked to handle. A legal document gives someone authority. Organization gives them a roadmap. Your family deserves both. Healthcare Planning Requires More Than PaperworkHealthcare directives are an important part of any estate plan, but there is something else that can make those documents much more powerful: a conversation. The person you select to make healthcare decisions may someday be asked to make choices under incredibly emotional circumstances. Think about the weight of that responsibility. If you have never discussed your wishes, your loved one may be left wondering, What would Mom want? or Am I making the right decision for Dad? Talking about your values ahead of time can give them tremendous peace of mind. What does quality of life mean to you? Are there circumstances or treatments you feel strongly about? Who would you want involved in important medical conversations? Are there personal, religious, or family values you want considered? The legal document may give someone permission to make a decision. The conversation helps them understand the decision you would have wanted. Make Sure Your Trust Is Actually Connected to Your AssetsCreating a trust can be an important part of an estate plan, but signing the document does not always mean the work is finished. Depending on your plan, assets may need to be retitled, assigned, or otherwise coordinated with the trust. This is an area where families can run into trouble years later. A couple creates a trust and leaves the attorneys office feeling relieved. Then life keeps moving. They buy another property. They open a new investment account. They change banks. Years later, something happens, and their family discovers that some of those assets were never properly connected to the trust. Documents alone do not move assets. Follow-through matters. That is why trust funding and ongoing asset coordination should be viewed as part of the estate planning process, not an afterthought. Review Your Beneficiary DesignationsBeneficiary designations are another area that families sometimes overlook. Retirement accounts, life insurance policies, annuities, and certain financial accounts may pass directly to the beneficiary named on the account. That means the beneficiary form can sometimes control where an asset goes, even if your will or trust says something different. Imagine someone who divorces, remarries, and carefully updates an estate plan to reflect a new chapter of life. Everything looks right. But one old retirement account still lists an outdated beneficiary. That one piece of paper can create a result nobody intended. A strong estate plan should look at the whole picture, including wills, trusts, beneficiary designations, account ownership, insurance policies, and real estate. Ideally, every part of the plan should tell the same story. Special Family Circumstances Require More ThoughtFamilies are wonderfully unique, and estate plans should reflect that. Blended families, minor children, beneficiaries with disabilities, family businesses, financially vulnerable loved ones, property in multiple states, or complicated family relationships may require additional planning. For example, leaving money directly to a loved one who receives certain means-tested public benefits could create unintended consequences. In situations like these, the question is not simply, Who should inherit? The better question is, What is the best way for this person to receive what I want to leave them? That is a very different conversation. Good estate planning takes the time to understand the people involved, not simply the assets on a spreadsheet. Keep Your Estate Plan Organized and CurrentEven the best estate plan becomes harder to use if nobody can find it. Your family should not have to become detectives while grieving, sitting in a hospital, or trying to manage an emergency. Important documents, financial information, insurance records, professional contacts, and property information should be organized so the appropriate people can locate them when needed. Your plan should also grow and change with you. Marriage, divorce, births, deaths, moves, retirement, business changes, health concerns, major financial changes, and changing family relationships can all affect your estate plan. A plan can still be legally valid while no longer reflecting the life you are actually living. At Bellomo & Associates, we often remind families that estate planning is not something you finish once and forget about. It is a process of making sure your plan continues to protect the people you love as life changes. Would Your Estate Plan Work Tomorrow?A well-prepared estate plan cannot eliminate every difficult moment. It cannot predict every illness, prevent every disagreement, or guarantee that life will unfold exactly as we hope. What it can do is create clarity. Someone has the authority to act if you become incapacitated. Your healthcare wishes are documented and understood. Your assets work with your plan. Your beneficiary designations reflect your current wishes. The people you selected understand their roles. Your family knows where to turn. And sometimes, that clarity is one of the greatest gifts you can give the people you love. So instead of asking only, Do I have an estate plan? ask yourself a slightly different question: If something unexpected happened tomorrow, would the people I trust know what to do, where to look, and whether they had the authority to act? If you are not completely sure of the answer, that does not mean you have failed. It simply means there may be an opportunity to make your plan stronger today, while you have the time and ability to do it thoughtfully.
Sep 25, 2026
Comparing Life Care Planning to Traditional Elder Law
This year, we are getting the word out there about the Life Care Planning we offer that involves a licensed social worker to act as the Client Care Advocate. A question that we keep getting is what is What is the difference between Life Care Planning and Elder Law and why did you make the change? The way that I explain it is that a traditional elder law firm prepares documents for an individual and then either waits until the client passes or until they need to go to a nursing home and will qualify them for public benefits.A life care planning firm is a more holistic approach to providing care. Our licensed social worker, Meg Motter, works with families to assist in figuring out ways to keep their loved ones home and how to receive care in a home or in a less restrictive environment than a nursing home. A licensed social worker will be able to provide different cognitive assessments and evaluate safety and necessity of levels of care, unlike an attorney. The elder care coordinator allows the firm to provide a more comprehensive approach, separate from just estate planning documents or qualification for Medicaid. The care coordinator allows the firm to provide information and advice that was not otherwise available to the firm prior to becoming a life care planning model firm.We are ecstatic to have Meg Motter onboard as our elder care coordinator and we look forward to assisting you and your family in the future.Please feel free to give us a call if you have any questions or comments at 717-845-5390.
Jan 20, 2023
Potential Decrease in Federal Gift and Estate Tax Exemption, Did it Pass and Does it Impact You?
A hot topic among our clients is the proposed amendment to the Federal Lifetime Gift & Estate Tax Exclusion and how it may affect their current estate plan. At this point Congress did not pass the proposed amendment to the law that was to go into effect January 1, 2022. And there does not seem to be a lot of talk of bringing this to the forefront again for a vote anytime soon. The current law doesnt reduce the exemption until January 1, 2026, when it would revert to $5 million. The exemption is a lifetime exemption per person and applies to gifts you make during your life or distributions to your beneficiaries after your death. Any amounts gifted or passed through your estate in excess of the deduction amount will be subject to either federal gift tax or federal estate tax. This change will only impact you if your net worth is in excess of $5 million (adjusted for inflation). If you are like many people, me included, who can only dream of having $5 million dollars of assets in your lifetime then the reduction of the exemption on January 1, 2026, or before, will have no effect on you or your planning. However, if you do have significant assets you may want to consult a qualified estate planning attorney to determine if you can make additional gifts before the law rolls the exemption amount back to $5 million in approximately 4 years. The attorney will also be able to advise you if establishing and funding a grantor trust prior to the exemption being reduced would benefit you and help to reduce any federal gift or estate taxes. Please keep in mind that this law and any changes applies to federal gift and estate taxes and has no effect on the assets or value of the assets subject to Pennsylvania inheritance tax. Inheritance tax in Pennsylvania is separate and apart from any federal laws and currently inheritance tax is assessed on almost every asset you own with the exception of life insurance. For questions on if the proposed changes in the federal gift and estate tax laws in early 2026 will negatively impact you or your estate planning or questions on Pennsylvania inheritance tax, please consult a qualified estate planning attorney for a review of your estate plan. We would be happy to schedule a time to speak with you regarding your individual situation. Please feel free to give us a call if you have any questions or comments at 717-845-5390.
Dec 30, 2022
Why Its Imperative To Have Advance Healthcare Directives
An advance healthcare directive is a healthcare power of attorney and living will in a single document. The document will provide instruction on who will make the medical decisions for another individual but also what the principal wants in the event that they become the end of life or have an end-stage medical condition. Many people who come into our office tell us that their family knows what they want and that they can take care of it. I cannot stress or urge enough to not fall into this thought pattern. End-of-life decisions are very unique to each and every one of us. It is very easy to tell your family member what your wishes are but its very different for a family member to have to verbalize to a doctor to withdraw treatment and see their loved one pass within minutes. There is no more emotional decision that I have ever experienced in my practice and wish that stress and emotion on nobody.Oftentimes, people believe that there is a right or wrong answer to the question of whether you want heroic and lifesaving measures if there is no hope. There are so many things that go into this decision such as our personal lives and goals and beliefs as well as religion. I certainly do not believe that I have the right answer as to what everybody should do but I do know that whatever the individual wants is the right answer for that person, and therefore, that should be what is in writing and that should be what we follow. Families generally have no issues or fighting as long as they know exactly what the individual wanted and know that they are carrying out the wishes of that individual. The fighting and stress start to set in when it is not clear what the person wanted and family members start jockeying for position and who knew exactly what the individual wanted. Please take the stress out of end-of-life decisions for your family and not allow those decisions to be the center of debate and fights in a hospital. Take the time to put your wishes in writing in an advance healthcare directive so that everybody knows exactly what you want. This will save your family lots of heartaches but, most importantly, will give you peace of mind knowing that your wishes will be followed.If we can be of any assistance or answer any questions while you make decisions about long-term care, please give us a call at 717-844-9218.
May 04, 2023
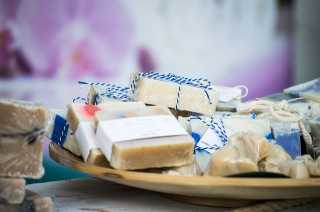
Adventures in Soap Making Part 1
Is anyone else like me, you see a craft and you just have to try it? No? Hmm, well I guess Im in the minority. Over the years I have explored many types of crafts from the traditionally counted cross stitch and knitting to the slightly more unusual like basket weaving, stained glass, and hot glass to the downright out of the mainstream like chain mail (I made jewelry not armor but the same process just on a smaller scale). My latest endeavor is soap making. And me being me I didnt start with the traditional melt-and-pour soap that you can get in kits at the craft store. Oh no, I jumped directly into making cold-process soap! For those that may not know, I didnt until I started this adventure, that much of what we use today is not, in fact, soap. I know, it blew my mind too when I came across that fact. True soap is a mixture of fat or oil an alkali (usually sodium hydroxide commonly called lye) and water. The chemical reaction between these items is called saponification which results in soap. Soap made in this manner must sit, or cure, for a few weeks to allow excess water to evaporate and make a harder bar. Only soap made in this way can be labeled as soap. Check your labels, if it doesnt specifically say soap but instead is called a cleansing bar, a body bar, a beauty bar, a body wash, or something else it isnt soap but a synthetic detergent product. Laundry detergent or dish soap also falls into the synthetic detergent designation. According to the FDA, there are very few true soaps on the market today. So how does true soap work if it doesnt have all the chemicals and additives of detergent products? Simply put soap has the ability to mix with the oil and dirt on your skin, trapping it and making it possible to remove the dirt layer. As a person lathers with soap, the soap latches onto the dirt and germs and rinses them away. True soap doesnt kill microbes but rinses them off the skin and down the drain. In a recent study sponsored by ABC News, numerous products were tested as to efficiency, and true soap ranked right up there with hand sanitizers and anti-bacterial soap. In fact, true soap ranked better than alcohol-based sanitizer. Plus the FDA has advised consumers not to use anti-bacterial soap because it assists in creating microbes that are increasingly immune to agents used to kill them.So now that you know what soap is, and is not, let the adventure begin! Stay tuned for Part II .
Jan 12, 2024
Stretching & Protecting Wealth
My estate planning and elder law practice have given me insights into these topics that I never thought possible. I encounter questions on a daily basis in my practice, how can an individual get the most out of retirement and how do you stretch your money and protect your wealth for future generations?I am an estate planning and elder law attorney who happens to have a Master's in Law and Taxation as well as a Certified Elder Law Attorney under the authorization of the Pennsylvania Supreme Court. However, more than any class or degree I have received, representing numerous families over the years and watching their decisions, and in some cases mistakes, has really provided me the most prevalent insight into these questions and their answers.I firmly believe it is very important to work with a financial professional to assist you during your working or earning years, as well as heading into your retirement years. Although it is possible for some people to do it alone, Im a firm believer in hiring professionals to provide assistance in their area of expertise.The small fee you will pay will be far worth it in the long run versus what you would save in the short term. Having a financial professional and a plan for retirement, not only how to get there, but also how you will live during retirement is imperative. Stretching your money during retirement is similar to when you were saving for retirement, being disciplined, and having a goal in mind.The one piece that no one ever wants to talk about is the cost of long-term care and how were going to pay for it. Although none of us really want to receive long-term care in our home or in a nursing facility, statistically it is a likely possibility that we need to consider.Long-term care in a nursing home will cost anywhere from 10,000 to $12,000 a month. And in-home care, depending on the amount of care that is being received, can cost anywhere from $17,000 to $20,000 a month. This care is often necessary and needed but if there isnt a plan in place, it can devastate a family pretty quickly and wipe out all of their savings.The most obvious way to pay for long-term care is to simply self-insure, and make certain you have enough assets or investments to cover the cost. I find this to be a very difficult proposition, not only because it is impossible to know ahead of time how much care you are going to need, but also because the cost of the care in the future is very unpredictable. I remember at the beginning of my career the cost of a nursing home was around $5,000 a month, and now it is well over $10,000 and in some cases in our area $12,000.I honestly dont think it is out of the realm to predict the cost will more than double in a short period of time. But for the people who were planning to self-insure, it was certainly a shock to them when they finally got to the point of needing it and learning that we were closer to $12,000 a month. Although this can be possible for wealthy individuals, it is not typically possible for the middle class, since they cannot accumulate enough wealth to absorb $12,000 a month in costs. The other thing to remember is that often times one spouse is the caregiver for another spouse, and when the good spouse ends up needing care himself or herself, both spouses end up in the nursing home to the tune of $25,000 a month. It would be very difficult to self-insure this kind of need.Another option is long-term care insurance. I am not licensed to sell insurance and have done numerous blogs on the topic of long-term care insurance. I am a big fan in general of insurance because I love that it could keep an individual in their own home for as long as possible. If you are looking at long-term care insurance policies, I would definitely look at a rider that will pay for in-home care.Pennsylvania has products that are hybrid policies which are life insurance policies, as well as riders that provide in-home care or nursing care. Pennsylvania also participates in the partnership plan, which will allow an individual who has a long-term care policy to exempt a number of assets equal to the amount of benefit that they have received. I am a big fan of both of these and if an individual is able to afford it, I believe it is absolutely a good investment. You certainly want to talk to an agent to determine if it is something that is possible for you and your loved one, as well as whether it is financially doable.In many cases, self-insuring or long-term care insurance is not an option, for a myriad of reasons, but often times we are stuck in a situation where a spouse does not have any way to pay for the long-term care, and they are reliant upon the crisis rules. Currently, in the state of Pennsylvania, the crisis rules are very favorable and will allow us to protect 100% of the assets of the spouse in the community. If you are interested in learning more about Medicaid crisis planning, please call our office at 717-844-9218, or click the link here to RSVP to our upcoming workshop to learn more about it.
May 25, 2023
Why to use Bellomo & Associates for Medicaid Instead of Doing it Yourself
When it comes to filing an application for Medicaid, the process can be quite daunting. Hiring a professional at Bellomo & Associates can relieve the pressure on everyone. To qualify for Medicaid, you must be determined both medically and financially qualified. To be medically qualified, you must be assessed by the County Area Agency on Aging and the family or Nursing Home physician. Becoming financially qualified is the tricky part. For Community Based Services your monthly income cannot exceed the yearly income limit established by Pennsylvania. For skilled Nursing Home Care, your income needs to be below the Cost of Care for that facility. In addition, you must provide statements for the previous five years for all accounts, verify all transactions over $500, and document all closed accounts. How can we help preserve excess assets if you sell the home or car, or even if you transferred or gifted assets? This is done by a process that follows the rules for Medicaid qualification. We will review the financials and determine what can be done to get Medicaid approval. A single person can have one house, one car, and up to $2,400*, or possibly as much as $8,000* depending upon their income, in all accounts. If you have resources within those limits but have transferred assets for less than Fair Market Value or given a gift over $500, you will not qualify. You are penalized and must pay privately during this period. We can help determine the penalty period and establish how the payments to skilled nursing care will be paid. A married couple can have one house and one car, and assets are divided in half with the maximum protected at $130,380* for the Community Spouse, this is the Resource Allowance. As of 2021, the Community Spouses retirement accounts are exempt from the Resource Allowance calculation. If you file for Medicaid and have assets over the established Resource Allowance, you will be denied Medicaid and will need to spend the excess over that amount, then refile. Most likely the excess will be paid to the Nursing Home or private care. This is another time way Bellomo & Associates can help protect assets and assist in obtaining financial eligibility for Medicaid.Bellomo & Associates can potentially assist in qualifying a single person that has excess assets, has previously made gifts, and perhaps even leave a legacy for their beneficiaries. We can also protect the excess assets for the Community Spouse so that the Community Spouse can maintain the same lifestyle and the family legacy. Requesting help from the team at Bellomo & Associates will ease the process and help preserve what you worked so hard to earn. If you are interested in learning more about Medicaid crisis planning, please call our office at 717-844-9218.
May 04, 2023
Is a Medicaid Asset Protection Trust Right for You?
A few years ago, a woman came into our office with worry written all over her face. Her husbands health was beginning to decline, and she couldnt stop thinking about what would happen if he needed nursing home care. They had worked hard their entire lives, saved carefully, and even paid off their home. But she had just watched a neighbor lose nearly everything to long-term care expenses, and she feared her family might face the same fate. Her concern was valid. Long-term care is one of the biggest financial risks retirees face. Depending on the type of care and your location, costs typically range from $50,000 to $100,000 per year. With the average stay lasting two to five years, those expenses can quickly drain a lifetime of savings. Studies indicate that approximately 70% of people will require some form of long-term care during retirement. The question isnt whether care will be needed, but how families can afford it without sacrificing everything they hoped to leave behind. How Medicaid WorksMedicaid can provide help with long-term care, but it comes with significant restrictions. Before you qualify, youre required to spend down almost all of your assets. Yes, youll get care, but you may have little left to pass on to your spouse or children. This is where a Medicaid Asset Protection Trust, or MAPT, can make a difference. By transferring certain assets into this kind of trust, those assets are no longer counted when Medicaid reviews your eligibility. That means you can still qualify for care while protecting your home and savings for your family. How a Medicaid Asset Protection Trust WorksTiming is everything with a MAPT. Medicaid has a look-back period, so assets need to be transferred into the trust well before care is needed. The trust must also be irrevocable, which means once assets are placed in the trust, you cant use them the same way you did before. That can sound intimidating, but with the right structure, you can still benefit from those assets in limited ways while protecting them for your heirs. MAPTs are especially useful for non-retirement assets like real estate or investments outside of IRAs. Not every family needs this tool, which is why working with an experienced estate planning attorney is so important. Other Benefits Beyond MedicaidA MAPT can provide more than just protection from long-term care costs:Estate tax planning: Todays estate tax exemption is high, but its set to decrease in the future. A MAPT can reduce potential tax exposure.Control over inheritance: Trusts let you decide how and when your heirs receive money. You can provide distributions over time, delay access until a certain age, or even ensure assets stay in the family in the event of divorce.Is It Worth the Cost?Creating a Medicaid Asset Protection Trust is an investment. Depending on the complexity, the cost often ranges from $7,000 to $12,000. For many families, the peace of mind and protection it provides far outweigh the upfront expense. The key is making sure its the right fit for your circumstances. Plan Ahead, Protect Your LegacyThe woman who came to see us decided to move forward with a Medicaid Asset Protection Trust. Years later, when her husband did require nursing care, their home and savings were safe. She had peace of mind knowing her children would still receive the inheritance she and her husband had worked so hard to build. If youre worried about how long-term care costs could affect your retirement savings and your familys future, the time to plan is now. At Bellomo & Associates, well help you explore whether a Medicaid Asset Protection Trust is the right solution for your needs. Take control of your future today. Register for a Workshop
Oct 17, 2025
Help! My Spouse Needs to go into a Nursing Home & We Can't Lose Everything!
We visited with Jeff Bellomo of Bellomo & Associates and explored what happens when a Loved One needs to go into the Nursing Home. How do you not loose everything? How do we plan for best outcomes? Jeff Bellomo, Bellomo & Associates, 717-845-5390, www.bellomoassociates.com. More questions? Ask Chris Gartman, Publisher, Seniors Blue Book of South Central PA - [email protected] #Money #Savings #NursingHomes #Safety #Finances #ElderLaw #BellomoAssociates #SeniorsBlueBook
Nov 30, 2020
Leaving a Legacy: How to Pass on More Than Just Money
When people hear the word legacy, they often think about money. Who gets what? How much is passed down? Whether assets are divided fairly. While financial planning matters, many families eventually realize something deeper. What they remember most is not the dollar amount they inherited but the values, stories, and guidance that came with it, or the absence of them. Leaving a legacy is about far more than an inheritance. It is about how you are remembered, what you stood for, and how your life continues to shape the people you love. With thoughtful planning, you can pass on more than money. You can pass on meaning. Why Legacy Planning Matters More Than Ever We are living through one of the largest transfers of wealth in history. Trillions of dollars will move from one generation to the next over the coming decades. Yet experience shows that money alone does not always create clarity or connection. In some families, it creates confusion, resentment, or distance when intentions are not clearly communicated. Legacy planning helps bridge that gap. It allows families to align financial decisions with personal values, reduce misunderstandings, and create purpose around what is being passed on. When done thoughtfully, legacy planning strengthens relationships rather than straining them. At Bellomo & Associates, we often remind families that a clear plan is one of the greatest gifts you can leave behind. It removes guesswork and gives loved ones confidence that they are honoring your wishes. Values, Not Just Valuables A true legacy includes the principles you lived by, the lessons you learned, and the example you set. It shows up in how you treated others, how you handled challenges, and what you believed mattered most. Financial assets are only one piece of the picture. Emotional inheritance often leaves a longer-lasting impact. Families tend to remember stories, traditions, and shared experiences far more vividly than account balances. Passing on values gives context to financial decisions and helps future generations understand the meaning behind the plan. When children and grandchildren understand why decisions were made, they are more likely to respect them and carry those values forward. The Power of Sharing Your Story and Values One of the most meaningful ways to leave a personal legacy is through a legacy letter, sometimes called an ethical will. This is not a legal document. It is a written message to your loved ones that shares what you want them to know. A legacy letter might include: Family history and traditions Life lessons learned through success or hardship Personal values and beliefs Hopes for children and grandchildren These letters often become treasured keepsakes. Many families say they return to them again and again, finding comfort, perspective, and guidance long after legal matters are settled. If you are unsure where to begin, start simply. Reflect on the experiences that shaped you most. Think about what you hope your family carries forward. Consider what you want them to remember about how you lived. Legacy Through Family Communication and Clarity A meaningful legacy is rarely created in silence. When families do not talk about intentions, loved ones are left to draw their own conclusions. This can lead to misunderstandings, hurt feelings, or conflict that might have been avoided. Open conversations about values and goals help everyone understand the bigger picture. These conversations do not need to include every financial detail. They are about explaining the reasoning behind decisions and setting expectations with care and respect. Families who communicate clearly often experience smoother transitions and stronger relationships. Legacy planning becomes a shared understanding rather than a source of surprise. Creating Impact Through Charitable and Community Giving For many people, legacy extends beyond family. It includes giving back to causes or communities that reflect deeply held values. Charitable giving can be built into an estate plan in many ways, including: Leaving a gift to a charity through a will or trust Naming a nonprofit as a beneficiary of a retirement account Creating a donor-advised fund Establishing scholarships or endowments Involving family members in charitable decisions can be especially powerful. It teaches generosity, responsibility, and shared purpose. In some families, giving becomes a tradition that continues long after the original gift is made. Passing Down Responsibility Alongside Wealth Many parents worry about whether their children will be prepared to handle an inheritance responsibly. Wealth passed down without guidance can feel overwhelming or even burdensome. Legacy planning creates opportunities to teach financial responsibility and intentional decision-making. This might include family meetings, shared charitable projects, or structured inheritances tied to life milestones. When responsibility is passed down alongside assets, an inheritance becomes a tool for growth rather than a source of stress. The Modern Legacy Includes Digital Life Today, legacy also includes digital life. Photos stored in the cloud, emails, social media accounts, online subscriptions, and digital wallets often hold both emotional and practical value. Without planning, families may lose access to irreplaceable memories or struggle to manage digital accounts. Taking the time to document digital assets, provide instructions, and name trusted individuals to handle them helps preserve this part of your story. Digital legacy planning ensures that your memories are protected along with your finances. Real Life Stories Show the Difference Planning Makes Some families remember a handwritten letter that guided them through difficult decisions years later. Others recall a tradition of giving that shaped how they view responsibility and community. Some families wish they had clearer communication after learning that silence left room for painful assumptions. These stories point to the same truth. Legacy is created intentionally. It is shaped by actions, conversations, and planning that happen while you are alive. When and How to Start Thinking About Your Legacy Legacy planning is not about age or net worth. It is about reflection and intention. The best time to start is when you can think clearly about what matters most to you. You do not need to do everything at once. Small steps can have a lasting impact. Write a letter. Start a conversation. Identify the values you want to pass on. Legal documents support your legacy, but they are not the starting point. The Legacy You Leave Starts Today Leaving a legacy is about more than money. It is about meaning, connection, and the influence you have on the people and causes you care about. Financial planning provides structure, but values give it purpose. The legacy you leave is shaped by how you live, what you communicate, and the choices you make today. If you want to create a legacy that reflects your values and protects your family, thoughtful planning is the first step.
May 19, 2026
What Trustees Wish They Knew Before Someone Passed
Karen thought being named trustee was simply a sign that her father trusted her most. That was before the phone calls started.Three days after the funeral, her brother wanted to know when he would receive his inheritance. Her sister questioned why the house was not already listed for sale. The bank requested paperwork Karen had never heard of before, and bills continued arriving in the mail every day. Utilities needed to stay on. Insurance policies needed attention. A CPA mentioned tax filings she did not understand.Meanwhile, Karen was still grieving the loss of her father.At Bellomo & Associates, this is one of the most common realities families face after a loved one passes away. Many people agree to serve as trustees without fully understanding what the role actually involves. They assume it will simply mean following instructions inside a trust document and distributing assets when the time comes.In reality, being a trustee often becomes a significant legal and emotional responsibility during one of the hardest seasons of a persons life.For many families, trust administration becomes stressful not because anyone had bad intentions, but because no one fully understood what would happen after death or what the trustee role would truly require.Responsibilities Begin Almost ImmediatelyOne of the biggest surprises for new trustees is how quickly responsibilities begin after someone passes away.While most family members are still processing the emotional shock of the loss, the trustee may already be responsible for protecting assets, organizing paperwork, communicating with financial institutions, and making important decisions. If there is a home involved, someone may need to: Secure the property Maintain insurance coverage Collect mail Coordinate maintenance Prevent damage or costly issues from developing Bills still need to be paid. Financial accounts may need immediate attention. Important documents have to be located quickly.For someone without a legal or financial background, the process can feel overwhelming almost overnight. Many trustees later say they had no idea how much responsibility would fall on them so quickly. A Trust Does Not Automatically Make Everything EasyAnother surprise many trustees encounter is realizing that simply having a trust does not automatically simplify everything. A trust only works properly when: Assets are titled correctly Instructions are clear Documents are updated regularly The overall plan has been maintained over time Sometimes trustees discover accounts that were never transferred into the trust. Other times, family members remember verbal promises that conflict with the written instructions inside the documents.That is often when emotions begin to rise.Even close families can experience tension after the death of a parent or loved one. Old sibling dynamics frequently resurface during inheritance conversations.One child may have spent years helping care for a parent and feel entitled to more. Another may live out of state and feel excluded from decisions. Beneficiaries may expect immediate distributions without understanding the legal, tax, or administrative steps that must happen first.Trustees often find themselves caught between grief, pressure, and responsibility all at once.Communication Matters More Than Most Families RealizeMany experienced trustees later admit they wish they had communicated more openly from the beginning.Silence can unintentionally create suspicion, even when the trustee is acting responsibly and doing everything correctly. Family members often assume delays mean something is wrong, when in reality, the trustee may simply be: Waiting for appraisals Gathering tax information Working through legal requirements Coordinating with financial institutions Following professional guidance Clear communication can prevent many problems before they start.Beneficiaries do not necessarily expect immediate answers, but they do want reassurance that progress is being made and that someone is handling the situation carefully.Trustees who provide updates, explain timelines honestly, and document important conversations often reduce misunderstandings and family conflict significantly.At Bellomo & Associates, we regularly remind families that communication after death can be just as important as the legal documents themselves.Trustees Must Follow the Trust InstructionsOne of the most emotionally difficult realities for trustees is understanding that they cannot simply do what feels fair.Their legal responsibility is to follow the trust document exactly as written.This can become especially difficult in blended families or situations where distributions are unequal.For example, a father may have verbally promised one child the family cabin for years, but the trust itself may require the property to be sold and divided equally among all beneficiaries.In moments like these, trustees often feel blamed for decisions they never made.Many trustees later wish their loved one had communicated planning decisions more clearly while everyone was still alive. Those conversations can feel uncomfortable during life, but they often prevent confusion and resentment later.The Paperwork and Administrative Work Can Be ExhaustingMany people are shocked by how much administrative work follows a death.Depending on the situation, trustees may need to: Obtain tax identification numbers Coordinate final income tax returns Manage trust income tax filings Organize property appraisals Maintain detailed financial records Work with banks and investment companies Respond to creditor claims Coordinate asset distributions Financial institutions often require extensive documentation before accounts can be transferred or accessed. Even simple tasks can take longer than expected.This is where many trustees begin worrying about making mistakes.They fear missing deadlines, mishandling distributions, or unintentionally creating conflict among beneficiaries. Some trustees delay important decisions because they feel paralyzed by the pressure of getting everything exactly right.The emotional weight of the role can become incredibly heavy.Trustees Are Not Expected to Do Everything AloneOne of the smartest things a trustee can do is seek professional guidance early.Estate planning attorneys, CPAs, financial advisors, and real estate professionals can help trustees navigate legal requirements, tax issues, and administrative responsibilities.Asking for help is not a sign of weakness. In many cases, it is exactly what protects: The trustee The beneficiaries The estate itself Family relationships Most trustees are caring family members trying to do the right thing during an emotional and unfamiliar situation. Having trusted professionals involved can provide clarity and peace of mind when the process starts feeling overwhelming.Preparation Before Death Matters More Than Most People ThinkExperienced trustees often say the same thing after everything is over:Preparation before death matters more than most families realize.When documents are organized, trusts are updated regularly, assets are titled properly, and family conversations happen ahead of time, the administration process becomes significantly smoother.Trustees benefit tremendously when they: Know where documents are located Understand the reasoning behind planning decisions Have updated information about assets Already know which professionals to contact for helpUnfortunately, many families avoid these conversations because they feel uncomfortable or assume there will always be more time later.But after someone passes away, unanswered questions often become far more stressful and emotionally charged.The most thoughtful estate plans do more than transfer money or property. They reduce confusion during one of the hardest moments a family will ever experience. They help preserve relationships, minimize conflict, and provide trustees with clarity during an already emotional time.The Trustee Role Is About More Than PaperworkAt its core, being a trustee is about far more than legal documents and financial accounts.It is about stepping into a position of responsibility during a time of grief and uncertainty. It is about balancing legal obligations with family emotions while trying to honor someones wishes the best way possible.At Bellomo & Associates, we believe good estate planning is not just about what happens on paper. It is about preparing families for real life and helping the people left behind feel supported instead of overwhelmed.If you already have a trust in place, it may be worth asking yourself an important question:Would the people you love actually know what to do if something happened tomorrow? If not, then you should consider attending one of our free workshops.Because the trustees who struggle the most are often not careless people. They are loving family members who were simply never fully prepared for everything the role would require.
Jun 26, 2026
How to Avoid Sibling Conflicts When Caring for Aging Parents
As our parents age, we are faced with tough decisions on how to provide them with the care they need. Two common questions that adult children face are: (1) Who will provide the needed care; and (2) Where will mom or dad receive their care? Such decisions are not always easy to make. Family members can view care issues differently, leading to conflicts, especially when one sibling is the primary caregiver.At Bellomo & Associates, we understand that these situations are stressful, emotional, and can be exhausting, causing conflicts and family duress. Through our work with clients and families, we find that such conflicts are quite common; however, we believe that many conflicts can be avoided by having aging parents proactively identify their wishes and verbalize their plans and desires related to the what if scenarios clearly and frequently.If your aging parents have not yet talked openly about their wishes and expectations, we urge you to start the conversation with them as soon as possible. By committing to discussing the what ifs with your parents, you can prevent differences of opinion and sibling conflicts down the road. Open and honest communication is key, and we recommend having such conversations early and often.Another crucial step to preventing unnecessary sibling conflict is to have a formal caregiver agreement drafted if a family member becomes a paid caregiver. This agreement is an essential tool for clarifying the financial parameters of the care being provided and preventing misunderstandings between siblings.To learn more about caring for aging parents and avoiding related family conflicts, we invite you to attend an upcoming workshop on estate planning and elder law. Our team of experienced attorneys will provide you with the information and tools you need to make informed decisions and avoid conflicts. Additionally, consider attending a Life Care Planning workshop to meet our firms Client Care Advocate, Meg Motter, LCSW, and CDP. Having Meg on your familys team as a mediator and resource can make a difference in navigating the stressful dynamics of so many encounters as you care for your aging loved ones. Register now for a workshop at Bellomo & Associates and start planning for your familys future!
Mar 08, 2024
Avoiding Common Estate Planning Mistakes: A Message from Jeff Bellomo
Greetings, I trust this message finds you in good health and high spirits. In my years as an elder law and estate planning attorney here at Bellomo & Associates, Ive had the privilege of guiding families through the intricacies of planning for the future. Today, I want to share some insights on common estate planning mistakes, drawing from the experiences of those Ive had the honor of assisting. Its human nature to postpone tasks, especially those that involve contemplating the future. However, delaying your estate planning can have significant consequences. Whether youre an income-generating couple, a seasoned individual considering nursing home care, or a young family with dreams to protect, procrastination can rob you of the peace of mind that comes with a well-thought-out plan. No two families are the same, and neither should their estate plans be. Cookie-cutter approaches often neglect the nuances that make your situation unique. As your trusted advisor, I emphasize the importance of personalized solutions. Your plan should reflect your values, aspirations, and the legacy you wish to leave behind. Life is dynamic, and so are your circumstances. Marriage, births, career shifts, and even unexpected health challenges can reshape your priorities. Failing to update your estate plan accordingly can lead to unintended consequences. Regular reviews ensure that your plan remains a true reflection of your current life stage and desires. Discussing end-of-life matters can be uncomfortable, but its a crucial step in ensuring your wishes are understood and respected. Communicating openly with your loved ones about your estate plan can prevent misunderstandings and provide clarity during challenging times. In the age of online resources, its tempting to try a do-it-yourself approach to estate planning. However, the potential pitfalls of DIY plans can far outweigh the perceived cost savings. Professional guidance ensures that your plan complies with legal requirements and considers intricate details that may be overlooked. To those of you who resonate with these considerations, I extend an invitation to join us at our next estate planning workshop. Its not just an opportunity to learn about common mistakes but also a chance to connect with others who share similar concerns. Bring your questions, share your stories, and lets navigate the path to a secure future together. Remember, estate planning is not just a legal process; its a journey toward safeguarding what matters most to you. I look forward to meeting you and exploring the important next steps in creating a plan that reflects your unique legacy. To a future of informed decisions and lasting legacies, Jeff BellomoWe offer FREE WORKSHOPS every week! Click here to register!
Aug 30, 2024
.png)
Understanding Probate: A Step-by-Step Guide
Im Jeff Bellomo, an elder law and estate planning attorney at Bellomo & Associates in York and Lancaster, PA. Today, were going to embark on a journey together, one that demystifies the process of probate. Its a topic that touches the lives of many. Lets delve into Understanding Probate: A Step-by-Step Guide. The Path Begins with a LossProbate is often viewed as a complex legal process. But its crucial to remember that its not just about legalese and paperwork. Its a path that often begins with the loss of a loved one, a time when emotions run deep, and the need for support is essential. When someone passes away, the first step is to open an estate. This is done by filing a petition with the appropriate court, and this court will oversee the administration of the estate. During this time, the court will appoint an executor or personal representative, who plays a critical role in managing the deceased persons affairs. Inventory and Appraisal: Preserving Your LegacyThe next step is inventory and appraisal, a process of cataloging and valuing the assets within the estate. This may include real estate, financial assets, personal property, and more. Its not just about numbers on a page; its about preserving your loved ones legacy. Heres where it gets a bit emotional. Memories are often tightly connected to these assets. It can be challenging to go through this step, but its essential for ensuring a fair distribution of the estate and honoring your loved ones wishes. Notification and Payment of DebtsOne of the next steps involves notifying creditors of the deceased persons passing and paying off debts. This part can feel like navigating uncharted waters, especially when emotions are still raw. Its essential to ensure that all debts are resolved before the remaining assets are distributed to heirs. The Final Stage: Distribution to HeirsThe final step is the distribution of the remaining assets to heirs or beneficiaries. This is where the fruits of your loved ones lifes work are passed on to the next generation. Its a time to honor their memory and to provide for the financial well-being of those left behind. The Heart of ProbateProbate, though often seen as a legal process, is, at its core, a journey of the heart. Its about closure, healing, and ensuring that your loved ones wishes are carried out. Here at Bellomo & Associates, we understand that the emotional aspect of probate can be overwhelming, especially when coupled with the legal intricacies. Thats why were here to guide you through every step of the way, providing the support and expertise needed to navigate this journey with confidence. Join Us at Our Estate Planning WorkshopIf youd like to learn more about probate and other critical aspects of estate planning, I invite you to join us at our next estate planning workshop. Its a place where you can connect with other like-minded individuals and ask questions. Its about taking those important next steps in creating a comprehensive estate plan. Remember, youre not alone on this path. Were here to support you, connect with your emotions, and guide you toward securing your familys future.
Aug 23, 2024
Maximizing Medicaid: How Asset Protection Plans Can Help You Save Money on Long-Term Care
Medicaid is a government program that provides health coverage to individuals, and it is the leading payor of skilled nursing facility care in the United States due to the high cost of such care. Many people mistakenly believe that Medicaid is only for those with minimal resources, but an asset protection plan can help you protect your assets and still qualify for long-term Medicaid benefits.Asset protection planning uses exemptions that allow you to keep some of your assets. For example, in Pennsylvania, you are allowed to keep $45 of your income per month plus any amount you use to pay for health insurance; the rest of your income must be used to pay for your care. When applying for Medicaid, countable resources include assets such as real estate, cash, investment accounts, retirement accounts, life insurance with a face value greater than $1,500, vehicles, and any business interests. However, you can exempt the house you live in, one vehicle, and your spouse can retain their retirement accounts and anywhere between $29,724 and $148,620 of the joint assets, depending upon the total amount of your combined assets. Anything over this calculated amount of exemptions could be put into an asset protection trust and protected from skilled nursing facility costs.An asset protection plan will allow you to immediately protect a portion of your assets, in addition to the assets that are exempt from Medicaid, for significant immediate savings that begin the moment your plan is fully funded.An asset protection plan consists of an asset protection trust, in which you can control the assets, but cant have direct access to them. Giving up direct access to the assets in the trust keeps creditors and predators away. If you do need access to an asset in the trust, you always have the ability to make distributions to someone other than yourself.Asset protection plans not only protect your assets during life but also provide tremendous value for your loved ones when youre gone.Laws and statutes in the area of long-term care Medicaid are always changing, so its highly recommended to review your options with a local elder law/estate planning attorney. At Bellomo & Associates, we can help you learn more about asset protection plans and how they can benefit you and your family while protecting your legacy from the rapidly rising cost of long-term care. Dont wait lets get your estate plan in place!Are you ready to start protecting your assets and planning for long-term care? Contact Bellomo & Associates today to register for an educational workshop. We can help you create a customized asset protection plan and provide guidance on long-term care Medicaid eligibility and planning. Dont wait until its too latetake action now and secure your financial future.
Mar 01, 2024
Youve Been Named a Beneficiary. What Happens Next?
Learning that you have been named as a beneficiary can bring a mix of emotions. You may feel grateful that someone thought of you. You may also be grieving the person who made the gift possible. At the same time, you may feel uncertain about what comes next. When will you receive the inheritance? What information are you entitled to see? Will you owe taxes? Are you responsible for the deceased persons debts? Can you simply deposit the money and move forward? These are understandable questions, and the answers depend on what you inherited and how it is being transferred. Being named as a beneficiary does not always mean a check will arrive right away. Before making plans for the money or property, it is important to understand the process, the role of the executor or trustee, and the decisions that may need to be made along the way. At Bellomo & Associates, we often remind families that an inheritance is not only a financial event. It is also part of a larger legal and emotional process that deserves time, patience, and thoughtful guidance. Start by Determining What Kind of Beneficiary You AreThe word beneficiary can describe several different situations. You may be named in a will, included as a beneficiary of a trust, or listed directly on a life insurance policy, retirement account, or financial account. If you are a beneficiary under a will, your inheritance may pass through probate. The executor must complete the estate administration process before final distributions can be made. This may include gathering assets, paying valid debts, filing tax returns, selling property, and completing required court filings. If you are a trust beneficiary, the trustee will manage or distribute assets according to the terms of the trust. Some beneficiaries receive an immediate distribution. Others receive money over time, at certain ages, or only for specific purposes. Life insurance policies, retirement accounts, and payable-on-death accounts may pass directly to the person named on the account. These assets may avoid probate, but they can still involve paperwork, deadlines, tax rules, and important distribution decisions. Before asking when you will receive your inheritance, first determine where it is coming from and which document or account controls the transfer. Why an Inheritance May Take TimeOne of the most common questions beneficiaries ask is, How long will this take? Unfortunately, there is no universal answer. Some assets can be transferred relatively quickly. Probate estates and trusts may take months or longer to administer, especially when property must be appraised or sold, creditors must be addressed, tax returns must be prepared, or disagreements must be resolved. Imagine a daughter who learns that she will receive one-third of her mothers estate. She may expect the money within a few weeks. But the estate includes a house that must be sold, unpaid medical bills, investment accounts, and tax filings that still need to be completed. Her percentage may be clear, but the final amount and distribution date may not be. A delay does not automatically mean the executor or trustee is doing something wrong. In fact, distributing assets too early can create serious problems if debts, expenses, or taxes remain unpaid. At the same time, beneficiaries should receive reasonable updates and should not be left completely in the dark. Ask for the Information You NeedBeneficiaries should understand what they are receiving and how their share will be calculated. Depending on the situation, you may need to review the will, relevant trust provisions, an estate inventory, appraisal information, an accounting, or proposed distribution documents. It is also reasonable to ask whether probate has been opened, whether there are outstanding debts, whether property needs to be sold, and when you can expect the next update. Pay close attention to anything you are asked to sign. A receipt, release, waiver, settlement agreement, or approval of an accounting may carry significant legal consequences. It may do more than confirm that you received property. It could also approve the executors actions, waive your right to additional information, or release potential claims. Do not sign something you do not understand simply because you are eager for the inheritance to be distributed. Understand the Executors or Trustees RoleAn executor or trustee does not personally own the estate or trust property. That person is serving in a fiduciary role and must follow the governing documents and applicable law. The executor or trustee may be responsible for protecting assets, keeping accurate records, paying appropriate expenses, communicating with beneficiaries, and making distributions at the proper time. Beneficiaries have legitimate interests, but they cannot necessarily demand an immediate distribution or require the fiduciary to ignore debts, taxes, or the terms of the will or trust. For example, one beneficiary may want the family home while the others want it sold. The executor may need to obtain an appraisal, review the estate documents, and determine whether a buyout is realistic before moving forward. The healthiest estate and trust administrations usually involve accountability from the fiduciary and patience from the beneficiaries. Are Beneficiaries Responsible for the Deceased Persons Debts?In most situations, beneficiaries are not personally responsible for another persons debts simply because that person died. However, valid debts may still need to be paid from the estate before the remaining assets are distributed. This means debts can reduce the amount a beneficiary receives, even when the beneficiary does not personally owe them. Suppose three children are equal beneficiaries of an estate initially valued at $300,000. After funeral expenses, administration costs, taxes, secured debts, and valid creditor claims are paid, only $240,000 remains. Each child would generally receive one-third of the remaining estate, not one-third of the original value. Personal responsibility may be different when someone jointly signed for a debt, guaranteed an obligation, or shares legal responsibility for the account. Beneficiaries should also be cautious of fraudulent debt collectors. Do not send money or provide personal information simply because someone claims you are responsible for a deceased relatives debt. Legitimate claims should generally be directed to the executor or personal representative. Will You Owe Taxes on an Inheritance?Many people assume that every inheritance is taxable income. The reality is more complicated. Inherited cash or property is generally treated differently from wages. However, inherited assets can still create tax consequences. Income earned by an estate or trust may be reported to beneficiaries. Inherited investments or real estate may also create taxable gains when sold. The value of inherited property at the time of death may become an important part of the tax calculation. That is why beneficiaries should keep appraisal reports, account statements, tax forms, closing documents, and other records showing how inherited assets were valued. Pennsylvania also has an inheritance tax, and the rate may depend on the beneficiarys relationship to the person who died. Because tax rules can vary based on the asset and the people involved, it is wise to speak with an appropriate tax professional before selling, transferring, or withdrawing significant inherited property. Be Especially Careful With an Inherited IRAInherited retirement accounts require special attention. They should not be treated like ordinary bank accounts. The rules may depend on whether the beneficiary is a surviving spouse, whether the account is a traditional or Roth IRA, and whether required minimum distributions had already begun. Many nonspouse beneficiaries are subject to a 10-year distribution rule, although additional withdrawal requirements may apply in some situations. Surviving spouses may have options that are not available to other beneficiaries. One of the costliest mistakes a beneficiary can make is immediately cashing out an inherited retirement account without understanding the tax consequences. A large withdrawal could create a significant income tax bill and eliminate more favorable distribution options. Before moving, retitling, or withdrawing money from an inherited retirement account, confirm the rules that apply to your situation. Use Caution With Real Estate, Releases, and DisclaimersInherited real estate can create both financial and emotional challenges, especially when several beneficiaries receive the same property. One sibling may want to keep the family home. Another may want to sell it. A third may be unable to decide while grieving. Meanwhile, someone must continue paying the insurance, taxes, utilities, maintenance costs, and possibly the mortgage. An independent appraisal, written buyout proposal, financing plan, and clear deadline may be necessary. Simply transferring the property into everyones names may not solve the disagreement. It may only turn an estate issue into a co-ownership issue. Beneficiaries should also seek advice before disclaiming or refusing an inheritance. You generally cannot disclaim an asset and then decide who receives it instead. The will, trust, beneficiary designation, or applicable law determines where the property goes next. Accepting the property or taking control of it may also affect your ability to disclaim it later. Protect the Inheritance After You Receive ItAn inheritance often arrives during a time of grief, stress, and major change. That is rarely the best time to make irreversible financial decisions. Before quitting a job, purchasing a home, making large gifts, lending money, or investing in something unfamiliar, give yourself time to understand what you received. Be especially cautious about placing inherited funds into a joint account or adding another person to the title of inherited property. Mixing inherited assets with jointly owned property may affect ownership, creditor protection, divorce exposure, and your ability to trace the inheritance later. Sometimes the wisest first decision is to make no major decision at all. Know When to Seek Legal GuidanceNot every delay or disagreement means that something improper has occurred. However, certain warning signs deserve attention. You may need legal guidance if the executor or trustee refuses to provide basic information, estate property appears to be missing, funds are being used for personal purposes, one beneficiary is receiving unexplained preferential treatment, or you are being pressured to sign a broad release. Professional guidance may also be important when the inheritance includes a business, retirement account, property in multiple states, complicated tax issues, or assets left to someone who receives needs-based public benefits. Bellomo & Associates helps beneficiaries understand the estate and trust administration process, review important documents, and identify concerns before avoidable mistakes become expensive ones. Take the Process One Step at a TimeBeing named as a beneficiary does not mean you need to understand every legal, tax, and financial issue immediately. It does mean you should take the time to learn what you are receiving and how the process works before making important decisions. Start by identifying the asset and the person responsible for administering it. Ask for appropriate documents and updates. Understand that valid debts and expenses may need to be paid before distributions can occur. Review the tax consequences before selling property or withdrawing retirement funds, and do not sign agreements you do not understand. An inheritance can provide meaningful financial security, but it can also create avoidable problems when decisions are rushed. Before you sign, sell, withdraw, transfer, or distribute anything, take a breath and make sure you understand what you inherited and what your next decision could mean for your future.
Aug 21, 2026
.png)
My Journey in Life Care Planning
I have been an Estate Planning and Elder Law Attorney for approximately 20 years. I have been fortunate enough to obtain the designation to become a Certified Elder Law Attorney and to receive a Master of Law in Taxation and a certificate in Estate Planning. There is no doubt that finding Elder Law as a career was the best thing that allowed me to go to work every day, excited to assist people and help them. Over the years, I have known a bit about Life Care Planning and have admired it from a distance. The bottom line was I did not understand it nor truly understand what the purpose was and how it could help clients. Over time, I became frustrated in meetings when clients would ask me if their mom was safe to be at home, or what modifications would need to be done to keep mom at home, or how long could mom stay in the assisted living, and under what circumstances would she then have to move on to another level of care. I did not know the answers to many of these questions and, although I did have referral sources, I felt inadequate, or disappointed, that I was not able to help the client directly. I have also known Meg Motter for many years. Meg is a Masters prepared Licensed Clinical Social Worker and has been in the industry for most of her career. I knew I always wanted to work with Meg, but unfortunately, the timing and the money never worked out until the Spring of 2021. When the opportunity presented itself and she was available, I acted immediately and, without even truly understanding the Life Care Planning model, jumped in with two feet, knowing I had the right person. Now that our firm is knee-deep in Life Care Planning, there is no doubt that it was the best decision that I have made, mostly for the clients that we serve. The assistance that she can provide, which we were not able to offer previously, is astounding. I believe that everything happens for a reason and, although it took several years for us to embrace the model and to have the right person, there is no doubt that it is the right thing for our clients, and I am excited to share everything about the life care planning model to anyone who will listen. Monthly Life Care Planning Workshops are offered at both our York and Lancaster offices. If you would like to learn more about Life Care Planning and our Client Care Advocate, Meg Motter, LCSW, CDP please reach out to the office at (717) 208-4546.
Feb 16, 2024
Alzheimers Disease: The Game Changer
In the mid-90s, my grandpa Bellomo was diagnosed with Alzheimers Disease, and I remember watching him progress through the stages of this disease and thinking how horrible it was and that he was no longer my grandfather. I remember being very optimistic that there would be a cure for this disease in the very near future. Here we are in 2022 and there are no cures to this difficult disease. In my practice as an estate planning and elder law attorney, we have answers to just about every question and solutions to just about every problem. The one constant difficult issue that arises on a regular basis is a client who is diagnosed with Alzheimers Disease and how to provide the care that they need to keep them safe as long as possible. Certainly, keeping somebody at home is a much better option than taking them out of their environment into another situation but as this disease progresses, the individuals will often get combative and violent and oftentimes cannot remain in the home. There are several wonderful care options at assisted living facilities that are called memory units. Unfortunately, these are private pay situations with no ability for government funds to help assist or pay for this type of living. Oftentimes, memory care units can cost somewhere between $7,000 and $9,000 a month which often becomes cost prohibitive. In many cases, the individual ends up being placed in a nursing home not because a nursing home is the right place for the client, but rather because there are ways to have the government assist with the funding of the approximate $12,000 to $13,000 a month of care. Whether or not this is the best place for the individual is certainly debatable but for some families it is simply not an option. Alzheimers is a very difficult disease and our hats off to all caregivers out there who are assisting to the best of their ability. Please feel free to give us a call if you have any questions or comments at 717-845-5390.
Dec 17, 2022

July Is Sandwich Generation Month
Caught in the Middle? Estate Planning Tips for the Sandwich GenerationJuly is Sandwich Generation Month. A time to recognize the millions of adults caring for aging parents while still raising kids (or supporting adult children). If that sounds like your life, youre not alone.Maybe youre juggling your dads medication schedule while reviewing your daughters college tuition bill. Or trying to plan your retirement while fielding calls from your moms assisted living facility. Welcome to the Sandwich Generation, that not-so-exclusive club of adults who are caught in the middle.And while youre managing everyone elses needs, heres one thing that often gets overlooked: estate planning matters. Not just for your parents. Not just for your kids. For you, too.At Bellomo & Associates, we help families like yours get ahead of the stress and start planning early, before a crisis makes everything harder.Whens the Right Time to Talk? (Spoiler: Its Now.)You know those conversations about what happens if that no one wants to have? The ones that end in a sigh or a subject change? Yes, those.But the best time to talk is when no ones in the hospital. When everyone is clear-headed. When you still have the luxury of time.Think of it like taking a trip. You could toss clothes in a bag and hope for the best or you could make a plan, pack what you need, and enjoy the journey. Estate planning is the same. You may not control every twist in the road, but the right plan makes it easier to keep moving forward.The Emotional Toll Is RealAnd So Is the Financial OneSandwich generation caregivers carry a heavy emotional load. But many also face financial pressure that doesnt make the headlines.You might be helping with your moms in-home care expenses while still covering summer camp. Contributing to your parents bills while trying to grow your retirement savings. And through it all, theres a quiet question running in the background: What happens if something happens to me?Estate planning is how you answer that question before your family has to.Its about taking control. Spelling out your wishes. Naming the right people to step in when needed. And protecting what youve built so your loved ones dont have to untangle a mess while grieving. Make the Talk Less Awkward (Yes, You Can)No, you dont have to schedule a family retreat with printed binders and pie charts. Sometimes all it takes is the right moment and a touch of humor.Maybe it sounds like, So, Mom what kind of music do you want at your funeral? Because Im thinking heavy metal.Laughter can open doors. You dont need to have every answer at once, you just need to start the conversation. The Stats Tell a Clear StoryThis isnt just your experienceits a national trend.About 2.5 million Americans are part of the sandwich generation1 in 4 caregivers supports both an aging parent and a child under 18Sandwich caregivers are twice as likely to report financial stress, and significantly more likely to experience emotional burnout(Source: University of Michigan, 2022)So if youre feeling stretched? Thats not a failure, its a call to plan better. How Bellomo & Associates Can HelpYou dont need to have it all figured out. Whether youve never touched an estate plan or youve got a will collecting dust in a file cabinet, well meet you where you are.We help families plan for the future, protect what matters, and create legal documents that do what theyre supposed to do when it matters most. From wills and trusts to guardianship and healthcare directives, our goal is to take something complicated and make it make sense.And if youd rather not be the one to initiate the talk? Thats what were here for.
Jun 27, 2025
Dont Let a Healthcare Crisis Turn Into a Legal Crisis
Most people understand that estate planning is important. They know they should have documents in place that name someone to make financial decisions, healthcare decisions, and eventually handle their estate after death. As an elder law attorney, I routinely meet individuals who are highly motivated to get their documents done and feel a sense of relief once everything is signed. Unfortunately, far too many families discoveroften during a medical emergencythat having documents alone is not enough. A healthcare crisis can quickly become a legal crisis when intentions are unclear, communication is missing, and family members are left guessing about what their loved one truly wanted. This article explains why that happens, how to prevent it, and why clear communication is just as important as the legal paperwork itself. The Foundation: Essential Estate Planning Documents Most comprehensive estate plans include several core documents: A financial power of attorney, which authorizes someone to manage financial affairs if you become incapacitatedA healthcare power of attorney, which allows someone to make medical decisions on your behalfA will or trust, which outlines how your assets should be handled after death and names an executor or trustee Many people do a good job selecting who they believe is the right person for each role. They often choose a spouse, adult child, or trusted family member and feel confident that everything will work smoothly. However, that confidence can be misplaced if the most important step is skipped. The Most Common Mistake: Assuming Your Agent Knows What You Want One of the most common problems I see is this: people appoint agents and decision-makers but never clearly explain what their wishes actually are. They assume: My spouse knows how I want things handled.My children will figure it out.Theyll just do whats best. Unfortunately, these assumptions often lead to confusion, disagreements, and sometimes full-blown legal disputes. Legal authority without guidance leaves too much room for interpretation. When your wishes are not clearly communicated, even well-intentioned agents may make decisions that conflict with what you would have wanted. Why This Becomes a Crisis During Healthcare Emergencies Healthcare emergencies are emotional, stressful, and fast-moving. Decisions often need to be made under pressure and with limited information. If your healthcare agent doesnt know these key viewpoints, theyre forced to guess: Your beliefs about medical treatmentYour views on quality of life versus longevityYour wishes regarding life-sustaining treatment When multiple family members are involved, those guesses often conflict. Each person may believe they are honoring your wishes, even though their interpretations differ. This is how a healthcare crisis turns into a family conflictand sometimes a legal battle. Theyre Not Fighting Over What Mom Wanted I often share this observation with clients: Children rarely fight over what mom or dad wanted. They fight over what mom or dad intended. When intentions are clearly stated, families tend to respect them, even if they disagree personally. When intentions are vague or never discussed, every family member fills in the blanks differently. I have seen situations where siblings say with absolute certainty: Mom intended for us to sell the house.No, mom intended for one of us to keep the house.Dad intended for us to use the money this way. Each person genuinely believes they are right. The conflict arises not because someone is acting maliciously, but because the wishes were never clearly communicated. Financial Powers of Attorney: More Than Just Paying Bills A financial power of attorney gives your agent broad authority. That authority can include paying bills, managing investments, selling property, and handling long-term care planning. However, without guidance, your agent may not know: How you prefer your bills to be paidHow conservative or aggressive you are with investmentsWhether you prioritize preserving assets or spending for comfortHow you feel about gifting or helping family members financially Even small differences in approach can lead to tension or accusations of wrongdoing. Clear communication protects both you and the person you appoint. Healthcare Decisions Require Even More Clarity Healthcare powers of attorney are particularly sensitive. Medical decisions often involve deeply personal beliefs about dignity, independence, and end-of-life care. Your healthcare agent should understand: Your views on life-prolonging treatmentYour wishes if recovery is unlikelyYour feelings about pain management and comfort careAny religious or personal beliefs that affect medical choices While living wills and advance directives can help, they are not substitutes for real conversations. Written documents work best when they supportnot replaceclear communication. Executors and Estate Administration Even when a will or trust divides assets equally, disputes can still arise. Executors often face difficult decisions, such as: Whether to sell or retain a family homeHow to handle sentimental itemsHow quickly assets should be distributed If your executor doesnt understand your intentions, they may feel pressured by other beneficiaries or second-guess their decisions. This can strain relationships and delay estate administration. A brief conversation explaining your priorities can prevent years of resentment and confusion. Simple Ways to Communicate Your Wishes Communicating your intentions doesnt require complex legal drafting. What matters most is that your wishes are expressed clearly and consistently. Efficient ways to communicate your wishes may entail: Writing a letter or email to your agents explaining your wishesHolding a family meeting so everyone hears the same messageDiscussing your decisions directly with the people you appoint These conversations dont need to cover every detail. Even general guidance can make a significant difference. Why Putting It in Writing Matters Putting your wishes in writing creates clarity at a time when emotions often run high, and memories can be unreliable. It removes guesswork and provides a clear reference point for the people you have chosen to act on your behalf. When agents and family members can look to your written guidance, they are far less likely to question what you intended or feel uncertain about difficult decisions. Written communication also serves an important protective function. It helps prevent misunderstandings, reduces the risk of conflict among family members, and protects agents from accusations that they acted improperly or in their own interest. Just as important, it promotes family harmony by ensuring everyone is working from the same understanding of your wishes. Not every preference needs to be legally binding or formalized in a document drafted by an attorney. In many cases, a straightforward written explanationsuch as a letter, email, or personal statementcan provide enough guidance to avoid confusion and conflict when it matters most. Learn How to Protect Your Family the Right Way Understanding how to communicate your wishes effectively is just as important as having the right legal documents. Education empowers you to make informed decisions and avoid common mistakes. Bellomo & Associates offers free educational workshops on estate planning and asset protection. These workshops are designed to help individuals and families understand not only what documents they need but also how to use them properly to prevent conflict and protect their future. If you want to ensure your healthcare decisions and estate plans truly reflect your wishesand that your family understands themjoin us for an upcoming workshop or contact our office today. Taking this step now can help prevent a healthcare crisis from becoming a legal and family crisis later.
Jan 09, 2026
Biggest Mistakes In Special Needs Planning
It is imperative that families of individuals with disabilities and special needs get appropriate advice when it comes to their estate planning. Special needs trust planning can provide a family significant peace of mind knowing that their children will not only continue to receive the government benefits that they are entitled to, but also access to the money that they are leaving them in a special needs trust.It is often a shame to see mistakes that families make in this area. They often are the same mistakes and I would like to assist today by shining a light on them. Although there are many more, here are just a few of the biggest mistakes that we see families making in the special needs context:1. Taking the cheap way out In light of how easy it is to get documents done online or in the age of every attorney believing that they do that too it is very easy for consumers to believe that quality does not matter. Although I have written many other blogs that talk about why quality does matter in all planning contexts, it certainly matters in the special needs context more than ever. Many of your online drafting companies as well as your inexpensive local attorney options are usually not people who specialize in this area. Special needs planning, more than any other area, requires knowledge and skill to ensure that a beneficiary does not get disqualified from any governmental benefits. Avoid the temptation of taking the inexpensive or cheap way out and get the planning done correctly.2. Waiting until it is necessary We often see people in this context who do not want to come to grips with the fact that they need to get the planning done sooner rather than later. They often will wait until the moment is perfect or until they have every answer to every question that they may ever need to know. Because of what is at stake, it is essential not to procrastinate and to get the planning done as early as possible. If you die without the correct planning in place, the risk is loss of benefits to your child, not only from their government benefit perspective but the loss of access to all the money that you are going to leave them as well. Avoid the temptation to be perfect and get documents placed that will protect your family. You can always update and make changes later to make it perfect but dont procrastinate and take a chance on it being too late.3. Failing to name an appropriate trustee or co-trustee The selection of a trustee is an extremely important decision in all trusts. However, this decision is probably more important in the special needs context than in any other context because of all the stringent rules that are required for special needs trust administration and the fact that one mistake or one improper distribution can have an individual lose their SSI benefit or Medicaid benefit. It is imperative that the trustee be up on the law and know the rules that apply to special or supplemental needs trusts inside and out. We typically recommend a corporate trustee in this instance and many of them are non-profit organizations that will act as trustees and do so as a profession on a normal ongoing basis. If you have a family member that you would like to name, consider adding them as the co-trustee with a corporate fiduciary. It is difficult for a corporate fiduciary to stay on top of all of the real changes in the social security context through the POMS and in the Medicaid context through case law and regulations, which makes it impossible for an individual to stay on top of all of those regulations. Our recommendation is to find a corporate fiduciary that you are comfortable with and then add a family member as a co-trustee to allow a family member to be involved.4. Getting it done early and forgetting about it As I stated above, getting it done early is imperative, but you also dont want to get it done and never update it. These are living, breathing documents and there are a lot of things that can change in our lives that would affect the documents themselves. Make it a plan to touch base with the attorney who drafted the documents at least once a year. There are often changes in the special needs arena and we recommend making updates as changes in the law and changes in the social security POMS occur on at least an annual basis. Dont fall into the trap of creating the documents and never reviewing them.We hope that these common mistakes to avoid when drafting special needs trust planning was a valuable use of your time. If you would like to learn more about special needs trust planning, please contact our office to learn more information about our special needs trust workshop.If you would like to have additional information or to discuss this further, please give us a call at 717-845-5490.
Sep 01, 2023
Are Estate Planning Online Documents "Good Enough"?
We get asked all the time by people about whether or not an estate planning online document would be good enough. The bottom line with the do-it-yourself options and the online options is that they are not state-specific.Each and every state in the country has its own nuances and its own unique rules, and many of the generic form databases and/or online functions do not meet the nuances of each state. I have actually seen, in several cases, where they advertise that they do, and even the paperwork that the client receives says that it does, but in reality, it simply does not.The other major issue that I have with online estate planning tools is that it is junk in and junk out. What I mean by that is they are going to ask you questions that you have to answer that will determine how the document will be drafted. If you do not know the answer or know the implications of the answer that you are giving, there is no way that you can know whether that document will work at the time that you need it to.I also worry about the unknown and about implications and situations that are currently not a concern but become so in the future. Most of the online or do-it-yourself forms are very short, very simplistic, and very basic.The problem with that is what happens if a beneficiary is receiving public benefits at the time of your death? What happens if an individual receives money outright and is in a horrific car accident and kills 10 people? There are so many variables that change estate planning that are just not accounted for in the do-it-yourself or online programs.One rebuttal that I often hear is that they do not have enough money to worry about those situations or those minor exceptions. I certainly appreciate that and respect that, but I think in some cases, that is a very easy cop-out and is a very short-sighted answer. It does not take a lot of money to have an unforeseen incident occur to lose it and to be extremely hurt and disappointed over the consequence of that action.For example, a client recently went the online program route and had planning done, but unfortunately had a stroke and needed to go into a nursing home. The person lost all of their assets because the planning was not done correctly, and the family is very regretful that they made that decision.The gentleman made a very conscious decision, that he saved a couple hundred dollars and did his documents online because he did not feel that he had enough to warrant our services and our expertise. To the individual, a couple hundred thousand dollars was not a lot of money and he could not justify the expense of using our firm versus the cost of the online program. Unfortunately, the gentleman lost several hundred thousand dollars to the nursing home simply because he used an online form that did not provide for the advanced planning that would be needed. This is a very common occurrence, where people cant seem to justify the investment and have planning done appropriately because in their eyes the amount of money that they have doesnt justify the excess expense.This is a very glaring example of how he did save a couple of hundred dollars, but in return, he lost a couple hundred thousand dollars of his hard-earned money, that could have gone to his family. The children and I have had several conversations about it and one of them even was encouraging him to hire our firm to get the work done properly. The son just could not understand why dad went with the cheap option online after he was warned, numerous times, by me and others.It is very sad these days that online companies and attorneys who do not specialize in an area are able to market that they are a one-stop shop and do everything. When in reality, they dont and their documents dont provide for the same things. Beware of saving a couple of dollars or a couple hundred dollars when the risks to you and your family are much greater than that. Go to a specialist who understands estate planning, elder law, and asset protection can give good advice, and can provide personal assistance and not just a form document that gets spit out of a computer.If you would like to learn more about this, please contact our office at 717-208-4546.
Aug 25, 2023

Seniors BlueBook Senior Care Spotlight Presents "How to Not Become a Homeless Senior!!"
We visited with Jeff Bellomo of Bellomo & Associates and explored how not to become a homeless senior! How do you protect your home and yet be prepared? Are there tax advantages? Jeff Bellomo, Bellomo & Associates, 717-845-5390, www.bellomoassociates.com. More questions? Ask Chris Gartman, Publisher, Seniors Blue Book of South Central PA - [email protected] #Money #Savings #NursingHomes #Homes #Finances #ElderLaw #BellomoAssociates #SeniorsBlueBook
Nov 30, 2020
Seven Financial Considerations When Downsizing for Retirement
For many people, retirement is not just about leaving the workforce; its about starting a new chapter. That new chapter often comes with the question, Do we really need this much house? Downsizing can be a wonderful way to simplify, save, or even move closer to family. But the decision is about much more than just picking a smaller home. Its about ensuring that your financial life, taxes, and estate plan all align seamlessly with your new lifestyle. Here are seven important financial factors to keep in mind before you make the move:1. Housing costs are more than the listing priceIts easy to focus on the purchase price or rent, but housing costs also include location, safety, maintenance, and the overall feel of the community. Spending some time in a neighborhood before you commit can give you a better sense of what daily life will really cost. 2. State estate and inheritance taxesEvery state has its own rules. Some have no estate or inheritance taxes at all, while others have both. Moving just across a state line could make a big difference in what your loved ones ultimately receive. 3. State income taxesNine states currently dont impose a state income tax, which can sound appealing. But states without income taxes often make up for it in other ways, like higher property taxes or fees. A balanced perspective is key. 4. Property taxesProperty taxes vary widely and can significantly impact your monthly budget. Some states also offer senior discounts or exemptions, which are worth investigating before committing to a new home. 5. Retirement account and pension taxesNot all states treat retirement distributions the same way. Some tax withdrawals from IRAs and 401(k)s, while others dont. Pensions, including military pensions, are also taxed differently depending on where you live. 6. Social Security taxationMost states do not tax Social Security benefits, but a few do, often with income-based limits. Knowing this before you relocate can prevent unpleasant surprises. 7. Sales taxes arent the whole storyIt can be tempting to focus on states with no sales tax, but this is often less significant than property or income taxes. Looking at the big picture of overall taxation is always smarter. Bringing it all togetherDownsizing for retirement isnt just about real estate. Its a financial and legal decision too. At Bellomo & Associates, we help families look at the whole picture, from taxes to estate planning to long-term goals, so the decision feels less overwhelming and more empowering. If youre thinking about downsizing or relocating, now is the perfect time to review your estate plan and make sure it supports this next chapter of your life.
Sep 19, 2025

Is a DNR the same as a Living Will?
The short answer is no, they are not the same. A DNR stands for a DO NOT RESUSCITATE order. A Living Will is a completely different document that is used during a very different time.A DNR should be entered into at your doctors office or in the hospital, not at your local estate planning and elder law attorneys office.Typical estate planning documents that an attorney will assist you with would include a financial and medical power of attorney as well as a Last Will and Testament and maybe a Trust of some type. The confusion often lies in the fact that in a medical power of attorney, you will often see a Living Will as a part of the document.This is collectively known as an Advance Healthcare Directive if medical power of attorney and living will are together in one document. The Living Will does not kick in until the individual is end-stage medical. While there is a very long medical definition for this term, I simply like to state it as when two qualified physicians put in writing that there is no realistic hope of recovery and that you will always remain vegetative, comatose, permanently unconscious, and terminally ill. A medical power of attorney, living will, or advanced health care directive are often documents that are obtained from your estate planning and elder law attorney and not from your health care provider.On the other hand, a DNR or DO NOT RESUSCITATE order is intended to let emergency and other medical professionals know whether or not they should resuscitate you. Methods often used for resuscitation would be things such as defibrillators, breathing tubes, ventilators, CPR, and other invasive techniques.The DO NOT RESUSCITATE order comes into play when the heart has stopped beating or the person has stopped breathing. The medical power of attorney, on the other hand, comes into play when the person simply cannot answer questions for themselves. That could be for numerous other reasons, such as being under sedation or incapacitated, unconscious due to an accident, or unable to speak.Certainly, it does not necessarily mean that the heart has stopped beating or that you have stopped breathing. The Living Will does not kick in until the end of life, but the heart is often beating, sometimes due to heroic and lifesaving measures, but the DNR will prevent those heroics if that is your wish.We truly believe that it is imperative for you to talk to your estate planning and elder law attorney about the estate planning documents as outlined above as well as discuss with your doctor about a DNR order. While you are discussing the DNR order, we would also recommend that you have a conversation with your healthcare professional about a POLST (Physicians Order of Life-Sustaining Treatment). These are documents that will be obtained directly from your doctor and they will be able to assist you with the nuances of how they work.We hope this article provided insight into the definition of a DO NOT RESUSCITATE order and the difference between a medical power of attorney and a Living Will. If you would like further information about these items, contact our office. Wed be more than happy to assist you. Call us at (717) 845-5390.
Nov 17, 2023
Life Care Planning: More Important Now than Ever in Our Post-Pandemic World
As an elder law attorney, I have witnessed firsthand how the COVID-19 pandemic has altered the way families approach long-term care and the importance of planning. While estate planning has always been a critical tool for protecting assets and honoring personal wishes, todays families must think beyond traditional documents. Thats where life care planning comes ina holistic, care-focused approach that combines legal protection with ongoing support for the challenges of aging.In this article, we will explore what Life Care Planning is, why its more important than ever in our post-pandemic world, and how families can benefit from working with a law firm that integrates legal services with compassionate care advocacy.What Is Life Care Planning?Life care planning is a comprehensive approach to elder law. Instead of focusing only on wills, trusts, and powers of attorney, life care planning looks at the entire aging journey. It addresses legal, financial, medical, and personal care needs in a unified way.A key feature of life care planning is the role of the client care advocate. This professionaloften a licensed social worker or nursehelps families navigate the healthcare system and ensure that loved ones receive quality care. Bellomo & Associates is proud to have Meg Motter, LCSW, CDP, on our team as our client care advocate. Meg works closely with families every day to provide answers and guidance during some of the most challenging times of their lives.Why Life Care Planning Matters More After the PandemicThe pandemic was a wake-up call for many families. It revealed just how vulnerable seniors can be in times of crisis and how quickly circumstances can change. Nursing home lockdowns and hospital restrictions left many families struggling to advocate for loved ones from a distance. In many cases, people realized too late that they lacked the information, documents, or resources needed to respond effectively.The pandemic highlighted several truths:A crisis can strike at any time. Families must be prepared not only financially but also emotionally and logistically.Advocacy is essential. Having a knowledgeable professional like a client care advocate ensures that families know their options and have someone to guide them through complicated healthcare and long-term care systems.Care planning cannot wait. Delaying important conversations and legal planning often results in fewer choices and higher costs.Life care planning directly addresses these challenges by offering both legal protection and ongoing care advocacy.The Benefits of Life Care PlanningLife care planning provides peace of mind by combining estate planning with real-world support. Families benefit in several key ways:Holistic Approach: Legal planning is integrated with healthcare and caregiving support.Professional Advocacy: A client care advocate helps coordinate care, evaluate facilities, and connect families with trusted resources.Proactive Problem-Solving: Instead of waiting for a crisis, life care planning prepares families for every stage of aging.Asset Protection: Legal strategies ensure that resources are preserved to provide the best possible care.Reduced Family Conflict: With clear guidance and professional support, families can make decisions with less stress and fewer disagreements.The Role of a Client Care AdvocateAt the heart of life care planning is the client care advocate. Families often find themselves overwhelmed with questions about healthcare and caregiving. The client care advocate bridges the gap between legal planning and day-to-day support.For example, families may need help with:Understanding options for in-home care, assisted living, or nursing facilities.Navigating Medicaid and Medicare rules.Assessing the quality of care provided by facilities.Coordinating medical services and long-term care providers.Providing emotional support during difficult transitions.Having this expertise under one roof makes life care planning uniquely valuable. At our firm, Meg Motter plays this role daily, reassuring families that they are not alone.Why Traditional Estate Planning Is Not EnoughWhile wills, trusts, and powers of attorney remain essential, they do not address the practical realities of caregiving. For example:A power of attorney can authorize someone to act, but it does not tell families what care choices to make.A will distributes assets after death but offers no guidance for how to manage care during life.A trust may protect resources, but it does not connect families with the services they need right now.Life care planning fills these gaps by combining legal tools with ongoing care advocacy.Lessons Learned from the PandemicDuring the pandemic, our firm saw firsthand how critical life care planning is. Families were calling daily with urgent questions:How do I get my mom the care she needs if I cant visit her facility?What are my rights if the hospital wont let me in to see my spouse?What happens if my loved one needs immediate placement in a nursing home?Without a care advocate, these questions often went unansweredor answers came too late. Having Meg on our team ensured that families had someone who could respond immediately with reliable information and help in making important decisions.Taking the First StepIf you have not yet considered life care planning for yourself or a loved one, now is the time. Here are some steps you can take:Have open conversations with your family about care preferences and what if scenarios.Consult with an elder law attorney who offers life care planning services.Attend an educational workshop to learn more about how life care planning works.Meet the Client Care Advocate to understand how they can support your family.Our firm hosts monthly life care planning workshops at our York and Lancaster offices. These sessions are an excellent way to explore whether this approach is right for your family.Schedule Your Consultation With Bellomo & AssociatesWhile the COVID-19 pandemic was a difficult time for many of us, it also put a spotlight on the importance of long-term care planning. The reality is that preparation cannot be put off. Life care planning provides families with a roadmap to navigate the aging journey while protecting assets and ensuring loved ones receive quality care.If you would like to learn more about our life care planning services and meet our client care advocate, Meg Motter, LCSW, CDP, we invite you to attend one of our upcoming workshops. And if youre ready to start life care planning now, schedule your consultation with our elder law attorneys today. Were ready to provide you with the guidance and assistance you need to secure reliable elder care services in the future.
Oct 24, 2025
Estate Planning for Blended Families
Im Jeff Bellomo, an elder law and estate planning attorney at Bellomo & Associates in York and Lancaster, PA. Today, were going to explore a topic that resonates with many of you estate planning for blended families. Its a journey that touches the lives of our cherished income-generating couples, our beloved seniors transitioning to skilled nursing facilities, and our forward-looking young families. Lets delve into the intricacies and emotions of Estate Planning for Blended Families. Blended families are born from love that knows no boundaries. When two hearts unite, each with their unique family history and experiences, its a beautiful testament to the power of love and the promise of a new future together. However, it also comes with its set of complexities, especially when it comes to estate planning. Balancing the needs and desires of all family members is a delicate art, one that requires both financial finesse and emotional sensitivity.Estate planning for blended families involves careful consideration of assets, beneficiaries, and distribution. Its not just about dollars and cents; its about protecting the ones you love, no matter their biological or step relationship. One crucial aspect is updating your will to reflect your current situation. Clearly defining how you want your assets distributed and to whom, ensuring that no loved one feels left out or overlooked, is essential. Its about making sure your intentions are crystal clear, and your familys future is secure. Trusts as a Tool for HarmonyTrusts can be an incredible tool for ensuring harmony within your blended family. They offer privacy and efficiency and can be tailored to meet the specific needs of your unique family structure.Consider a trust as a way to protect assets for the benefit of both your spouse and your children. This can be particularly important when there are assets you wish to pass on to your biological children from a previous relationship. A trust can help ensure that your assets are distributed fairly, while also providing for your new spouse. The Importance of CommunicationEstate planning in blended families is not just about legal documents; its also about communication. Open and honest discussions with your spouse and family members can prevent misunderstandings and ensure that everyones concerns are addressed. Remember, an estate plan is not set in stone; it can be adapted and changed as your family dynamics evolve. By fostering an environment of understanding and open dialogue, you can navigate this journey with greater ease. Join Us at Our Estate Planning WorkshopIf youre in a blended family, I invite you to join us at our next estate planning workshop. Its a space to connect with others who face similar challenges and ask questions. Well guide you on critical next steps to create an estate plan that reflects your unique family situation.Together, we can help you build a legacy that ensures the security and harmony of your blended family, allowing your love to shine brightly in the generations to come.
Aug 16, 2024
Crisis Planning: What to Do If a Loved One Suddenly Needs Care
One hospital stay can change everything. One moment, your loved one is completely independent, and the next, you find yourself trying to make decisions that feel impossible. We meet families at Bellomo and Associates who walk through our doors overwhelmed, emotional, and scared. They are already too late to protect what their loved one built. When Crisis Hits Without WarningA daughter once shared a story that stays with us. Her mother had a stroke right before Christmas. One day, they were out shopping for gifts, laughing and planning their holiday dinner. The next day, she was in the ICU, and doctors were explaining that she would need long-term care. The daughter scrambled to gather documents, talk with hospital staff, and understand how Medicaid worked. She felt lost. Her mother had no plan in place, assets were all in her name, and the cost of care was more than the entire family earned in a month. They were convinced they would lose everything. When she finally reached out to our office, she learned something important. Even in a crisis, there are legal tools that can protect assets and help someone qualify for Medicaid faster and more safely. Most families have no idea these options exist until they are sitting in a hospital hallway trying to make decisions they never expected to face. Where Crisis Planning BeginsCrisis planning starts with gathering information. Someone needs to collect:Bank statementsProperty deedsIncome detailsInsurance policiesAny documents that show assetsMedicaid has strict financial rules, and knowing the full picture helps determine the best strategy. Next, call an elder law attorney right away. Timing matters. Even a few days of delay can limit what options are available. The Tools That Can HelpThere are Medicaid-compliant transfers and certain annuities that can sometimes be used in a crisis. These tools help convert assets into income or place them in a protected structure without violating Medicaid rules. But they must be used correctly. One misstep during the five-year lookback period can trigger penalties or delay benefits. Crisis planning is not something families should try to handle on their own. Applying StrategicallyOnce a strategy is set, the next step is submitting the Medicaid application with care. These applications require precision. Missing documents or unclear information can cause denials or long delays. A well-organized, properly prepared application helps ensure care is approved sooner. There Is Still HopeThe message we want families to hear is simple. Even if you did not plan ahead, there is still hope. With the right guidance, you can protect savings, secure the care your loved one needs, and find stability during one of the hardest moments of your life. If your loved one needs care now, do not panic, and call our office to see if were a good fit. (717) 845-8390
Dec 19, 2025

Time to Declutter
Years ago, my best friends parents passed away in an airplane accident. I vividly remember going to their house with my mother to bring food in the days following the incident. When we arrived, we saw four to six massive dumpsters outside of the house that were being filled and emptied on a very regular basis. A few weeks after our visit, I called my mom to check in on her. She made a comment that has always stuck with meshe could not believe that after years of collecting all those wonderful items, they all ended up in a dumpster. It was very eye-opening for my mother to see what occurs after a death. In her mind, and Im sure in many other peoples minds, those items have significant value to the family, and they will be forever cherished. The truth is most children dont have the room to take those items and their perception of sentimental value is not the same as it was for previous generations. Almost immediately, my mother started cleaning out all of the things she had been collecting. She became very picky about what she would keep. I did not realize at the time what a huge project she had undertaken until years later when she died. It still did take my father a long time to go through everything that remained, but I have no doubt that he was thankful that he didnt need the four to six dumpsters he would have needed, had my mom not started her own decluttering project years earlier. We encourage you to talk to your loved ones about starting to declutter and sort their items now. You will be grateful after they are gone, and it will make your job as the executor of the estate much easier. Remember, however, that it may be very difficult for seniors to part with some of their things. Dont push to the point of causing any type of conflict. Enjoy the time with your family while you are cleaning and downsizing, and hopefully, it will provide peace of mind for family members down the road.Please call us at 717-844-9639 and well set you up with a free consultation or register you for a free workshop.
Feb 02, 2024
Estate Planning During Uncertain Times
It is very easy with everything that is going on in our country and our world right now, to be concerned about the pandemic and start to think about your own mortality and planning. While we recommend planning at all times to always be prepared ahead of time, this certainly provides a reminder for us to stop and take a look at our current situation to make sure that we have at least our basics in place. Powers of AttorneyEach person should have a financial power of attorney that authorizes another individual to make financial decisions on their behalf in case they cannot. They could be unable to because of an illness or an incapacitation or simply just not in town, or maybe they are traveling out of the country. We cannot stress the importance of having a financial power of attorney in place to avoid the necessity for guardianship. We have discussed in detail in other blogs and articles about powers of attorney and guardianships, and we would encourage you to please take a further look at those, and why it would become important to have a financial power of attorney in place.A medical power of attorney is an essential document that authorizes another individual to make medical decisions on your behalf if you are not capable or able to make those medical decisions for yourself. Although there is a healthcare statute in the state of Pennsylvania that will name the next of kin to be able to make those healthcare decisions in case you cannot, we stress the importance enough of having this document in place to ensure that the people that you want making those decisions can make them without unintended people being named as well. When you reach the end-of-life stage it's also important that you have in place a living will. If the living will is coupled in one single document with a medical power of attorney, that is also considered an advanced healthcare directive. We recommend having these documents in place to ease the burden on your family. This will save them from having to make those end-of-life decisions if two qualified physicians put in writing that there is no realistic hope of recovery that you will always remain end-stage medical or vegetative, comatose, permanently unconscious, or terminally ill. There is certainly a lot that goes into the medical definition, but plainly stated, it is imperative to decide for yourself how you would like those decisions to be made rather than to put the burden on a loved one to feel like they have to play God or pull the plug on their family member. Review Your Current Documents, Including Beneficiaries, to Ensure They Meet Your Needs and Desires We encourage anyone who has planning in place to not assume that it is up to date or that it is what their current wishes are, things change over time. It is also important to review all of your beneficiary designations on accounts, such as life insurance policies, annuities, retirement accounts, etc. Often, the most overlooked item is reviewing the beneficiary designations of an account, and it is probably the most critical thing that can screw up an estate plan. Please make it a priority to review your documents to make sure they accurately reflect your wishes. If you have questions or need to make some changes we would be more than happy to see you at one of our workshops to discuss the different documents and how they can assist you and your family. We certainly understand if there is any anxiety or stress that you are experiencing but encourage you to be prepared no matter what, which will give you a sense of comfort and security. If you would like further information about this topic or to learn more about our firm, please visit us at www.bellomoassociates.com or call the office at 717-845-5390.
Nov 03, 2023
.png)
Family Involvement in Elder Law
As an estate planning and elder law attorney, I have seen a little bit of everything over the past 20 years. I am a big believer in having loved ones be part of the estate planning process to ensure that everybody is on the same page. Unfortunately, there are a few unscrupulous individuals whose objectives are to take advantage of their parents in one way or another. This does not change my opinion that estate planning and elder law are a team sport and that they should always include the financial advisor, the accountant, as well as the family. However, it is imperative that the professionals who are working with the individual stay vigilant and watch for signs of exploitation or abuse. Although it can often be very subtle, professionals usually have the skills and the tools to be able to see through it and bring attention to it. In an extreme case, a professional will contact the Area Agency on Aging and notify the Adult Protective Services division. They have authority under the Adult Protective Services Act to protect individuals in or around our community. However, that is definitely the exception to the rule, and in most cases, it is enough to have the family members leave the room and talk to the client alone to determine whether or not they are being unduly influenced or if they are speaking freely on their own. Most elderly individuals dont always realize what is occurring and therefore are not trying to hide it. They dont realize what is going on, so a trained professional can often ask the right questions to determine if something is not right. In the vast majority of cases, I do think that having family involvement in the elder law process is beneficial to everyone involved.
Jul 12, 2024
.png)
Moving Out of State?
Are you planning to move out of state? Bellomo & Associates, an estate planning and elder law firm based in York and Lancaster, Pennsylvania, is here to assist you. Our services cover everything from basic estate planning documents to asset protection and more. One common question we often receive is about the validity of documents when moving to a new state. Generally, if your documents were valid in the state where they were created, they should also hold validity in your new state. However, its crucial to remember that a confused mind may lead to complications. In many cases, it makes sense to consider redoing your documents according to your new states rules and regulations. Each state has its own specific requirements for documents like Powers of Attorney. If your new state has stricter or different requirements, you may encounter difficulties in having institutions accept your documents. While you may eventually prevail, it could be a hassle and time-consuming process. Let me share an example we experienced in the Commonwealth of Pennsylvania. A client moved from Arizona with documents deemed valid in Arizona at the time of creation. Despite having an affidavit from an Arizona attorney, we faced considerable difficulties in Lancaster County when attempting to accept the Will for probate. To avoid potential confusion and refusals to accept your documents, we strongly recommend updating your documents if you have the capacity to do so after moving. Although this might not be the technical rule, its a safer option for you and your family. Take the necessary steps to ensure your documents comply with your new states regulations. To learn more about estate planning and how to protect your assets, we invite you to join our free educational workshop. Register now and secure your spot!
May 24, 2024
What Is Medicaid Planning and When Should You Start?
Why Just Spend It Down Is Not a Real PlanYou have probably heard someone say, Just spend down the assets and apply for Medicaid. It sounds simple, almost like a final step once the money is nearly gone. If only it worked that way. In reality, Medicaid planning is a legal strategy that works best long before a crisis. Understanding how it actually works can make a meaningful difference for families who want to protect savings, reduce stress, and secure care with dignity. A Lesson Learned the Hard WayMaria learned this when her mothers health began to decline. She stepped in to help with appointments, medications, and finances. As the need for long-term care became clearer, someone casually told her not to worry. They said Medicaid would cover it once her mother spent down her assets. Maria assumed they had time. They did not. Because no planning had been done in advance, many of the legal tools that could have protected her mothers savings were no longer available. Medicaid reviewed her mothers finances, applied strict rules, and required most of her hard-earned savings to be spent on care before assistance would begin. What Maria thought would be a straightforward process became stressful, confusing, and emotionally exhausting. What Medicaid Planning Really IsMedicaid planning is the process of legally organizing income, assets, and property to help someone qualify for Medicaid while protecting as much as possible for a spouse or family. It is not about hiding money or doing anything improper. It is about understanding the rules and planning within them. Medicaid helps pay for long-term care, including nursing home care and, in some cases, in-home services. Unlike Medicare, Medicaid is needs-based. Eligibility depends on several factors, including:IncomeAssetsMarital statusTimingTo qualify, applicants must fall within strict financial limits. Some assets may be exempt, such as a primary residence under certain conditions, while others count toward eligibility. Income also matters, and if it exceeds limits, additional planning may be needed. Why Timing Matters So MuchMedicaid reviews financial transactions made in the years leading up to an application. This is known as the look-back period. Gifts or transfers made during this time can trigger penalties that delay eligibility. This is why last-minute planning often leaves families with fewer options and higher costs. By the time care is needed, many protective strategies are no longer available. How Planning Early Changes EverythingWhen Medicaid planning is done proactively, families often have far more flexibility. Early planning may help:Protect assets for a healthy spousePreserve funds for future needsReduce stress and uncertaintyAvoid costly mistakes and delaysCreate a smoother path to careMany people assume they will never qualify because they have too much, or that they will qualify automatically once money runs low. Both assumptions can lead to unnecessary financial loss. Medicaid eligibility is not automatic, and qualifying without a plan often means giving up far more than necessary. Planning Is About ChoiceMedicaid planning is not something you do when there are no options left. It is about making informed decisions while choices still exist. If you want to understand how Medicaid planning works and when to start, we are here to help guide you through it.
Jan 30, 2026
What Happens to Debts After You Die?
Heres something that surprises a lot of people: debt doesnt automatically disappear when someone passes away. When a loved one dies, families are already juggling so much: grief, paperwork, and tough decisions. Then the mail starts to pile up with bills, credit card statements, and possibly even calls from debt collectors. It can be overwhelming. Many people assume that those debts now belong to the family, but thats not the case. Understanding what really happens can help your loved ones avoid unnecessary stress and find peace of mind when the time comes. A Familys StoryAfter her father passed away, Sarah found herself sorting through piles of mail and paperwork. Her dad still had a mortgage, a car loan, and a few credit cards. Within weeks, letters started arriving demanding payment, and one company even called her directly, insisting she take care of the debts to protect the estate. Feeling scared and unsure, Sarah considered paying the bills herself just to make it all stop. When she finally sat down with an estate planning attorney, she learned something she wished she had known sooner: her fathers debts were his alone. His estate, not Sarah, was responsible for them. What she experienced happens to families all the time. The confusion, the fear, the pressure. But once she understood the process, she found relief and confidence to handle things correctly. Who Pays the Debts?When someone dies, everything they own and owe becomes part of their estate. The estate acts like a temporary financial container that holds all assets and liabilities until things are settled. Before anything is distributed to heirs, the estate must first pay legitimate debts. That means your estate pays your debts, not your family. The executor named in your will (or appointed by the court if you dont have one) is responsible for identifying and paying creditors according to the law. Theyll use estate assets to pay debts in a specific order before anything goes to beneficiaries. If there isnt enough money to cover everything, some debts are paid in full, while others may be reduced or written off entirely. Which Debts Take Priority?Not all debts are treated equally. Heres the general order in which theyre paid:Funeral and administrative expenses. Burial, funeral, and legal costs come first.Federal taxes. Any unpaid income or estate taxes must be handled before other debts.State taxes. Depending on where you live, state income or inheritance taxes may apply.Secured debts. Mortgages and car loans are tied to specific property.Unsecured debts. Credit cards, medical bills, and personal loans are paid last, if funds remain.If the estate runs out of money, unsecured creditors often receive only partial payment, or nothing at all. What Happens to Specific Types of DebtMortgages: The property doesnt automatically go away with the debt. The home can be sold to pay off the loan, or an heir can take over payments to keep it.Car Loans: Similar to a mortgage, the estate can sell the car, or an heir can refinance and continue payments.Credit Cards and Personal Loans: These are unsecured debts and are only paid if money remains after higher-priority debts.Medical Bills: Providers can file claims against the estate, but these are often last in line for payment.Taxes: Federal and state taxes must be paid before assets are distributed. Executors can even be held responsible if taxes are ignored.Student Loans: Federal student loans are usually forgiven after death, but private loans may not be.What About Co-Signed or Joint Accounts?If you co-signed a loan or shared a joint account, youre still responsible for that debt after the other person passes away. Lenders can require you to continue making payments. For joint accounts, the surviving account holder typically becomes fully responsible for the remaining balance. This is why co-signing loans should always be done with care and understanding of the long-term impact. Are Family Members Personally Responsible?In most cases, no. Family members are not personally responsible for a loved ones debts. Creditors cannot demand payment from children or spouses unless they co-signed the debt or live in a community property state. Even then, there are legal protections. If collectors start calling, remember: under the Fair Debt Collection Practices Act, creditors cannot harass or pressure family members into paying debts that arent theirs. What If Theres No Money Left?If the estate doesnt have enough money to pay everything, its called an insolvent estate. Debts are paid in order of priority, and once the funds run out, the rest are written off. Family members are not required to use personal funds to pay the difference. The process may take time, but its designed to resolve things fairly and protect surviving loved ones. Why Planning Ahead MattersKnowing how debts are handled is one thing; planning for them is another. A good estate plan can save your family months of confusion and worry.Heres how:Organize your assets and liabilities in one place.Name a clear executor or trustee.Make sure accounts and policies have up-to-date beneficiaries.Use trusts to streamline administration and reduce exposure to creditors.Provide written instructions for how debts should be settled.Without a plan, the process can drag on, cost more, and leave your family feeling overwhelmed. At Bellomo & Associates, we help families understand and prepare for every part of the estate process, including what happens to debt, so your loved ones can move forward with confidence, not confusion. The Bottom LineDebt doesnt disappear when someone dies, but it doesnt become your familys burden either. Your estate handles it, and what remains is passed on to your heirs. By planning, you can protect your family from unnecessary stress and ensure your wishes are carried out with clarity and care.
Nov 21, 2025
.png)
Nurturing Harmony in Caregiving: Open Communication and Conflict Prevention
Caring for aging parents involves crucial decisions regarding who will provide the necessary care and in what setting. However, these decisions can often give rise to conflicts among family members, particularly when one sibling assumes the role of primary caregiver. Through our work with clients and families, we frequently encounter these stressful and emotionally charged situations, creating a perfect storm for family disputes and distress.Reflecting on recent consultations with families, it becomes apparent that a key factor contributing to conflicts is the failure of aging parents to openly express their wishes and expectations regarding potential scenarios. When parents do not communicate their desires early and consistently, adult children are left to speculate about their parents preferences, leading to differences of opinion and sibling conflicts. To prevent such difficulties, we urge you to initiate conversations with your adult children about what if scenarios and discuss your wishes and preferences openly. This proactive effort can serve as your conflict prevention plan, saving you and your loved ones from engaging in conflict resolution in the future.In situations where a family member becomes a paid caregiver, it is essential to establish a formal caregiver agreement. This agreement serves multiple purposes, including clarifying the financial aspects of the care being provided. By having a caregiver agreement in place, you can prevent misunderstandings and promote a harmonious caregiving environment within your family. It ensures that everyone is on the same page and understands the expectations and parameters involved.Above all, open and honest communication is the key to fostering understanding and preventing conflicts among family members. We strongly recommend engaging in conversations early and frequently to address concerns, preferences, and potential challenges that may arise in caregiving situations. By doing so, you can promote a supportive and respectful environment where everyones needs are acknowledged and considered.At Bellomo & Associates, we believe in nurturing harmony within families facing caregiving challenges. Our experienced team is dedicated to providing comprehensive estate planning and elder law services that cater to your unique circumstances. Start the conversation with your adult children today, discussing your wishes, expectations, and potential what if scenarios. Visit our website to learn more about how we can support you and register for our free educational workshop. Let us help you pave the way for peaceful resolutions and a smoother caregiving journey.
Apr 26, 2024
Caregiver Agreements and Considerations.
Caregiver agreements are often used in the Medicaid context so that a family member can be paid for their services to a loved one and the payment would not be considered a gift.In the Medicaid context, payments to family members are considered to be a gift for love and affection, unless there is a clear agreement written prior to services being rendered, preferably signed by the parent receiving the care as well as the child giving the care.The caregiver agreement will set forth all of the terms of the transaction, including what services will be provided, where will they be provided, how will they be provided, and other typical contract languages.The significance of this agreement is that the Department of Human Services (DHS) will look at the transaction as an arms-length transaction between third parties and not among family members.This means that the payments to the child will not be considered a gift, and, therefore payments will be allowed to be counted as a for value transfer as part of a legitimate spend-down and not a gift that will trigger a penalty period for Medicaid purposes.The biggest question that arises in regards to caregiver agreements is what the parent should pay for services. This is often a very difficult question because there are certainly competing interests at stake. For the parent receiving the care, they genuinely would like to pay full market value and as much as they can without there being a penalty created. This will legitimately reduce the value of their estate, but benefit the child who is providing services for their care on a daily basis.On the other hand, if there are other children who are not providing the care they often feel slighted or that the other sibling is receiving more than their fair share.This is very difficult because the children who are not providing the care want the amount to be paid to be the least amount possible to potentially raise the amount that will be left for them and their siblings to share.However, if the parent does not spend down their assets legitimately, the money can be lost to long-term care costs, and there may not be anything left for anybody.This inheritance rub is one of the most difficult things involved with a family caregiver because of the potential conflict that it may create among the family members.At the end of the day, fair market value is generally set in, in this context, by what other professionals and people are charging for similar services. As long as you can stay within the realm of what others are charging for similar services, the Department of Human Services will not raise a red flag. However, that does not mean that other children or other family members may not question the motives of their family member providing the services and the amount of the payment.We believe it is important to have all parties abreast of the information and informed so that we can potentially avoid unwanted conflict in the future. We always advise the advice of a professional to assist with these potential implications, and ensuring that the agreements are written properly to comply with DHS and Medicaid standards.If you are looking for advice in regards to estate planning, please call our office at 717-844-9639 or click the link here and we will contact you.
Apr 19, 2023
Thank You All For Supporting Our Walk to End Alzheimers
Since my first day with Bellomo & Associates, our team has been a part of the Walk to End Alzheimers. Over the years, it has come to mean so much, not only to me, but also my family and even my neighbors! My daughter especially loves the walk. One year, she represented the symbol of hope; hope to find a cure for Alzheimers.During the pandemic, when everything was virtual, the Alzheimers Association produced the Walk Everywhere. This made it possible to still have this tradition remain in tact for my family. It was such a relief to have a sense of normalcy! Bellomo & Associates, we have several team members that work remotely, the Walk Everyone also allows them to participate!In all my years of participation, the most rewarding moment was when my family had just completed the walk in our neighborhood, using our app to track. We crossed the finish line holding our flags high when my neighbor was waiting to ask what we were doing. We explained that we were participating in our one of our favorite events, the Walk to End Alzheimers. He then told us that he had lost a parent to Alzheimers and he was touched that we were walking and raising awareness. After chatting for a bit, I decided to give him one of our flags. To this day, that neighbor has his Alzheimers Association flag proudly displayed in his front yard in honor of his lost loved one.
Apr 05, 2023
How Can I Avoid Probate?
A week probably does not go by in my estate planning and elder law practice that I do not hear this question. We spend a lot of time in our weekly workshops in our office answering this question and also much of our time during our free consultations also discussing this in detail. I believe that the major reason why people make this their primary question is because of a lot of information that is out in the mainstream, the media, from national companies or national spokespeople who often urge people to avoid probate at all costs.I was very fortunate several years ago that I was able to travel the country training and teaching lawyers all over the country. It was an extremely enjoyable experience and I learned and grew tremendously from it. One of the main things that hit me during my time educating and teaching is that each and every state in the country has very different rules.Most attorneys are only licensed in one state and typically do not get licensed in multiple states because of the exams and costs that are associated with it. It became very clear to me over the years that each state is very different in regard to its probate rules as well as how difficult probate is.Many of the national trust companies and national spokespeople live and come out of states where the probate process is very burdensome, overwhelming, arduous, confusing, expensive, and time prohibitive. In those states, it makes a lot of sense to take steps in order to be able to avoid probate so that their clients do not have to go through those processes and spend the time and cost involved with it.Several very good business individuals understood what a valuable opportunity it could be for them to be a spokesperson or to advertise living trusts and other opportunities to avoid probate. Rather than take the time to research each states rules, they make blanket statements and characterizations that seem to apply to every state but in reality do not.Yes. There are certainly ways to avoid probate, and if the situation is correct, we will often make recommendations to do things such as creating a trust or having access jointly owned with another individual, or using beneficiary designations on accounts. In our workshops, we spend a lot of time talking about these and many other opportunities to avoid probate and how to take advantage of them.My concern is that without proper advice and guidance, oftentimes these tricks and solutions often arent necessary and can be overkill.If you are interested or believe that you are interested in avoiding probate for the sake of avoiding probate, please come to one of our upcoming workshops to learn not only about probate but also about the options that we would use to avoid probate and the pros and cons of those.It is imperative that people be provided good advice in regard to this and any implications and complications that could come from decisions that are made. Remember, in Pennsylvania avoiding probate does not equate to avoiding inheritance tax.If you would like to learn more, please give our office a call at 717-844-9218.
Aug 04, 2023
My Spouse Died, Am I Liable for his/her Debts?
As estate planning and elder law attorneys, we receive this question all of the time. As a general rule of thumb, the answer is no, you are not liable for the debts of another individual. However, there are some exceptions to that general rule, which is why it is essential to seek professional advice when a loved one passes, especially a spouse who had debt in his or her name alone.For example, there are a few situations where a spouse would be liable for the debt of a spouse, and they are a few of the following:1. If a spouse co-signs on a loan for a spouse, then they also own the debt.2. If a spouse is a joint account holder of a credit card with their spouse, then they are also liable for the credit card as a joint owner.3. If a spouse has jointly owned property, and that property has a liability, then the joint owner would as well.These exceptions are obviously pretty clear, which all point to the situation where the spouse is either an owner or co-signed for the debt one way or another.However, in the State of Pennsylvania, there is a doctrine called The Doctrine of Necessities. Essentially, it provides that a spouse is liable to provide for the necessities of their spouse. While this is certainly not a doctrine that is used all the time, it is possible that a spouse could be held liable for their spouses debt that was incurred prior to death if it is deemed to be a necessity and is deemed that the spouse has a duty to support the other spouse.Although this is rare, it is definitely something not to overlook and, again, is why we recommended that you seek legal counsel when a spouse passes away to make sure that everything is taken care of properly and that you dont assume any personal liability for any inadvertent omissions.Please, if you have any questions or concerns about your financial future should your spouse die, contact us at (717) 844-9218 or fill in our contact us form and well get back to you.
Jun 30, 2023
My Loved One Will Stay Home Forever
This is a statement that we hear on a regular basis in our office when we talk about aging and potentially needing assistance for our loved ones in the future. Most people, if asked, would choose or want to stay home as long as they possibly can. We often are abruptly interrupted when we start talking about alternatives such as assisted living facilities or personal care homes or long-term care facilities.It is certainly admirable to want to stay home as long as possible and there are a lot of things that can be done to help ensure that that can occur. The time to start discussing what it is going to look like for a loved one to stay home is now. Take a look at the house and the configurations of the house to determine if it is suitable and adaptable to allow somebody to age there. Is there a possibility of putting ramps in or having a stair lift installed to assist with getting up and down steps within the home. Are there appropriate handrails or grab bars in bathrooms and other places. We highly recommend that you ask a geriatric care manager to come to your home to assist with evaluating its adaptability and suitability for people as they age.If you find yourself in a situation where a loved one needs care now, we highly recommend that you look at non-medical options to have someone come into the persons home to assist them with their needs. Non-medical options are plentiful in the York and surrounding areas and allow families to know that their loved ones will have a companion during the day and potentially get reminders throughout the day about taking medication, going to the restroom, or getting meals. Oftentimes all that people need is simple reminders and someone just taking a look to make sure that they are remaining safe in their home. If the situation gets worse and the individual begins to need medical care we are also very lucky in our area that we have several medical options for care in the home. I would highly recommend that you research both the medical and non-medical options in our area to see how plentiful and wonderful these companies are.As a person ages in place, and as their care needs increase, sometimes it is impossible to have somebody continue to remain in their home because it may become unsafe. There are certainly a lot of options before this becomes a possibility but if a person begins to wander from the home or if the home is not able to be adapted to be safe for them we may have no choice but to move them into another type of setting. However, with proper planning and assistance from outside companies and family members it is possible to age in place in your home for a long time. We highly encourage you to have these conversations ahead of time so that youre not having them in a crisis situation which makes the conversation much more difficult.If you would like to learn more about estate planning and elder law, please give our office a call at 717-844-9218.
Jun 23, 2023
Guardianship vs. Power of Attorney: Whats the Difference?
When a Loved One Cant Make Decisions, Who Steps In and HowThis question usually comes up during stressful moments. A medical emergency. A new diagnosis. A sudden decline no one saw coming. Families often believe they already have the right paperwork in place, only to learn too late that what they planned for is not what the law allows in that situation. Sarah and Tom learned this the hard way. A Story Many Families RecognizeTheir adult son had special needs but lived a fairly independent life. Years earlier, Sarah and Tom worked with an attorney and signed documents they believed would protect him, including a Power of Attorney. They felt confident that if anything ever happened, they would be able to step in and help. Then their son experienced a serious medical crisis. When doctors asked for legal authority to make decisions, the hospital explained that the Power of Attorney was not enough. Because their son could no longer understand or legally grant authority at that point, the court required guardianship. What they expected to be a smooth process turned into months of court hearings, paperwork, and emotional strain during an already painful time. Why This HappensPower of Attorney and guardianship are often confused because they both involve helping someone who cannot make decisions. But they apply in very different situations. What a Power of Attorney DoesA Power of Attorney is created voluntarily by a capable adult. It allows someone to choose who will make financial or medical decisions for them if the need ever arises. The key requirement is capacity. The person signing must fully understand what they are doing and agree to give that authority. When done properly and at the right time, a Power of Attorney can help families avoid court involvement altogether. What Guardianship IsGuardianship is very different. It is ordered by the court when a person can no longer make decisions for themselves and has not legally granted authority in advance. Guardianship removes certain decision-making rights and places ongoing oversight under the court. While it can be necessary in some situations, it often involves:Court hearingsOngoing reporting requirementsLegal feesEmotional stress for the entire familyWhy Planning Makes Such a DifferenceThis is where early and thoughtful planning truly matters. An experienced elder law attorney helps families understand:When a Power of Attorney is enoughWhen guardianship may be unavoidableHow to plan to reduce court involvementWhat to do if capacity begins to declinePlanning early gives families more control and fewer surprises when life changes. Choosing the Right PathThere is no one-size-fits-all answer. The right approach depends on capacity, timing, and the individuals specific needs. Assuming one document will cover every situation often leads to stress that families never expected. If you are unsure which option your family needs, it is worth having the conversation before a crisis forces one.
Jan 16, 2026
Finding and Sharing Joy
We hope you enjoy this special blog by Meg Motter, Client Care Advocate for Bellomo and Associates:Jump for joy! Joy to the world! Enjoy.The word joy surrounds us, yet many struggle to find it. The daily grind and lifes burdens try to steal our joy, and noses buried in cell phones rob us of countless opportunities to bring joy to those passing by.My father loved to sprinkle joy on strangers. His Harbor Tunnel commute provided his favorite opportunities, as he cheerfully greeted tollbooth operators by name, determined to transform their day. So, I guess you are wondering why I called this meeting, he would bellow to break awkward elevator silences. He delighted in asking passersby, How many times did Mr. Opporknockity have to tune the piano, grinning as he revealed, Opporknockity only tunes once!I inherited the joy sprinkler gene, looking daily for opportunities to bring joy to those around me. What fun it is encouraging random folks to join me in singing Happy Birthday, often for a person not actually celebrating his birthday.Nothing beats a quarter left in the Aldi cart for the next shopper, the look of relief on a mamas face as I hold the door for their stroller, or my cheerful and sympathetic greeting to the not-so-patient hubby waiting for their bride to finish shopping.Research has proven that positive thinking, laughter and socialization improve ones physical and emotional well-being. Volunteerism, random acts of kindness and making a difference in the lives of others reaps double benefits, improving well-being for the giver and receiver.Try a warm hand-off delivery of your neighbors poorly aimed newspaper. Try encouraging the seemingly miserable store cashier. Try to strike up a conversation with the lonely person in the waiting room. Purpose yourself to be a joy sprinklertrust me, it will be a win for both of you!
Mar 31, 2023
Why Improper Planning For A Child With A Disability Can Be Catastrophic
Most people go through life and do not often think about planning for the future and what that might look like. Oftentimes, when people finally get around to planning, they dont take the necessary time to truly understand the intricacies and the consequences of decisions but rather want to get something done for the sake of being done.An individual with a disability who is receiving public benefits from the government cannot receive an outright inheritance or they will lose their entitlement to their government benefits. However, many parents do not completely understand this concept and since they have three children, theyre going to provide for their children equally regardless. It is imperative if you have a child with a disability or special needs that you seek expert counsel in order to fully understand what the implications of giving money outright to that individual could be now and in the future.It is very easy and straightforward to be able to provide for an individual with a disability by placing money in a special needs trust. This will allow that individual to continue to receive the money from the parent but also receive the government benefits that theyre currently getting. This is my example of having your cake and eating it too. While not necessarily overly difficult, it is essential that you work with an estate planning and elder law attorney who does special needs trust on a regular basis. There are many easy pitfalls that someone can fall into and it is easy to make a mistake in this arena. If you have a special needs child, please take the time to fully understand how you can protect that individual and the inheritance in the future as well as still provide them any government benefits that they may be entitled to.If you would like to learn more about special needs trust planning, please contact the office at 717-844-9218, to learn more about our workshop for families with individuals with disabilities and how to plan for them. We look forward to seeing you in the future.
May 17, 2023
.png)
The Perils Of DIY Estate Planning
Estate planning is a crucial process that ensures the security of your family and assets when you pass away. However, many people are tempted to handle the task themselves using do-it-yourself (DIY) websites or forms. While these options may seem convenient and cost-effective, they can lead to numerous mishaps that can cause legal and financial problems for you and your loved ones.One major issue with DIY estate planning is that the forms are not tailored to your state-specific laws and regulations. Many people dont realize how specific estate planning documents can be, down to the notarization process. DIY websites and forms assume that you know the answers to legal questions, but they dont provide the knowledge or expertise that an experienced attorney can offer.Weve seen cases where DIY estate planning forms have led to costly mistakes. In one instance, a child lost hundreds of thousands of dollars in government benefits because the form did not include language for special needs planning. This mistake could have been easily avoided if an experienced estate planning attorney had been consulted.In another case, estate proceedings were delayed for four months because the forms were not notarized properly. A self-proving Will would have ensured that the document was legal and saved time and money. Unfortunately, the individual who was the notary was unavailable, and the estate faced several complications as a result.At Bellomo & Associates, we strongly advise against DIY estate planning. Its essential to take estate planning seriously and seek the expertise of a professional who specializes in this area of law. Our attorneys can provide personalized guidance and ensure your estate plan is tailored to your needs and state regulations. By investing in a professional, you can protect your family and assets and avoid costly mistakes in the future. If youre interested in learning more about estate planning, we invite you to visit our website to register for one of our upcoming workshops.Our knowledgeable attorneys will provide valuable insights and answer any questions you may have. Dont wait until its too late to plan for your familys future. Register today and take your first step towards ensuring peace of mind for you and your family.
Mar 15, 2024
Wills vs Trusts: Which is Right For You
In our tranquil corners of the world, where generations build legacies, we often find ourselves at a crossroads one that leads to choices that impact not just our finances but our familys future. Today, lets journey together and explore the age-old question: Wills vs. Trusts. Which path is right for you?The Legacy of Love and SecurityFor many, this journey begins with the dawn of financial stability. As your hard-earned assets grow, so does the desire to protect and secure them. Its not just about the numbers; its a promise of love, devotion, and the legacy you intend to leave behind.A well-crafted will is like a love letter to your family. It ensures that your assets are distributed according to your wishes, providing your loved ones with the financial security they deserve. It offers peace of mind, knowing that your legacy is well-guarded.Yet, here in York, we understand that privacy and efficiency matter, too. This is where trusts come into the picture. A revocable living trust, for example, offers the privilege of sidestepping the often lengthy and public probate process. With a trust, your assets are distributed privately, sparing your loved ones from unnecessary stress and public scrutiny.Embracing the Golden Years with GraceNow, lets consider the beautiful chapter of our lives when we move gracefully into our golden years. For many seniors, the prospect of skilled nursing facility care can be daunting, both emotionally and financially. Its a time when you want to ensure that your lifetime of hard work doesnt disappear in the blink of an eye.Wills and trusts play pivotal roles in Medicaid planning. But when it comes to securing your legacy while obtaining Medicaid benefits, trusts, particularly irrevocable trusts, can be life changing. These trusts enable you to preserve a legacy for your heirs, all while qualifying for Medicaid Assistance. This decision is more than just financial; its about preserving dignity and providing your loved ones with the peace and security they need during this chapter of life.Building a Strong Foundation for the FutureAnd for our young families, life is a whirlwind of dreams and aspirations. Amid all this, you must ensure your childrens future is secure. Your primary concern is their well-being, their dreams, and their security.Wills are the fundamental pillars of estate planning. They allow you to name guardians for your children, should the unthinkable happen. Its a promise that their future will be safeguarded.But, for those who seek to go above and beyond, revocable living trusts can provide an additional layer of protection. These trusts help you manage your assets efficiently, ensuring a seamless transition for your children if something were to happen to you. Its about laying a foundation for their future, one built on love, security, and opportunity.The Choice is PersonalThe choice between wills and trusts is deeply personal. It depends on your unique circumstances, your familys needs, and your dreams for the future. No matter where you are on your lifes journey, were here to guide you, to connect your hearts desires with the path you choose.This isnt just about assets; its about your legacy of love, security, and dreams fulfilled. Were here to help you make the right choice for your family, and together, we can build a legacy that will stand the test of time.
Feb 12, 2024
Moving On Help for Seniors Relocating to Nursing Homes or Assisted Living Facilities
In my estate and elder law practice, I routinely provide advice to seniors and their families about the next step. Specifically about what they will do when they need more care in their home or in an assisted living facility or in a nursing home.Nobody ever wants to have to be relocated as we all wish that we could just reside in our homes until we pass. However, this is not always the case, and having a plan in place, preparing you and your loved ones for what it will look like to have to move will reduce the amount of stress and burden on your family tremendously.The most important piece to all of this is for the entire family to be on the same page and to have open and honest conversations with each other. All too often, families dont have difficult conversations with the hopes that those decisions or that heartache will simply just go away if they ignore it.My experience is that that is never the case. But, ultimately will only provide more heartache and more stress that could easily be avoided if the family has conversations up-front before it is necessary.I am always amazed at the assistance and guidance that assisted living facilities, personal care homes, and nursing homes provide to their potential residents. The number of resources and guidance that they can provide is astronomical and should definitely not be underestimated or overlooked.Take advantage of any and all resources that are made available. But, if you have not yet made the final decision as to where you may want to move and cannot tap into the resources of a specific facility, there are definitely resources in and around our community that will not only assist you with the preparation of your current home for sale and how to receive the highest top dollar but also what to expect when moving and what should you take or leave behind. We found one resource here on 7 Best Moving Companies to support you or your loved ones. Sometimes paying for a service to take away from the overwhelm can be incredibly valuable and provide peace of mind.Although these seem like very simple ideas and issues they really arent, and thinking about them in advance can save you and your family a lot of headaches. Tap into your local resources to assist you with the move itself as well as how to get the new place put together and looking and feeling like home. Spending a little bit of money in order to be able to get your new home feeling like your old home cannot be underestimated.If we can be of any assistance or answer any questions while you make decisions about long-term care, please give us a call at 717-844-9218.
Jun 08, 2023
What Happens If You Become Incapacitated Without a Power of Attorney?
It often starts with an ordinary day. A phone rings on a Tuesday morning, and in a single moment, everything changes. A daughter hears the words no one is ever ready for: her father has suffered a stroke. Within hours, she is sitting beside his hospital bed, frightened and overwhelmed. He is alive, but he cannot speak clearly. He cannot sign documents. He cannot explain what he wants. For years, he had been the one handling everything. He paid the bills, managed the accounts, and made the decisions. Now, when his family needs answers the most, they are left without a clear path forward. What feels like it should be simple quickly becomes anything but. The bank will not talk to her. The mortgage company will not accept her instructions. Doctors need decisions, but no one can confirm who has the legal authority to make them. In the middle of a medical crisis, the family runs into a painful truth that many people do not think about until it is too late. Without a power of attorney, love alone is not enough. This is one of the most overlooked parts of estate planning. Many people assume estate planning only matters after someone passes away. In reality, incapacity is often the first crisis a family faces. It can happen in an instant through an accident or stroke. It can also happen slowly through Alzheimers disease or another serious illness. However it happens, the result is the same. Someone needs to step in and help. The problem is that without the proper legal documents, even the people who care the most may not be able to act. A durable power of attorney is meant to prevent this kind of situation. It allows you to name a trusted person to handle your financial and legal matters if you become unable to manage them yourself. That authority can include paying bills, accessing accounts, managing property, handling insurance matters, and dealing with government benefits. That word durable is important. A basic power of attorney may no longer be effective once incapacity occurs. A durable power of attorney is designed to remain in place during the very time it is needed most. It continues to work when you cannot. Without that document, families are often left in limbo. Many people are surprised to learn that spouses and adult children do not automatically have the authority to act on someone elses behalf. Financial institutions, insurance companies, and government agencies must follow strict privacy and authorization rules. Even when the situation is urgent, they usually cannot make exceptions simply because a loved one is asking for help. That means bills may go unpaid. Important accounts may be inaccessible. Decisions may be delayed when time is already in short supply. Medical decisions can become just as difficult. A health care power of attorney allows you to choose someone to make medical decisions if you are unable to communicate your wishes. Without one, doctors may have to rely on state law to determine who can act for you. While the law may provide a list of possible decision-makers, that list may not reflect your family dynamics, your closest relationships, or your personal preferences. In some families, this leads to confusion. In others, it can lead to conflict. More than one person may believe they should be the one making decisions. What should be a time of support and care can quickly become tense and uncertain. When no power of attorney is in place, families are often forced into a court process just to move forward. That process is usually called guardianship or conservatorship. It allows a judge to appoint someone to make decisions for an incapacitated person. Sometimes it becomes necessary, but it is rarely easy. It often involves legal paperwork, medical evidence, court hearings, and added expense. It can also take valuable time at the exact moment a family feels they have none to spare. Perhaps most importantly, it takes the decision out of your hands. Instead of you choosing who will act for you, the court makes that decision. The person appointed may be subject to ongoing court oversight, reporting requirements, and limitations on what they can do. A deeply personal family matter becomes a formal legal proceeding. At Bellomo & Associates, we have seen how heavy this burden can feel for families. The stress is not only financial or legal. It is deeply emotional. People are already trying to cope with a frightening health event, and suddenly they are also navigating rules, roadblocks, and decisions they never expected to face. The good news is that much of this can be prevented with thoughtful planning. Creating a power of attorney is not about giving up control. It is about protecting it. It gives you the chance to decide, in advance, who should step in if you are unable to act for yourself. It allows you to define that persons authority and put safeguards in place so your wishes are respected. It also gives your family something priceless in a moment of crisis: clarity. There is also a very human side to this conversation. Incapacity is not just a legal issue. It touches dignity, independence, and peace of mind. Knowing that someone you trust can step in without unnecessary delays can lift a tremendous weight from the people who love you. It allows them to focus less on obstacles and more on care, support, and being present. At Bellomo & Associates, that is exactly why planning matters. A good plan is not just a set of documents sitting in a folder. It is a practical way to protect your voice, your wishes, and the people you care about most when life takes an unexpected turn. That daughter in the hospital room should not have had to fight her way through paperwork and resistance just to help her father. With a power of attorney in place, she could have stepped in right away. She could have handled urgent matters, spoken with the right people, and focused her energy where it belonged: on her fathers well-being. That is the difference planning can make. Incapacity planning is one of the kindest and most practical gifts you can give your family. It helps ensure that your wishes are honored even if you cannot speak for yourself. It gives the people you trust the legal ability to act when it matters most. If you are not fully confident that your current plan would work in real life, now is a good time to take a closer look.
May 19, 2026

Spendthrift TrustsHow and Why They Can Protect Your Family
Spendthrift Noun: a person who spends money in an extravagant, irresponsible way. Most parents want to provide for their children, but they want to ensure that the children cannot squander the money or have it taken from them by an unwanted creditor. The benefit of Spendthrift Trusts is that only the child can benefit from the money that is placed in the trustcreditors cannot access the funds, nor can the individual use the funds to make unwise decisions. Some parents tell us that they do not want to control from the grave. The more I learn about their situations, the issue at hand is not control, but rather it is protection that they seek. Protection to ensure that an unwanted creditor cannot take money, as well as protection so that no one makes a decision they will later regret. Either way, these types of trusts are very common and extremely valuable in protecting the money for the child alone, and no one else. If you have an individual that you think could benefit from this type of planning, please let us know by reaching out to us at 717-845-5390 or signing up for one of our free weekly workshops!
Aug 02, 2024

How Can I Avoid the Skilled Nursing Facility?
This is the question that we get regularly in our law firm and before having our Life Care Planning program and Client Care Advocate, Meg Motter, a licensed clinical social worker on board, my answer was always that it is not something that you can plan for. I believed it to be a decision that was out of your hands. As I have embraced the Life Care Planning model of assisting clients and their families, Ive come to realize that those answers and beliefs were probably incorrect. Im learning through watching Megs work unfold that much can be done well in advance of crisis times to proactively plan for aging in place and avoid entering a skilled nursing facility for long-term care.Now, my answer would be to at least attend one of our monthly Life Care Planning Workshops, take advantage of the free one-on-one Life Care Planning vision meetings with Christine Oyler, and consider retaining the law firm for Megs services to assist you and your family in developing your very own Life Care Plan. There are ways to pay for in-home care and set up other situations that would certainly provide a much better chance of staying out of the nursing facility. Working closely with your Client Care Advocate through your one-year contract with Meg to determine your goals and wishes, research and secure services to assist you in remaining in the least restrictive setting of your choosing, and put those services in place is the answer. Planning is a necessity to avoid the nursing facility and starting early ensures the greatest success. Sure, we can help in the crisis, but starting your Life Care Planning journey before the crisis hits is all the better.If youd like to learn more about Life Care Planning and meet our Client Care Advocate, Meg Motter, LCSW, CDP consider attending one of our monthly Life Care Planning Workshops. Please reach out to the office at 717-208-4546 for more information.
Jan 31, 2025
Planning for Long-Term Care Without Losing Everything
One of the biggest fears families share, often quietly, is this question: What happens if I need long-term care and it wipes out everything I worked for? We hear this concern often at Bellomo & Associates. Long-term care planning is not just about aging or preparing for the worst. It is about protecting independence, dignity, and the financial stability of the people you love. Unfortunately, many families do not start planning until a health crisis forces decisions to be made quickly. By then, options are limited and stress is high. The good news is that with the right information and proactive planning, it is possible to plan for long-term care without losing everything. Why Long-Term Care Planning Matters More Than Ever The need for long-term care is far more common than most people expect. More than half of adults over age 65 will require some form of long-term care during their lifetime. For many families, that care lasts longer and costs more than anyone planned for. Long-term care expenses add up quickly. Whether care is provided at home, in assisted living, or in a nursing facility, costs can reach thousands of dollars each month. These expenses often increase faster than general inflation, placing growing pressure on retirement savings and household income. Planning ahead does not mean assuming the worst will happen. It means preparing for a realistic possibility and preserving choices when they matter most. The Biggest Misconception: Medicare Will Cover It One of the most common and costly misunderstandings we see is the belief that Medicare will cover long-term care. Medicare does provide limited coverage for short-term skilled care, such as rehabilitation after a hospital stay. What Medicare does not cover is custodial care. This includes help with daily activities like bathing, dressing, eating, or moving safely. For many people, this is the type of care they need the most. Families often discover this reality only after a loved ones rehab benefits end and the bills begin arriving. At that point, care quickly becomes an out-of-pocket expense that drains savings faster than expected. Understanding this distinction early is critical to realistic long-term care planning. What Losing Everything Really Means When families talk about losing everything, they are rarely talking about luxury items. They are talking about retirement savings, the family home, financial security for a surviving spouse, or the ability to help children and grandchildren. Long-term care costs often create a slow financial drain. Savings are spent down month after month. Income that once supported a comfortable retirement is redirected entirely to care. Without planning, families may be forced into decisions that limit both care choices and financial stability. Planning is not about hiding assets or cutting corners. It is about protecting quality of life and preserving options. How Long-Term Care Is Actually Paid For Understanding how care is typically paid for helps families see where planning fits in. Paying Out of Pocket Many families start by paying for care using savings, pensions, Social Security income, or investment distributions. This approach may work for short-term needs, but long-term care often lasts longer and costs more than expected. Family Caregiving Family members frequently step in to provide care. While this can reduce costs, it often comes with a significant emotional, physical, and financial toll. Caregiving can affect careers, personal health, and family relationships. Even the most dedicated caregivers eventually need support. Medicaid as a Safety Net Medicaid is the primary payer for long-term care in the United States. However, it is a needs-based program with strict eligibility rules. Qualifying often requires spending down assets, and many families are caught off guard by how complex these rules can be. This is where planning ahead can make the biggest difference. Key Medicaid Rules Families Need to Understand Medicaid planning is not something to approach casually or at the last minute. Some of the most important rules include: The look-back period, which reviews asset transfers made before applying Transfer penalties, which can delay eligibility Estate recovery, where the state may seek reimbursement after death Special rules for married couples designed to protect a spouse who remains at home These rules are complex, but they are also predictable. Families who plan early have more legal and ethical options than those who wait until a crisis occurs. Smart Strategies to Plan for Long-Term Care Without Losing Everything Start Planning Before a Health Crisis The earlier planning begins, the more options are available. Early planning allows families to make thoughtful decisions instead of reacting under pressure. Plan for Care First, Then Finances Start by discussing preferences. Would care at home be ideal? Is assisted living acceptable? Who should make decisions if you cannot? These answers help guide the financial strategy. Use Insurance Strategically Long-term care insurance or hybrid insurance products can help offset future costs for some families. These tools are not right for everyone, but when they fit, they can significantly reduce financial risk. Consider Legal Planning Tools There are legal strategies that may help protect certain assets while still planning for care. These strategies must follow the rules and depend heavily on timing and individual circumstances. Professional guidance is essential. Do Not Overlook Veterans Benefits Veterans and surviving spouses may qualify for benefits that help pay for care, including Aid and Attendance. These benefits are often overlooked simply because families are unaware they exist. Real-Life Scenarios Show the Difference Planning Makes Families who plan early often retain more control over where and how care is provided. They have time to coordinate care, finances, and family roles in a thoughtful way. Families who wait are frequently forced into quick decisions with fewer choices. The difference is not effort or intention. It is timing and guidance. When to Start Planning If you are healthy, planning now gives you the greatest flexibility. If you are noticing changes in health, mobility, or memory, planning becomes more urgent. A helpful rule of thumb is this: if the thought of losing your savings or home to long-term care costs concerns you, it is time to start planning. Planning Is About Protection, Not Panic Planning for long-term care without losing everything is not about fear. It is about protecting yourself, your spouse, and your family from unnecessary stress and financial hardship. Long-term care is likely. The costs are significant. Medicare is not the solution. But with proactive planning, families can preserve dignity, choice, and financial stability. If you want a plan that protects both your care and your legacy, a thoughtful conversation is the best place to start.
May 19, 2026
The Talk
No, we are not talking about the birds and the bees and how to have a conversation with your young son or daughter. We are talking about the conversation with your parents as they age and what are their wishes in regard to caregiving, long-term care, death, and the planning associated with it. Most families shy away from these conversations and essentially treat them as faux pas conversations and avoid them at all costs. While avoiding the conversation can make it seem like its going away and make it seem like everything is okay inevitably that decision will blow up and will become a very painful situation for those involved.As an estate planning and elder law attorney, I cannot begin to tell you how many families avoided this conversation with their parents and regretted it later. I have never had a family come back to me after I suggested that they sit down and have The Talk and told me that they regretted it and wished they wouldve waited. They all say that it was great to get everything out on the table.Most parents dont talk about it with their children mainly because they dont think that their children want to discuss it. We often hear parents saying that their kid clams up or their kid gets very nervous and just doesnt want to talk about them or their spouse dying. Therefore its easier just not to have the conversation. Believe it or not, most parents are open to having the conversation because they are dealing with it on a daily basis and they understand that its better to have the conversation or at least to think about it ahead of time.Our advice is to try to start the conversation to understand what your parents wishes are for their golden years. Where do they want to live as they age? Do they have an idea as to how they would like to be treated if they were ever to be in an end-of-life situation? Where would they like to be buried? Do they have their financial affairs in order and do they have professionals that they are working with that you could contact if something happened to them? What is going to happen when if they have to go into a nursing home how can you assist them with their planning? What happens when they die?These are often great conversation starters. An estate planning and elder law attorney could also assist you with filling in the details and understanding how to put these answers in legal documents to make them binding in the future. Dont underestimate having your parents go to a workshop on estate planning and elder law, it will get them thinking and may also provide the opportunity for the conversation to occur.The holidays and times that families together often end up being the time that people get to discuss these topics and we encourage you to have The Talk not only for your parents but for you and your family as well. As much as your parents will thank you for wanting to have the discussion to figure all of the information out you will also be relieved to know that they have thought a lot about it and have a lot of strong opinions and beliefs and now you know that you can carry out their wishes. One thing that I have found is that people always want to do whats best for mom and dad and oftentimes want to do what Mom and Dad intended. If you have had the conversation and have documents in place everyone will be on the same page and no one has to speculate or argue about what was intended.If you are interested in learning more about Medicaid crisis planning, please call our office at 717-844-9218.
May 17, 2023

Estate Planning for Small Business Owners: Nurturing Your Legacy
Dear Friends, In the dynamic tapestry of life, small businesses are the threads that weave communities together. As an elder law and estate planning attorney at Bellomo & Associates, Ive had the privilege of assisting individuals and families in preserving their legacies. Today, I want to address a group close to my heart small business owners. Small businesses arent just economic entities; they are the heartbeat of our communities. Your dedication, hard work, and entrepreneurial spirit contribute not only to your familys well-being but also to the vitality of the neighborhoods we call home. For many small business owners, the line between personal and professional life is beautifully blurred. Your legacy isnt just about the products or services you offer; its about the dreams youve nurtured and the impact youve had on those around you. As we embark on the journey of estate planning, its crucial to recognize the interwoven nature of business and family. One common oversight is neglecting the unique considerations that come with passing down a business. Whether youre a seasoned entrepreneur or just starting your venture, a well-crafted estate plan ensures the seamless transition of your business to the next generation, preserving not only its financial value but also the essence of your hard work and dedication. Succession planning is a vital aspect of estate planning for small business owners. Its about cultivating the seeds of your success and ensuring that the business youve built with passion continues to thrive. By thoughtfully designating successors and outlining a clear plan, you pave the way for a smooth transition, minimizing disruptions and securing the future of your enterprise. Your business is more than a source of income; its a foundation that supports your familys dreams and aspirations. Estate planning goes beyond business assets; it safeguards the well-being of your loved ones, providing a roadmap for their financial security and peace of mind. To my fellow small business owners, I extend an invitation to join us at our upcoming estate planning workshop. Its a space where we delve into the unique considerations of business-centric estate planning and connect with like-minded individuals facing similar challenges. Bring your questions, share your experiences, and lets work together to ensure your legacy is as resilient as your entrepreneurial spirit. Estate planning is not just a legal process; its a commitment to nurturing what matters most. I look forward to meeting you and exploring the important next steps in securing both your business and family legacies. To a future of continued success and lasting impact, Jeff Bellomo
Sep 06, 2024
I Dont Trust My Trustee. What Can I Do?
It is important to understand that a trustee is a fiduciary and is held to a higher standard of duty. It is imperative as a beneficiary of a trust that you read every word of the trust and understand the circumstances under which the trustee is to distribute money to you as the beneficiary.If you do not understand the agreement, seek legal counsel so that youre sure you understand the terms under which the trustee should/may/can/must distribute money to the beneficiary. As you can see from all the different words that I used, every trustee has different discretions depending on the four corners of the trust document. There is no one size fits all, so it is imperative that you read and understand the terms of the document and what discretion the trustee has.Once you understand the document if you still feel as though youre not getting transparency from the trustee you can always request an accounting. If the trustee does not comply with the request for the accounting of the trust you can then file an action in the Orphans Court in your local county to force the trustee to provide you with a copy of the accounting to understand what money has been distributed from the trust and under what circumstances. If you have reviewed the accounting and are still not satisfied that the trustee is fulfilling his or her fiduciary duty, I would look to the trust document to determine if there is a trust protector.Many trusts nowadays will incorporate in them a trust protector who is often another law firm or professional fiduciary who can assist the beneficiaries. It would also be imperative to read every word of this section to understand what the trust protector can and cant do and also seek counsel if you still do not understand the specific terms of the documents.Because there are so many different styles and types of trusts it is virtually impossible to provide a specific direction to beneficiaries who feel that the trustee is not acting in their best interest, but the steps provided herein provide a starting point for the beneficiaries to feel that they have a voice and a say. In certain circumstances, the trustee may have sole and absolute discretion to do whatever he or she wishes, but even in those circumstances understanding what monies have been paid out and your rights under the document is very important.Please seek assistance from an attorney who specializes in trust and understands the ins and outs of trust documents in order to be able to provide advice on what you can and cant do within the terms of the trust.If you would like to learn more about trusts and how they can benefit your family, please give us a call at 717-844-9218.
Jul 21, 2023
Estate Planning Basics: What Everyone Should Have in Place
Published on October 14, 2020. Last Updated on October 28, 2025.As an elder law attorney, one of the most common questions I hear is, What kind of estate planning do I really need? The truth is that no two estate plans are the same. Each persons goals, family circumstances, and financial situation shape the details. However, there are a few core legal documents that everyone, regardless of age, income, or health, should have in place. These documents form the foundation of every solid estate plan. They protect you during your lifetime, guide your loved ones if you become incapacitated, and ensure your wishes are carried out after your death. Without them, your family could face unnecessary financial complications or court involvement at an already difficult time. Lets walk through the essential components of a complete estate plan, why each is important, and how they work together to safeguard your future. 1. A Last Will and TestamentA last will and testament is the cornerstone of most estate plans and for good reason. Its your opportunity to maintain control over what happens to your assets after your death.Your will allows you to:Designate who receives your property and assets.Appoint an executor to handle your estate.Name a guardian for minor children.Its important to understand that a will governs only probate assets property held solely in your name without a designated beneficiary. For example, your house, car, or personal belongings are typically included in your will. However, assets with joint ownership or beneficiary designations, such as retirement accounts or life insurance, pass directly to the named individuals. This means if your will leaves everything to your spouse but your life insurance still names a former partner, the insurance company must legally pay the named beneficiary, even if your will says otherwise. Without a valid will, your states intestacy laws decide who inherits your estate and that may not align with your wishes. For example, unmarried partners, stepchildren, or close friends typically receive nothing under intestacy laws. A well-drafted will ensures your property passes the way you intend and that the right person manages your estate. 2. Financial Durable Power of AttorneyA Financial Durable Power of Attorney (POA) gives someone you trust the authority to manage your finances if you become unable to do so. This could include paying bills, managing investments, selling property, or handling taxes. The term durable means the power continues even if you become incapacitated. You can also decide when the authority begins immediately upon signing, or only if a doctor determines you are unable to manage your affairs. Why does this matter? Without a durable POA, your family may need to go through the court process of guardianship or conservatorship to handle your finances. That process is often time-consuming, costly, and emotionally draining.For instance, one of my clients a retired teacher suffered a stroke and was unable to handle her bills or bank accounts. Because she didnt have a financial power of attorney, her daughter had to petition the court for guardianship, which took nearly three months and thousands of dollars in legal fees. Had a POA been in place, her daughter could have immediately stepped in to keep her mothers finances stable.By signing a durable financial POA in advance, you ensure that someone you trust can step in seamlessly if needed, without court involvement. 3. Health Care Power of Attorney and Living WillA Health Care Power of Attorney (also called a medical proxy) designates a trusted person to make medical decisions on your behalf if youre unable to communicate your wishes. Your chosen person called your health care agent can talk with doctors, access medical records, and make treatment decisions consistent with your values and preferences.Often, this document is paired with a Living Will or Advance Health Care Directive, which outlines your wishes regarding life-sustaining treatments, such as:Use of ventilators or feeding tubesPain management preferencesOrgan donationResuscitation decisions (DNR orders)Together, these documents ensure your medical wishes are respected and your loved ones arent left making difficult choices under stress.For example, one family I worked with had never discussed end-of-life wishes. When their father fell critically ill, his children disagreed about whether to continue life support. It caused painful family conflict at an already emotional time. If their father had completed a Living Will and appointed a health care proxy, his wishes would have been clear, and the family spared that anguish. Its also worth noting that your health care agent and financial agent dont have to be the same person. Many people choose different individuals based on who is best suited for each role. 4. Reviewing Beneficiary DesignationsOne of the most common and costly estate planning oversights involves outdated beneficiary designations on accounts such as:Life insurance policiesRetirement accounts (IRAs, 401(k)s, 403(b)s)AnnuitiesTransfer-on-death (TOD) or payable-on-death (POD) accountsThese assets bypass your will entirely and go directly to the listed beneficiaries. Thats why keeping them updated is critical.This mistake was made by one of my past clients whose ex-husband remained the listed beneficiary on her 401(k) despite her having remarried years earlier. When she passed away unexpectedly, the entire account legally went to her ex-spouse not her current husband because the plan administrator was bound by the designation on file.To avoid such outcomes, review beneficiary designations every few years and after major life events such as marriage, divorce, or the birth of a child. Your designations, will, and any trust should all work together to reflect a unified plan. 5. Guardianship Designation for Minor ChildrenIf you have children under 18, your estate plan should include a guardianship designation. List the names of those who will care for your children if something happens to you before they reach adulthood. Without a written designation, a court will decide who raises your children and that decision may not reflect your wishes.Its best to name both a primary guardian and an alternate guardian in case your first choice cannot serve. This gives the court clear direction and minimizes family disputes. Choosing a guardian can be emotional, but its one of the most loving steps you can take as a parent. It ensures your children are cared for by someone who shares your values, lifestyle, and parenting philosophy. Why These Estate Planning Basics MatterThese core documents your will, durable powers of attorney, health care directives, and beneficiary designations form the foundation of a strong estate plan. Together, they:Ensure your assets are distributed according to your wishes.Empower trusted individuals to manage your affairs if you cant.Protect your loved ones from unnecessary court involvement and stress.Even if you think you dont have much, estate planning is not just for the wealthy. Its about control, protection, and peace of mind. These documents ensure your voice is heard and your loved ones have clear guidance during difficult times. Updating Your Plan as Life ChangesEstate planning isnt something you do once and forget. Life changes and your plan should evolve with it.You should review your plan every few years or after major events, such as:Marriage or divorceBirth or adoption of a child or grandchildDeath or incapacity of a named agent or beneficiaryMajor financial changes (inheritance, sale of property, retirement)Relocation to another state (since laws vary by location) When You May Need More Advanced PlanningWhile these five basic documents cover most peoples needs, some situations require more advanced tools, such as:Revocable Living Trusts for privacy and probate avoidanceIrrevocable Trusts for asset protection and Medicaid planningSpecial Needs Trusts for beneficiaries with disabilitiesCharitable Trusts or Tax Planning Strategies for large estatesFor instance, a family business owner may need a succession plan to ensure smooth operations if something happens to them. Or a parent with a child who has special needs might establish a trust to provide long-term financial security without jeopardizing government benefits.Working with an experienced estate planning or elder law attorney helps identify which strategies best fit your goals. Common Estate Planning Mistakes to AvoidEven with the best intentions, mistakes happen. Some of the most common include:Failing to sign or properly execute documents.Forgetting to update documents after major life changes.Naming co-agents or co-executors who may not cooperate.Creating a trust but failing to transfer assets into it (funding the trust).Overlooking digital assets such as online accounts, passwords, and cryptocurrency.Not communicating your wishes to your family or agents.These errors can undermine your plans effectiveness. Avoid them by reviewing your documents regularly and seeking professional guidance before making significant updates. Get the Support You Need from Bellomo & AssociatesEstate planning doesnt have to feel overwhelming but it does have to be done right. At Bellomo & Associates, our experienced elder law and estate planning attorneys work closely with individuals and families to create customized plans that protect what matters most.From drafting or updating your last will and testament to developing comprehensive strategies for long-term care, Medicaid, and trusts, our team ensures that every aspect of your plan is thoughtfully designed and legally sound.Whether youre creating your first estate plan or revisiting an existing one, were here to guide you with clarity, compassion, and confidence. Contact Bellomo & Associates today to schedule a consultation. Its never too early or too late to protect your future and give your family lasting peace of mind.
Nov 14, 2025
When Avoiding Probate Wasnt Necessary Or The Right Answer
We recently did a blog that talked about how national companies and mainstream media often talk about avoiding probate at all costs and the advantages with it. I warned in that article that probate is not a bad thing in the Commonwealth of Pennsylvania. In fact, the process itself is very straightforward and fairly inexpensive. Many of our national companies and spokespeople come from states where the rules are very difficult and expensive, and make it sound like every state follows the same process when, in reality, each state has different rules, and overall, Pennsylvania is a very easy state to go through probate and is overall fairly inexpensive.Several people have asked us to provide more in-depth answers as to what are the tools to avoid probate. In the previous article, I avoided getting into that conversation because I simply wanted to address the fact that we dont necessarily need to do that in the state of Pennsylvania and that we recommend that you seek counsel to advise you on the pros and cons of such decisions. I will take a minute in this blog to discuss some of those options briefly but still recommend that you speak to an attorney to discuss whether it is applicable for you in your specific particular situation.Here are a few options or ways that people can avoid probate:Create a trust.Joint ownership.Outright gifts.Beneficiary designated accounts.Trusts are certainly very viable options and can provide a lot of benefits. Some of these benefits can include avoiding probate in several different states, as well as potentially asset protection. In some rare instances, some people need advanced tax planning, in which case a trust can serve as a way to reduce the federal taxable estate to avoid paying higher taxes to the government. Each particular trust certainly has pros and cons and the rules are different for each one. Depending on whether you are doing a trust simply for probate avoidance, for asset protection, or for tax planning, each trust will have its own rules and will be governed by a different set of restrictions and limitations. Fully understanding the restrictions and limitations and weighing that with whether or not the benefits outweigh the negatives is something that each person should do individually and should do with an experienced trust planning attorney.Joint ownership. It is very easy to encourage people to add family members as joint owners on their accounts. Oftentimes, people will say that theyre doing this for convenience. I believe that it is important to understand some of the negatives that can come out of joint ownership property ownership, such as if the child were to die first, there would be tax implications in the Commonwealth of Pennsylvania to the parent for adding their child at a 4.5% tax rate. It is a very difficult conversation to be the person who calls the parent who lost a loved one who has to tell them that they are very sorry for their loss and to remind them that theyre going to have to pay inheritance tax on the joint owned account when it was the parents money in the first place, and why do they have to pay tax on their own money? Once you add a joint owner to an account, there are implications of that transfer that very few people discuss or are aware of.If you would like to learn more about estate planning and elder law, please give our office a call at 717-844-9218.
Jun 23, 2023
Who Will Raise Your Kids and Make Sure That They Are Taken Care of Financially if You Are Gone?
The thought of passing away and not being able to raise your kids is certainly one that none of us hope that we ever have to experience or endure. However, the thought of our children being involved in a legal dispute over whos going to raise them and having them go in and out of court after the loss of their parents is even more haunting and disturbing.If you want to be in control of who is going to raise your kids and who is going to make sure that they can distribute the money to them to take care of them financially, it is imperative that you make efforts to name a legal guardian for your children. Otherwise, a judge will be the individual to decide who will ultimately raise your children, often amidst litigation and arguments among numerous family members.We are often asked in our office who is the best person to name as the legal guardian for children and who should be the trustee of said children to distribute the money to them.Although there are certainly no perfect answers, we wanted to provide some thoughts, ideas, questions, and comments in order to be able to help narrow your options and assist you with this decision.Who in your life shares the same values as you and is as patient to raise your children?Based upon the individuals that you are thinking of, how many children do they have on their own and would adding your children to their family be insurmountable? Do they have the stamina to be able to raise all of the children not only their own but yours?If you are not related to this person by blood, would you still consider this person to be the right choice to raise your children? We often find that people will look typically to other siblings or family members, not because they think that they are the right choice but simply because they are blood and believe that they have to do that.Have you talked to the person or people that you are thinking of naming? Are they willing to undertake the responsibility of being a legal guardian to raise your children? We recommended that you contact those individuals to verify that they are willing and able.Does the age of your potential person cause a problem? For example, are they under 18, or are they of an age that they are slowing down and not able to take care of themselves, let alone other individuals? We often find that children want to name their parents as the guardians and forget that as their parents get into their later years, it is difficult for them to raise children, particularly young children who are very ambitious and very strenuous.Does the person or people that you are thinking of have a deep enough connection with your children or a significant personal relationship with you and your family?Do the people that you are thinking of live locally so that the kids would not have to change school districts? If not, have you discussed this possibility with your children if they are old enough to understand and how they would react to that or, have you discussed with potential legal guardians the possibility of them moving to your hometown in order to get your children out of high school or at least of an age that moving them would not be problematic?Do the people that you are thinking of have the financial means to undertake such an endeavor? It is imperative that you plan ahead to provide, in case you are gone, and we would recommend that you talk to a financial planner to discuss ways to provide for your children, such as life insurance and other vehicles. That would allow the guardian to be able to get access to money on behalf of the children, which is certainly important.Whether or not the trustee and the guardian are the same people is a personal choice. Some people believe that you should separate the person who is raising your children from the people who are in control of the money on behalf of the children, such as a checks and balances situation. Others feel that if you trust the individual with your kids, you should trust them with the money. Although I personally do not believe that there is a perfect answer for all people, I think that it is definitely something that everyone should think about, and oftentimes, the people who you are thinking of will dictate the answer.These are a few questions thoughts and ideas that people should think about in regard to who to name as the legal guardian and trustee for their families. If you would like to have additional information or to discuss this further, please give us a call at 717-845-5390.
Oct 06, 2023
How Technology is Changing the Estate Planning Landscape
It is so easy these days from the comfort of our homes to be able to learn all about our ancestry and to be able to take DNA tests to learn about our family history. Technology sure has come a long way and is providing us with information from the comfort of our own homes that we never had seen before. It is essential, now more than ever, to make sure that our estate planning documents are up to date and also are done appropriately and properly.Nowadays, it is easier to track down a parent that you never knew existed and just learned about, whether were adopted or simply just lost contact or were estranged from that person. Or there could be a situation where someone does not know that they had a child and years later it may come to light that they are a father because of the technology and ability to learn this information from the comfort of your home. This will certainly change outcomes in the future of who is entitled to certain assets and who may have standing and different circumstances.It will be interesting to see how this fleshes out over the next 20 or 30 years, but one thing is for certain it is more important now than ever to make sure that your estate planning is up to date. It will be important to have them done correctly and make sure that all of your is are dotted and ts are crossed to ensure that someone cant come in later who is unknown or unexpected and have rights. And especially important to have your documents prepared and not rely on the intestate laws of Pennsylvania to determine your beneficiaries.Technology certainly has and will change estate planning in the future, and we look forward to seeing how it does, but in the meantime, we will certainly plan accordingly and make sure that our documents are up to date and properly drafted for any unexpected mishaps.If you would like to learn more about this, please give us a call at 717-844-9218.
Jul 14, 2023
What is the Worst-Case Scenario if I Dont Plan?
What is the worst-case scenario if I dont plan?This is a question that was raised to me several years ago by a client, and I answered her question by walking her through what would happen if she did not have a plan, and she became incapacitated from a financial perspective as well as from a medical perspective. I also answered the question about what would happen if she died. My client was married with three children. Her husband had two children of his own, and she certainly loved them and treated them like her own.Unfortunately, she did not see the need to do planning ahead of time, and the worst-case scenarios that I set forth for her are exactly what happened. She became incapacitated a few years later and had a stroke. While she was in the hospital, her children and her husband were disagreeing about the healthcare decisions that should be made on her behalf. To further complicate things, the stepchildren showed up at the hospital also arguing that they should be involved in the decision process.There is a healthcare statute in the Commonwealth of Pennsylvania that does provide the next of kin and who would make healthcare decisions, but, ultimately, the hospital did not want the husband and his children along with the stepchildren to be fighting in the hospital, so they asked them to go to a guardianship hearing and have a judge adjudicate who would be the guardian of her healthcare decisions. There were a decent amount of assets in her name alone, and, unfortunately, the husband was not able to access them because she did not have financial power of attorney in place.He went to the bank trying to explain the situation but, ultimately, was told that he had to obtain a guardianship Order from the Court to be able to make decisions on behalf of his wife. The husband ended up in court fighting with his children that he had with his wife along with his children to another relationship, fighting over who should be granted guardianship of her. He ultimately won after having to hire an attorney and spent thousands of dollars in legal fees.She passed away and did not have a Will in place. I think everybody, including her and him, incorrectly believed that the husband would get 100% of the assets. I did explain to her the worst-case scenario under the Pennsylvania Intestate Succession Statute that the husband would be forced to get the first $30,000 and then have to split the remainder with the children that he had with his wife. Because of all of the strained relationships that occurred under the fighting that they had in the hospital and the Courtroom, tensions were high, and they did not get along. The husband was devastated to learn that he only got the first $30,000 and one-half of the remainder. He asked his kids to please gift the money back so that he could have it to live the rest of his life, and they laughed in his face and kept the money that they were entitled to under the statute.Unfortunately, this scenario is far too common. As an estate planning and elder law attorney, I tend to live in the worst-case scenario world because that is what typically happens. If you plan, you avoid all of these circumstances and situations from arising. If you do not plan and you allow yourself to be subject to the government or the states rulebook, it may not go the way that you want it or the way that your family wants it.I think often about that day when I met with her and discussed the worst-case scenario. I didnt scare her enough or do enough to make her realize how devastating that could be for her family. I am saddened over the tension in the relationship now with the entire family and know that I couldve easily eliminated all of those fights and arguments and the need to go to Court and spend thousands of dollars of money. My goal now is to show the worst-case scenario and hope that it hits home with at least one person who will get their planning in place ahead of time so that this does not happen to them.If you would like to learn more about how you can plan properly to avoid these and many other complications, please give our office a call at 717-844-9218.
Jun 16, 2023
What is a Pour-Over Will?
Most of us have heard about a Last Will and Testament, but have you ever heard of a pour-over Will? Pour-over Wills are often used in connection with living trusts.There are several different types of living trusts. Trusts are a vehicle that will avoid probate and often provide other benefits such as asset protection or other things, depending on what type of trust it is. The goal of a trust is to make sure that the assets are funded into the trust. In our office, we like to say that it is putting your boxes into your wagon.However, oftentimes assets will be left out of the trust for a myriad of reasons. To be completely honest, the main reason is probably just because people forget to put them in the trust, and over time when they buy something new instead of having it put into the wagon they just leave it in their name alone out of forgetfulness.A pour-over Will essentially says that all assets that are left in a persons name alone at the time of their death should pour over into the trust. The will does still have to be probated because the asset was in the persons name alone, but ultimately the assets will pour into the trust and then will be subject to the terms of the trust. We used this as a catchall or fallback provision so that we are sure that the trust terms will govern the distribution in the future.Pour-over Wills are often much shorter than your traditional wills because their purpose is simply to get assets over into a trust, subject to the terms of that trust. Therefore, pour-over Wills are simple and easy to understand because of their purpose.If you have a trust and your trust provides for all of the distributions to you and your family after you die, talk to your attorney or professional to determine how assets that are left in your name are going to be handled. Assuming that there wont be any is probably not the best option or course of action. Talk to your professional to determine if a pour-over Will is right for you.If you would like to have additional information or to discuss this further, please give us a call at 717-845-5390.
Sep 29, 2023
7 Steps Executors Must Take After a Loved One Dies
Being named an executor is an honor, but it often arrives at one of the hardest moments of your life. While you are grieving the loss of someone you love, you may suddenly find yourself responsible for legal, financial, and administrative tasks you have never handled before. Many executors worry about making a mistake or missing something important, which can add another layer of stress during an already emotional time. If you are wondering what executors must do after a loved one dies, you are not alone. Estate administration can feel overwhelming at first, especially when you are not sure where to begin. The good news is that the process generally follows a clear path. When broken down into manageable steps, it becomes far more approachable and far less intimidating. Below are seven essential steps executors must take after a loved one dies, along with practical guidance to help you move forward with confidence. Step 1: Obtain Certified Death CertificatesOne of the first and most important tasks is obtaining certified death certificates. Nearly every organization you work with will require one, including banks, insurance companies, investment firms, and the probate court. It is wise to request multiple certified copies right away. Executors are often surprised by how many are needed, and ordering additional copies later can slow the process. Funeral homes typically help families obtain death certificates, or you can request them through the local vital records office. Having death certificates readily available makes every step that follows easier and less frustrating. Step 2: Locate the Will, Trust, and Key Legal DocumentsNext, locate the most recent will, trust, and any related estate planning documents. These documents explain who was named as executor, how assets should be distributed, and whether probate is required. If a will exists, it usually must be filed with the probate court. If no will can be found, the estate is typically handled according to state law, and the court will appoint a personal representative. At this stage, many executors learn that they need formal authority from the court. This authority is often called Letters Testamentary or Letters of Administration. These documents allow you to act on behalf of the estate and communicate with financial institutions, creditors, and government agencies. Step 3: Secure Property and Protect Against FraudAfter a death, protecting the estate becomes a critical responsibility. Vacant homes, personal information, and financial accounts can be vulnerable to misuse or fraud. As executor, you should take steps to:Secure the home and any valuable propertySafeguard important documentsForward mail to a secure addressLimit access to sensitive personal informationIdentity theft after death is more common than many people realize. Addressing these risks early can prevent problems that are difficult and time-consuming to resolve later. Step 4: Notify Key Agencies and Financial InstitutionsNotifying the appropriate organizations helps prevent overpayments, fraud, and confusion. Some notifications may happen automatically, but many require direct follow-up. Common notifications include:The Social Security AdministrationBanks and credit unionsInvestment firmsLife insurance companiesCredit card companies and lendersCredit bureausFinancial institutions typically require a certified death certificate and proof of your authority as executor before discussing accounts. Handling these notifications early helps establish a clear foundation for managing the estate. Step 5: Inventory Assets and Open an Estate AccountOne of the core responsibilities of an executor is creating a complete inventory of the estates assets and debts. This includes real estate, bank accounts, investments, vehicles, personal property, and outstanding obligations. It is also important to determine which assets are probate assets and which pass directly to beneficiaries through joint ownership or beneficiary designations. Many executors choose to open an estate account to receive funds and pay estate expenses. This helps keep finances organized and avoids mixing personal and estate funds, which is a common and avoidable mistake. Clear organization at this stage saves time, reduces stress, and helps prevent issues later in the process. Step 6: Handle Debts, Bills, and Creditor Claims CarefullyAfter someone dies, their debts do not automatically disappear. At the same time, those debts do not become the executors personal responsibility. Debts are generally paid from estate assets and must follow specific rules and timelines set by state law. Executors are often required to notify known creditors and may need to publish notice to unknown creditors. This creates a formal claims period and helps protect the estate from future claims. It is important not to rush payments or distribute assets too early. Paying the wrong bill first or missing a required step can create complications and personal liability. A careful and methodical approach protects both the estate and the executor. Step 7: File Required Tax Returns and Distribute AssetsThe final step brings the estate toward closure. Executors are generally responsible for ensuring that required tax returns are filed, including the deceased persons final income tax return and, in some cases, an estate income tax return. Only after debts, expenses, and taxes are fully resolved should assets be distributed to beneficiaries. Distributions should follow the instructions in the will or trust and be documented carefully. Once distributions are complete and all obligations have been satisfied, the executor can formally close the estate, bringing the process to a clear conclusion. Common Executor Mistakes to AvoidEven well-intentioned executors can encounter challenges. Some of the most common mistakes include:Distributing assets before debts and taxes are resolvedFailing to keep detailed recordsMissing deadlines or required noticesMixing personal and estate fundsTrying to manage everything without guidanceBeing aware of these pitfalls can help you avoid unnecessary delays, disputes, and stress. You Do Not Have to Do This AloneServing as an executor is a significant responsibility, especially during a time of loss. While the process may feel overwhelming at first, understanding the steps involved can bring clarity and confidence. With proper guidance, executors can stay organized, protect assets, and honor their loved ones wishes without carrying the burden alone. If you are serving as an executor and want clarity and support through estate administration, help is available. Register for a Workshop to learn how the process works and how to move forward with confidence.
Feb 06, 2026
.png)
The Risks Of An Adult Child Getting An Advance On Their Inheritance
As we grow older, our desire to support our children often intensifies. A trend that is becoming more prevalent is parents choosing to give their adult children an advance on their inheritance while they are still alive. Essentially, this means gifting a sum of money to the child during the parents lifetime and including in their estate planning documents that if the gift is not repaid, it will be considered an advance, affecting the childs share of the estate. While there are several concerns I have with this approach, two major ones stand out: the potential impact on Medicaid eligibility due to the gift being considered, and the risk of unequal distribution of assets among the children. One significant issue arises if the parent requires long-term care. Medicaid, the government program that assists with long-term care costs, imposes a five-year look-back period to assess any gifts made during that time. If a gift is identified, a penalty is calculated, which could prevent the person from qualifying for Medicaid until the penalty period is served. Providing an advance during your lifetime is indeed considered a gift and may significantly affect your eligibility for long-term care assistance. Additionally, we cannot predict the financial demands that may arise toward the end of our lives, especially when it comes to potential long-term care needs. Giving away money during your lifetime with the expectation that everything will be equalized may be risky, as theres no guarantee of how much money will be left in your estate. For instance, if an advance of $300,000 is given to one child, deemed an advance, and after paying debts, funeral expenses, and legal bills, there is insufficient remaining to reimburse the other children, an unfair situation arises. As a general rule, we advise against providing advances during your lifetime. While there may be specific exceptions based on individual circumstances, seeking counsel before making such decisions is crucial. Without professional guidance, we do not recommend this course of action. Join our free educational workshop to delve deeper into estate planning and inheritance strategies. By attending, youll gain valuable insights to make informed decisions about your assets and your familys future. Reserve your spot now!
Jun 14, 2024
Keep Our Loved Ones at Home
I have never had a client tell me that they want to go to a nursing home. Almost daily in my practice I hear that my clients want to remain in their home as long as possible. Unfortunately, some clients do not want to bring outside caregivers into the home for a myriad of reasons. The old days of the children taking care of the parents needs to make a comeback. Caring for parents to keep them home is extremely rewarding for both the child and the parent.Being a family caregiver is one of the most rewarding, amazing experiences that children can provide to their loved ones. I have heard time and time again from children who are able to provide caregiving how rewarding it is, particularly in cases when it keeps their loved ones out of a nursing home.For a number of reasons, children who provide caregiving should enter into a written caregiver agreement with their parents.First, it is the best way to ensure that there are not mis-expectations and hurt feelings later.Second, if done properly, it will actually provide, for both VA purposes Medicaid purposes, a legitimate spend-down of resources which would otherwise go to the government, and the monies paid will not be considered a gift. Therefore, no penalty will be assessed for the money paid to the child.The one thing to remember is for the child caregiver monies that are received will be income taxable to the child; it is very important that the child claim those monies as income on their tax return so that it clearly shows that it was not intended to be a gift.However, family caregiving is certainly not without its downsides to caregivers. In most cases the caregivers could make more money if they stayed in the workforce and did not leave to provide care. In a situation where they are trying to continue to work and provide care, the increased stress added to the caregivers can be detrimental their physical and/or emotional health.There are often cases where family dynamics become an issue, either because one child is doing the caregiving and that child feels like theyre being taken advantage of, or others feel as though that child is taking advantage of Mom and Dad because they are getting paid.Either way, a lot of times it provides an additional stress to family members that they werent expecting. There are times where a caregiver will be out-of-pocket as well for certain costs, and getting reimbursed may surely be an allowable thing under the law, but having other children understand why money is being distributed to one child versus them is often not an easy conversation.There is no doubt that for those people who are able to provide care to their loved ones, care in the home it is a wonderful gift. However, I highly recommend that everything be put in writing for all of the reasons stated above, but mostly so that there are no missed expectations among the people receiving the care, the people providing the care, and the other family members.To those who have been able to keep their family members home, thank you for everything, all that you do is appreciated. To those who are considering it, give it a try. It could be the best decision you have ever made.
Mar 22, 2023
What If You and Your Childs Other Parent Cannot Agree on a Guardian?
When engaging in estate planning for any parent whose child is not yet an adult, there is always one very important decision to make: who would be the guardian of their child(ren) if both parents pass away? Like many issues in estate planning, it is an almost unimaginable thought that such a tragedy could occur to a child. But if we did not plan for the worst when doing estate planning, it would not be providing your family the protection it deserves.If a child would ever lose both their parents before they are an adult, the state would have to appoint a person to be in charge of your childs best interest and who could legally act as the childs parent (for example to have authority to register the child for school or take the child to a doctor). This person is what is referred to as a guardian, and can only be appointed by a Judge after a very thorough vetting process and Court proceedings all centered on the standard of what is in the best interest of that child.A common misconception is that there is some automatic and informal process whereby, in the event of the death of both parents, the childs pre-determined relative x would automatically become the childs guardian. Again, this is simply incorrect as stated above, even if you list a preferred guardian in your Will. The only way that your child will have a guardian appointed is after they go through the guardianship process in Court. Nevertheless, it is not as though a Judge would ignore the wishes of the deceased parent. The wishes of the deceased parent would be overwhelmingly strong evidence to any Judge who was trying to decide what person would be best to care for this child going forward. For that reason, it is imperative for any parent to list their preferred choice of guardians in their Will in the event of their death.When I am working with estate planning clients and helping them consider who should be listed as their childs preferred guardian, things can get complicated quickly. It can be difficult for any couple to agree on who would be the appropriate guardian for their child, and it is something that most people try not to even imagine. Common examples of concern quickly become issues such as which set of grandparents should be listed first. Should we make both of our siblings act as co-guardians? Do we still feel comfortable with your father as guardian if your mother is no longer here, or vice versa?The best approach is to plan for the immediate. I always remind clients that they should only try to plan ahead for the next few years because they can always revise that choice in their Will as time goes by. Sometimes, there is an obvious choice of who would take care of toddlers; but maybe that same person would not be such a great choice with a teenager. Its also important to take into consideration a list of backup guardians. You can have as long of a succession line for your preferred guardian in your Will as you like to provide you with the most comfort possible. By taking these steps, and understanding that there is an entire judicial process set up to protect your children, you can enjoy peace of mind knowing you have done the most you can to protect your family.If we can be of any assistance or answer any questions while you make decisions about yourself and your family, please give us a call at 717-844-9639 or click the link here and we will contact you.
Apr 28, 2023
What is the difference between a living will and a healthcare power of attorney?
This is the question that I receive at least once a week in my estate planning and elder law practice. Taken together, a Living Will and a Healthcare Power of Attorney, are an Advanced Healthcare Directive. Taken individually a Healthcare Power of Attorney allows an individual to make healthcare decisions on another persons behalf. A Living Will is a document that only kicks in when a person is end-stage medical which means that two qualified physicians have put in writing that the individual has no realistic hope of recovery. That they will always remain permanently unconscious, vegetative, comatose, and/or terminally ill. If the document has both of these items in them together, then it is considered an Advanced Healthcare Directive.I am always urging people to ensure that they have these documents in place. My main reason for feeling that way is that I believe that it is imperative to take the burden off a loved one, to spare them from having to pull the plug on their loved one. My experience at my law practice is that when a persons wishes are in writing regarding what they want or do not want should something happen, others are much more comfortable in allowing that decision to stand if they dont personally have to make it.I remember several years ago a spouse who recently lost her husband came into my office sobbing because her husband did not have an Advanced Healthcare Directive and she did not know exactly what he wanted. I reminded her that he repeated numerous times in my office in front of her that he did not want to live that way, and that if there is no hope there is no reason to live. However, all that she could know or remember is that she pulled the plug. She conveniently did not remember all of those conversations because, in her mind, she told the doctor to pull the plug, and within seven minutes her husband was no longer with her. There was absolutely no consoling or helping her feel better about her choice. And, although I am 100% confident she did exactly what her husband wanted because she was the one who had to make the decision she always wonders and always regretted it. Putting your wishes in writing will allow your family members to be 100% certain that they were your wishes and that they are merely following through on what you wanted, not what they think you want, or making them play God. It is imperative that everyone over the age of 18 have a Healthcare Power of Attorney as well as a Living Will.If we can be of any assistance or answer any questions while you make decisions about yourself and your family, please give us a call at 717-844-9639 or click the link here and we will contact you.
Apr 28, 2023
How Mediation Can Save a Family
Estate planning and elder law is a wonderfully rewarding and fulfilling practice area. As an attorney, I am blessed to work with families who are not in crisis and are merely planning for their families. To the extent that we are dealing with people who are in crisis, we are oftentimes able to assist with strategies that produce a positive result for the family that they are so happy and so relieved, which makes the relationship all the better. The hardest thing I have had to watch during my career is that families are ripped apart for numerous reasons. We often joke that we've seen siblings fight over five dollars or that family members will kill each other over Grandma's clock. While most times, we are joking and saying it in jest, the truth is families can often become divided over very basic and nominal things. Disputes can often arise when an elderly adult individual is receiving care in their home from another family member or when an individual dies and assets are being distributed pursuant to the Last Will and Testament or another device. The instinct for most people is to immediately call an attorney and litigate or fight over an issue; however, I truly believe that mediation can oftentimes not only save lots of money for the families involved but also is a pathway for the family relationship to remain intact. The job of a mediator is to lead all parties through a conversation to a mutual agreement that they have entered on their own accord rather than a judge issuing a final order or decree. Oftentimes with an order or decree, nobody feels like they got what they want and are always resentful and never happy with the result. We have referred numerous clients over the years to different local mediators, and the results have been overwhelmingly positive.We have had numerous clients who have come back to us and thanked us for the referral to the local mediators because they were trained in conflict resolution and were able to dissolve or diffuse the emotions to get to the root of the problem. Litigation immediately puts people on opposite sides and often has an end ugly because people are fighting over the principle of the matter, or they are digging their heels in just because they can. We highly recommend that you contact a local mediator if you are in a family conflict, regardless of the root cause. If you do not know of one, please feel free to contact our office and we can provide the names of several in the area who are very good at their craft.With the realization of the value of a mediator, we have now also been able to eliminate the very few situations that would have ended very badly for the family and allowed them to come to a mutual agreement. We hope that this article provides another alternative to litigation and how conflicts can be resolved. If you have any further questions or would like to get additional information, please reach out to our office at 717-220-3120 or check us out on the web at www.bellomoassociates.com.
Oct 20, 2023
When Cohabitating Goes Wrong
This blog discusses cohabitating in the context of two adult individuals who live together but who are not married. They can be a partner, significant others, or simply friends. We will not be discussing the pitfalls of owning property jointly or other obvious pitfalls of cohabitation but rather we will be discussing the downfalls of not having estate planning documents to allow that significant person in your life to help make decisions.In the Commonwealth of Pennsylvania, you must be married in order to have certain rights under the context of the healthcare statute. It also requires marriage to have rights under the intestate succession statute in the Commonwealth of Pennsylvania. However, many adult individuals will decide later in life to never get married for one reason or another.This is certainly a personal choice and preference, but if you are not legally married you will not have the ability to go into a hospital to make a decision for your partner or significant other. Without having a Healthcare Power of Attorney in place that appoints an agent your partner or significant other would have no ability or authority to make decisions for you. Instead, family members, who may or may not have been involved in your life, for years would be able to come in and make those decisions.Often times if there is a guardianship proceeding that has to occur (because you dont have a Power of Attorney or Health Care Directive in place), the Court will often defer to family members rather than individuals who are cohabitating with the alleged incapacitated individual. While this is certainly not set in stone, my experience personally is that the Court will defer to family and blood rather than a significant other relationship in appointing a guardian.It is certainly a persons choice to not get married and not to take the next step for one reason or the other, but we highly encourage those individuals to make sure that they have, at a minimum, in place a financial Power of Attorney and Health Care Directive and strongly suggest having a Last Will and Testament as well so that your wishes are known and can be carried out. This will at least save some heartache in the end.If you would like to learn more about avoiding estate complications, please give us a call at 717-844-9218.
Jun 16, 2023
Aw Snap! My Beneficiaries Died Before Me, Now What?
As estate planning and elder attorneys, we always encourage people to plan ahead in case something unforeseen were to happen.In some cases, we plan ahead and unfortunately, the people that we have named die before us. If this happens, it is essential to review your planning to determine whether or not you need to make any changes or whether or not your plan is sufficient as-is.When an individual tells me that their beneficiary has passed, that typically tells me that they have named that individual as a beneficiary on a non-probate asset, such as a life insurance policy, an annuity, a retirement account, a payable on death account, a transfer on death account, or in trust for an account. If this is the case, the first thing to do is to look to see if you provided for a contingent or successor beneficiary.If you did provide for a backup beneficiary, then the person that you have named as the contingent will be the person who receives your money if you were to die. If you did not provide for a contingent or backup beneficiary, then the money would go through your estate.Your estate means that if you have a Last Will and Testament the terms of that document would govern. Therefore, if the beneficiary that you have named is no longer alive and there is no contingent beneficiary, we will look to the Will to see who the beneficiary is under your Last Will and Testament. If it was the same person that was named in the non-probate asset, then we would look to see if the Will provides for a backup or any contingent beneficiaries.If the Will does not provide for anyone else to receive the asset and does not provide for a word such as "per stirpes" then we may have to look to the laws of intestate succession in the Commonwealth of Pennsylvania. If it does say per stirpes, then that individuals children would inherit the monies that that individual was entitled to.If there is no designation such as per stirpes and the beneficiary is not alive, then we will look to the rules of intestate succession in the Commonwealth of Pennsylvania. The state will provide under this statute an order of who would inherit first, second, third, etc. The Commonwealth of Pennsylvania would not be entitled to any of the money unless there are absolutely no beneficiaries or family members that are alive, which is very infrequent if not virtually impossible.If you are trying to determine who is going to take under the Pennsylvania intestate succession statute, I highly recommend that you seek professional advice for this hierarchy. Seek out the advice of an attorney who specializes in estate planning and has extensive knowledge in estate administration, but also has done cases where there is no Will and the intestate succession statute has governed. While it sounds pretty simple, this is not a common occurrence. So it would be essential to have somebody who has the experience to understand what is going to happen. The bottom line is that if we plan properly to provide for contingent beneficiaries and make a backup plan in case they die, the fact that your heir died before you should not become a huge issue.I hope that this article also helps you understand the interplay and inner workings between probate and non-probate assets and how, if there is no contingent beneficiary named and the beneficiary of the non-probate asset is no longer around, it would then default to the estate of the individual. The estate would be governed either by the terms under the Last Will and Testament or under the Pennsylvania intestate succession statute.If you would like to learn any more about this topic, please feel free to give us a call at 717-208-4546 or attend one of our upcoming workshops to learn more.
Sep 08, 2023
Planning For Retirement And Enjoying The Remaining Years
When it comes to planning for retirement, the most important person may, probably, be a financial planner or someone to make sure that you have enough money to enjoy those years the way that you want to. However, equally as important is to make sure that you have completed your estate planning at the same time. Oftentimes people think of estate planning as a death plan, but in reality estate planning is everything before that as well. Incapacity can hit us at any time, and its imperative that you have your basic estate planning documents in place so that during those wonderful years, if you were unable to do something for yourself, somebody would be authorized to do it for you.Some basic items that we always recommend everybody to have in place is a Financial and a Medical Power of Attorney, as well as a Living Will. These documents will allow you to make sure that your financial and medical decisions can be made for you if you are not able to make them. It will avoid any fights with family members or anyone who you do not want to have access to your information and will also avoid the expense and the emotional heartbreak of a guardianship proceeding. A Living Will will allow you to make your end of life decisions if you are end stage medical. This is a period in time when two qualified physicians state in writing that there is no realistic hope of recovery, that a person will always remain vegetative, comatose, permanently unconscious, terminally ill. If two doctors state this and that there is no realistic hope of recovery, a Living Will will allow you to decide whether you want heroic and lifesaving measures or whether you want them to withdraw treatment. The most important piece is that the individual gets to decide for themselves, so that their loved ones dont feel as though they had to make that difficult decision to pull the plug or to play God. Finally, a Last Will and Testament will allow you to make the decisions about what will happen at your death and in the future, and along with your financial planner, who assisted you in making sure that you have enough money for retirement, they will, also, ensure that the assets are designated properly to go to the correct beneficiaries.Enjoying your time in retirement and enjoying those wonderful years will be much better knowing that you have protected yourself in case of an unforeseen incident or accident, et cetera. The time to plan for that is now to allow you to enjoy each and every day to its fullest and not be worried about the worse-case scenario in case you didnt plan. Enjoy those final years!If you would like to learn more about this, please give us a call at 717-844-9218.
Jun 23, 2023
With premiums increasing drastically, should I keep my long-term care insurance?
This is a question that I receive on a regular basis in my estate planning and elder law practice. By way of full disclosure, I am not a licensed insurance agent and I am not licensed to be able to sell long-term care insurance or any other insurance product. I am an attorney with approximately 20 years of experience in estate planning and elder law and I happen to be a Certified Elder Law Attorney under the authorization of the Pennsylvania Supreme Court. While I am not the person who will sell the products, I am certainly an individual who has been advising numerous clients over the years and definitely believe in the benefits of a long-term care policy and what they can provide. We have done numerous other logs about long-term care insurance and the benefits of said policies.When long-term care insurance first gained popularity, many companies completely missed out on the actuarial tables and in predicting what people were going to need. Because of this drastic miscalculation, most of the companies that originally were in the markets for long-term care insurance are no longer there. The few standing companies that are left are trying to figure out ways to make up for the mistakes of the past. Because of that, they are often forced to increase premiums and decrease benefits. Although these companies do have to get permission from the insurance board, it is not a very difficult proposition, and in most cases, they will almost always be able to receive permission. The most difficult part is that individuals have been paying into a plan for a number of years and now are learning that theyre going to have to decrease their benefits and even then they may have to increase the premiums that they are paying. It is heart-wrenching to have to provide guidance in these situations and ultimately I always encourage them to bring in their financial professionals to try to make the decisions. This is as much about the numbers and common sense as it is about the emotion involved. This becomes very easy for us to get disgusted and upset about what is occurring, but it is a cold, harsh reality of the miscalculations that were made in the past. In some instances, increasing premiums and decreasing benefits is the only way some of these companies will survive.My best advice to any and all people who are faced with this dilemma is to write out the pros and cons and to try to make the evaluation and determination about numbers and as little as possible about the emotion of the situation. It is too easy to get hung up on the principle of the manner, but the truth is principles are expensive and cause wars. Make the best decision for you and your family based on the information that you have in front of you. Long-term care is not going away and dropping the policy out of spite is not going to help anyone.
May 17, 2023
10 Myths About Trusts That Could Cost Your Family Thousands
You have probably heard someone say that trusts are only for the ultra-wealthy. That one myth alone can cost families time, money, and peace. At Bellomo and Associates, we meet families all the time who skip the idea of creating a trust because of things they once heard from a friend, a neighbor, or a well-meaning relative. What many do not realize is that probate fees, delays, and public court records often cost far more than preparing a trust ever would. One middle-class family learned this the hard way. Their parents passed away with only a will. They assumed trusts were for people with large estates, so they never considered one. Probate proceedings dragged on for more than a year, incurring thousands of dollars in fees, and exposed private family matters to public scrutiny. A simple trust could have prevented all of it. Here are ten common myths that prevent families from utilizing one of the most helpful planning tools available. Trusts are only for wealthy families.Many of the families who benefit most from trusts are middle-class homeowners. Probate fees often take a larger percentage of smaller estates, making a trust the more affordable option long term. A will and a trust do the same thing.A will only takes effect after death and must go through probate. A trust manages your assets during your life and after you pass, and it keeps everything out of the probate system. Once I put assets in a trust, I lose control.With a revocable living trust, you remain the trustee for as long as you are able. You can change it, add assets, or even revoke the trust entirely. Trusts are too expensive.Most families are surprised to learn that probate often costs more than creating a trust. A trust is an upfront investment that prevents future legal bills and stress. I do not own enough to need a trust.A home alone is often reason enough. Even modest estates can get stuck in probate, and a trust makes the transfer smooth, private, and efficient. Trusts are only for older people.Young families use trusts to protect minor children, name guardians, and provide structure if the unexpected happens. Trusts are not about age. They are about preparation. My family will get along, so we do not need one.Even the closest families struggle with decisions after a loss. A trust removes guesswork, prevents misunderstandings, and keeps siblings from having to settle tough questions on their own. A trust keeps my finances private from my beneficiaries.Your beneficiaries will still know what they are receiving, but a trust keeps your information out of the public probate file. That is where most privacy is lost. My bank accounts already have beneficiaries, so I am covered.Accounts may transfer easily, but homes, vehicles, investments, business interests, and personal items all need a coordinated plan. A trust brings it all together in one place. I made a trust once, so it will work forever.Trusts must be reviewed to stay effective. Laws change, assets change, and families change. A trust that never gets updated can create new problems. The Truth About TrustsTrusts are not complicated or exclusive. They are practical tools designed to protect families, simplify transfers, and prevent unnecessary costs and delays. At Bellomo and Associates, we help families understand exactly what a trust can do and whether it is the right fit for their goals.
Jan 02, 2026

Hey Grandpa, Whats for Supper? Italiano Marinara
Here is an easy pasta dish from the back of the San Giorgio box. It makes an easy weeknight meal that comes together quickly and satisfies that craving for Olive Garden when you dont want to go out. Italiano Marinara2 Tbsp. olive oil c. chopped onion2 cloves garlic, minced3 cups (28 oz can) tomatoes, undrained2 Tbsp. chopped fresh parsley2 tsp. basil1 tsp. sugar tsp. oregano tsp. salt tsp. pepper3 c. (8 oz) San Giorgio Trio Italiano (or other tube-shaped pasta)1 c. shredded mozzarella cheeseIn 2 quart saucepan, heat oil and cook onion and garlic until tender but not brown. Stir in tomatoes with liquid, parsley, sugar, basil, oregano, salt, and pepper; bring to a boil then reduce heat and simmer, stirring occasionally to break up tomatoes, 15 to 20 minutes. Meanwhile, cook the pasta according to package directions; drain. Toss pasta with sauce and place in a 1-quart casserole. Top with mozzarella cheese and broil for 3 minutes or until cheese is melted. Makes about 4 servings.
Jan 05, 2024

Why Your Estate Plan Will Probably Fail Unless You Do These 3 Things
You finally did it. You signed the papers, got the binder, and checked Estate Planning off your list. But now what?If that beautifully prepared binder is collecting dust on a shelf, tucked in a drawer, or forgotten in a box, youre not alone. So many families work hard to create a plan, only to assume the job is done.Heres the truth: most estate plans fail. Not because you did anything wrong. Not because of a legal misstep. They fail because no one told you what to do after you sign. At Bellomo & Associates, we believe your plan should live and breathe alongside your life. The work doesnt end with the signature; it begins there. Here are the three key things you must do to make sure your estate plan works when your family needs it most. Update Your Plan RegularlyThink of your estate plan like a car. You wouldnt buy one and drive it for ten years without an oil change, right? The same idea applies here. Your plan needs regular check-ups to keep it running smoothly.Life changes. And when it does, your plan should reflect that. You should review your plan if:You got married or divorcedYou had a child or grandchildYou moved to a new stateYou bought or sold a home or businessEven if your circumstances havent changed, the laws might have. Or maybe the people you once trusted to step in for you have changed. We recommend reviewing your plan every 2 to 3 years, or sooner after any major life event. Thats why our clients love our maintenance program; its our way of walking alongside you through lifes changes. Fund Your TrustThis is where most estate plans quietly break down. You created a trust but did you put anything into it? If your trust isnt funded, meaning your assets arent properly titled, its just paper. Your family may still end up in probate court, facing delays, confusion, and extra costs. Heres a quick checklist to consider:Is your home deeded to your trust?Are your bank and investment accounts titled correctly?Do your retirement accounts and life insurance policies match your plan?Not sure? Were happy to help. We do this every day, and we love making it easy for our families. Educate Your HelpersNaming someone as a trustee, power of attorney, or executor is important. But if they dont know theyve been chosen or dont know what to do, it can lead to chaos at the worst time. Your helpers need to know:That theyve been named.What their role involves.Where are your documents?How to reach your attorney.We love it when clients bring their helpers to workshops or invite them to a quick meeting. One short conversation now can save your family from heartache later. Bonus: Give Yourself a Quick Check-UpAsk yourself these questions:Have I reviewed my plan in the past 2 years?Is my home titled in the name of my trust?Are my financial accounts correctly assigned?Do my agents or trustees know theyve been named?Do they know how to reach my law firm?If you answered no to even one, your plan might not work as you intended. But dont worry, you dont have to start from scratch. How We Help Keep Your Plan AliveAt Bellomo & Associates, we dont believe in one-and-done planning. Thats why we created our Maintenance Program, the Red Wagon Club. Its a simple, affordable way to keep your plan current and your family protected. As a member, youll receive:Annual plan reviewsUpdates for legal changesOngoing support to fund your trustEducational tools for your helpers24/7 access to your documents through our secure client portalBecause your life isnt standing still, and neither should your plan. Bottom LineYouve already done the hard part. You got the plan in place. Now lets make sure it works the way you intended. Pull that binder off the shelf. Lets dust it off together and make sure your legacy is protected for the people you love. Register for a Workshop to review your plan or learn how we help families like yours every day. Wed love to see you.
Jul 18, 2025
Money Isnt What Leaves a Legacy
Dolly Parton left behind an extraordinary career, incredible generosity, and a lasting impact on millions of people. Yes, she had wealth, but that is not what made her legacy remarkable. What made it remarkable was how intentionally she used what she had. She knew what mattered to her; she acted on it, and she built things that continued helping people far beyond the moment. That is the lesson. You do not need Dolly Partons money to leave a meaningful legacy. You do need to decide what matters to you. Dolly Gave Children Books. The Bigger Legacy Was Opportunity.Dolly Partons Imagination Library began in 1995 and grew into a program that mailed free books to children around the world. On the surface, that is a story about generosity. But underneath it was something much more personal. Her father could not read or write, so literacy was not just a cause to her. It was something she understood could change the direction of a persons life. She did not simply give money away. She connected her resources to something she deeply cared about and created a way for that impact to continue. For the rest of us, the scale may be much smaller, but the idea is the same. Maybe what matters to you is helping a grandchild afford college. Maybe you want to support your church, a local organization, or a cause your family has always cared about. Maybe you want to make sure a child or grandchild has opportunities you did not have. The question is not always, How much can I leave? A better question may be, What do I want what I leave behind to accomplish? Dolly Invested in Her Hometown. Legacy Can Be About Where You Came From.Dolly never forgot Sevier County, Tennessee. She built Dollywood there, helped create jobs there, supported families there after devastating wildfires, and made her hometown an important part of her charitable work. She could have taken her success anywhere. Instead, she kept investing in the place that helped shape her. That is another important lesson about legacy. It does not have to be global to be meaningful. It can be incredibly local. It can be the family property you hope stays in the family, a community organization you want to continue supporting, or simply a desire to help your children and grandchildren stay connected to the traditions and values you grew up with. Sometimes the most meaningful thing you leave behind is not the size of the gift. It is the connection behind it. Dolly Protected What She Created. Legacy Also Requires Planning.One of the smartest things Dolly Parton did during her career was maintain ownership of her work. When Elvis Presley wanted to record I Will Always Love You, the deal reportedly required Dolly to give up part of the publishing rights. She declined, and years later, that decision became enormously valuable. There is an estate planning lesson in that too. It is not enough to build something. You also need to understand what you own, how it is titled, who will receive it, and whether the plan you created actually works with the assets you have. We see this all the time at Bellomo & Associates. Someone has a will, but an old beneficiary designation says something different. Someone creates a trust but never gets assets properly connected to it. Someone assumes the house will automatically go where they want it to go. The intention may be good, but good intentions are not always enough. Dolly protected what she built. Families should think about doing the same. Dolly Gave While She Could See the Difference It Made.After the wildfires in the Great Smoky Mountains in 2016, Dolly helped provide monthly financial assistance to families who had lost their homes. She did not wait for some future date to make an impact. She gave while she was here to see what that help meant. That is a beautiful part of legacy planning that people sometimes overlook. Not every gift needs to happen after death. Sometimes the most meaningful way to help someone is while you are still here. Maybe that means helping a grandchild with school. Maybe it means helping a child buy a home. Maybe it means spending money on experiences with your family instead of focusing only on leaving the largest possible inheritance. There is no single right answer. The important part is being intentional about what you want your resources to do. Dolly Left Stories, Not Just Assets.Dolly Partons legacy is also tied to the stories she told. Her songs often came from her childhood, her family, her community, and the experiences that shaped her. They mattered because of the stories behind them. Families have their own versions of that. It may be the ring your mother wore every day, the tools in Dads garage, the family Bible, the Christmas decorations, the old recipe cards, the photographs, or the cabin where everyone gathered for years. Sometimes those things have very little financial value and enormous emotional value. That is why part of estate planning should also be conversation. Tell your family why something matters. Write down the story. Explain the decisions you have made. Do not assume everyone will simply understand someday. The Lesson Dolly Leaves BehindMost of us will never have a theme park. We will not own a famous music catalog or give away millions of books. But that really is not the point. Dolly Partons legacy was not powerful because it was expensive. It was powerful because it was intentional. Literacy mattered to her. Her hometown mattered. Her family mattered. Her music mattered. Helping people mattered. And over and over again, she made decisions that reflected those priorities. That is something every one of us can do. Your estate may be large or small. You may leave behind a home, a retirement account, some savings, family possessions, or simply a lifetime of memories. The question is not whether it is enough to matter. The question is whether the people you love will understand what mattered to you and whether you have put a plan in place to protect it. At Bellomo & Associates, we help families think beyond simply, Who gets what? We help them think about the bigger questions: What do you want to protect? Who do you want to help? What burdens can you remove from your family? What do you want the people you love to understand? Money may be part of what you leave behind. But money is not what makes it a legacy.
Sep 18, 2026
How to Help Your Loved One Avoid Isolation
Isolation is something that many seniors experience on a regular basis. However, with the COVID pandemic, that isolated feeling is more common than ever. Today, we want to encourage the individuals who know someone living alone to take some small steps to help your loved one socialize.We always encourage our clients to incorporate video conferencing or video chat to allow the family member to see their loved ones on a regular basis. This could be on a scheduled date and time each week where you have a conversation and catch up, or maybe schedule meals together where you leave the video on while everybody eats. You have to eat anyway and giving the opportunity for your loved one to spend their mealtime talking with their family and seeing familiar faces is a small gesture that could go a long way! Not only will it help them, but it will also give you the chance to assess whether your loved one is having any hearing or sight issues that should be addressed.Encourage your loved one to join clubs. Many of them are now virtual to allow as many people possible to partake. Having them be a part of these groups will give them interactions outside of your conversations and have stories to bring you when you visit or call.Although these are very minor suggestions, they can go a long way in helping your loved one not feel so isolated. Please feel free to give us a call if you have any questions or comments at 717-845-5390.
Jan 27, 2023
Caring for Loved Ones
More and more, as our population ages, many of us are taking care of aging spouses or parents. According to the Mayo Clinic, 33% of adults provide such care. Most caregivers feel an obligation to do so out of love.However, caregivers often find that providing that care is emotionally and physically, and often financially, draining. It is essential that caregivers know their limits. The danger is that the everyday stresses and challenges of providing such care often lead caregivers to forget about themselves, which can lead to depression, social isolation, financial difficulties, stress, fatigue, loss of interest in activities, frequent pain or headaches, and other effects.When we get on an airplane before we take off the flight attendants always instruct passengers that, if the oxygen masks drop down, be sure to place them on you before you help others. Why? If you pass out from lack of oxygen, you cannot help anyone else, so by taking care of yourself you are in a position to care for others. This is not selfishness it is a necessity. When Mary first came to see us, her husband of over 40 years had advanced Alzheimers and other physical conditions, and qualified for skilled nursing level care. Caring for him was a 24-hour job he would wander off at all hours of the day and night, and other behaviors andMary needed to dispense his medications throughout the day and evening. We immediately sensed that Mary was on the verge of a nervous breakdown, but this was her husband, her love, to whom she had pledged herself in sickness and in health. She could not imagine abandoning her obligation to him by placing him in a nursing home, and, sadly, they did not qualify for Medicaid Waiver for in-home care.We worked hard to make her understand that caring for her husband was killing her. As we talked, it became ever clearer that she could not keep up her current pace. I asked Mary how caring for her husband was affecting her; she admitted that she was under constant stress, was depressed, didnt have any social life, and was generally wearing down. I then asked her what would happen if she were to wear down so much that she died from overwork while caring for her husband. She was startled she hadnt considered that. The answer was, there would be no alternative he would have to go to a nursing home.It took a couple of meetings with her, but she finally came to realize that in the long run, she was not doing her husband any favors by keeping him at home; her best course of action would be to find a great nursing home for him, and visit him frequently and get stronger physically and emotionally herself so she could continue to play an important role in her husbands life for a long time to come.If you are going to care for a loved one in the twilight of his/her life, then there are things which you should do to maintain your physical and mental health, such as:Seek and accept help from family and support groups, including online.Keep connected with family, friends, even clergy.Find out from your loved ones medical staff, or others, what resources are available to you and your loved one.Give yourself permission to spend me time to rejuvenate your physical and mental conditions then do it! Even a short time for yourself each day can make a huge difference.Maintain good, healthy habits.Exercise it improves your mood and reduces stress. You should consider all of your options, but always consider your needs as well as your loved ones. Remember, to be an effective resource for your loved one, you need to put the oxygen mask on first before you can help others!
Apr 05, 2023
.png)
Family Conflicts Over Caregiving
As our parents age, the primary questions adult children face are (1) who is going to provide needed care, and (2) in what setting will mom or dad receive the needed care. Coming to such decisions does not always mean smooth sailing moving forward. Family members often view care issues very differently and conflicts can be further complicated when one of the siblings is the primary caregiver. Our team members find such conflicts to be quite common in their work with our clients and families. The situations are stressful and charged with emotion, worry, and exhaustionthe perfect storm for conflict and family duress.As I reflect on the meetings and consultations I have had with some of these families recently, I suspect that part of the problem is the fact that the aging parents failed to verbalizeearly and oftentheir wishes and desires related to the what if scenarios. Because their folks did not talk openly about their wishes and expectations, the adult children are often forced to guess what Mom and Dad would have wantedanother perfect storm for differences of opinion and sibling conflicts.If you have not already done so, commit to conversing with your adult children about the what ifs. Let them know your wishes and preferences. Consider the effort to be your conflict prevention plan, so that down the road, you and yours wont have to engage in conflict resolution. And be sure to have a formal caregiver agreement drafted if a family member becomes the paid caregiver. It is an important tool for many reasons, including clarifying the financial parameters of the care being provided. Doing so will prevent misunderstandings between those you love most. Open, honest communication is always the key, and we recommend it early and often in these situations.
Apr 12, 2024
Get Ready George Jetson
I recently attended the national Life Care Planning Law Firms Association (LCPLFA) conference in Alexandria, Virginia. The speakers were terrific, but two got my undivided attention. You see, Im a social worker who cringes when she sees parents waiting at the bus stop with their faces stuck in their cell phones, rather than chatting with their kids. I recall not being too excited about being asked to use a laptop rather than notepad and pen during home assessments years ago. Ive often said that I was born in the wrong century and would have been much happier had I been born 100 years earlier. Yet, as a child I remember loving The Jetsons. I was fascinated by George Jetsons ability to fly through the sky, arriving at his destination within minutes and was especially intrigued by Rosie, the robotic maid. I knew beyond a shadow of a doubt that it was all make-believe and would never happenor so I thought!I learned last week that we will soon be able to wear balance soles, which will help a 73 y/o body walk with the balance and accuracy of a 23 y/o. Folks in Denmark and Japan are actively working on exoskeletons that those with debilitating conditions like Osteoporosis will be able to wear to maintain their posture and ability to walk. Did you know that GPS smart soles are now available? Slip them in the shoes of a loved one prone to wandering. In the next five years, smart clothing will not only monitor our vital signs but be able to administer CPR! For a cool $100,000-$150,000, nursing homes can purchase a service bota robot with an animated bear face that lifts a patient needing to be transferred, in order to prevent employee injuries and better manage staffing challenges. Drum roll pleasewithin the next 10 years, assistant robots will be on the marketable to help humans with activities of daily livingdressing, grooming, meal preparation, you name it.Are your eyes rolling? Well, Ive had a major shift in my thinking about technology. Sure, Id prefer a future world where every human in need has a human to help them, but Ive come to appreciate the technologies that will allow us to safely navigate care for our growing senior population. Historically, the ratio of available family caregivers to seniors in need was 7:1. By the year 2030 it will be 4:1 and by 2050, it will be 3:1. Yep, were going to need all the Rosies we can get!This blog was guest written by our own Meg Motter, our Client Care Advocate. If you have questions for our team, please give us a call at (717) 845-5390.
Mar 22, 2023
The Most Common Medicaid Myths That Cost Families
My neighbor told me we should just put the house in the kids names. It is amazing how often conversations about Medicaid planning begin with advice like that. When families start thinking about the possibility of long-term care, everyone seems to have an opinion. Friends share stories about what worked for their relatives. Someone online insists you have to spend every penny before Medicaid will help. Another person confidently says Medicare will cover nursing home care if the need ever arises. Most of this advice is shared with the best of intentions. The problem is that Medicaid planning is one of the most misunderstood areas of elder law. Rules change over time, they vary from state to state, and what worked for one family may not work for another. Acting on outdated or inaccurate information can lead to costly mistakes, unnecessary financial hardship, and missed opportunities to protect the assets you have spent a lifetime building. That is why the release of Pennsylvanias updated 2026 Medicaid Long-Term Care Eligibility Fact Sheet is an important reminder that Medicaid planning is never something to base on old information or well-meaning advice. Every year, important eligibility numbers are updated, including income limits, protected asset amounts, and other figures that directly impact planning opportunities. At Bellomo & Associates, we often meet families who have delayed planning or made major financial decisions based on something they heard from a friend, neighbor, or online discussion. Fortunately, many of these misunderstandings can be avoided by understanding how Medicaid planning actually works. Why Medicaid Planning Is So Often MisunderstoodUnlike many legal topics, Medicaid planning does not follow one simple set of rules. Although Medicaid is a federal program, each state administers its own Medicaid system within federal guidelines. Eligibility requirements, planning opportunities, and available strategies can differ depending on where you live. On top of that, financial eligibility numbers are updated regularly to reflect changes in the law. For example, beginning July 1, 2026, Pennsylvanias updated Medicaid fact sheet includes a monthly gross income limit of $2,982 for certain long-term care eligibility calculations, along with updated resource allowances and other important planning figures. Those numbers were different just a year ago, which is exactly why relying on outdated advice can create problems. Every financial situation is different. Every health situation is different. Every familys goals are different. That is why Medicaid planning should never be based on assumptions or secondhand advice. Myth #1: You Have to Spend Everything You Own Before You Can QualifyThis is one of the most common Medicaid myths, and it causes many families to postpone planning until they believe they have exhausted every other option. The reality is much more nuanced. Medicaid does have income and asset rules, but that does not automatically mean every dollar must be spent before someone can qualify. Depending on your circumstances, there may be legal planning strategies that help preserve certain assets while preparing for future long-term care needs. The updated 2026 Medicaid fact sheet is another reminder that eligibility is based on specific legal standards, not rumors. Income limits, resource allowances, protections for spouses, and other important figures are carefully defined and reviewed each year. Medicaid planning is not about hiding money or trying to work around the rules. It is about understanding the rules and making informed decisions before valuable planning opportunities are lost. Myth #2: Just Give Everything to Your ChildrenThis advice has circulated for decades. Unfortunately, following it without understanding Medicaids rules can become an expensive mistake. Many people do not realize that Medicaid generally applies a five-year look-back period when evaluating certain transfers made before applying for long-term care benefits. Imagine a family that transfers a parents home to the children because they believe it will protect the property. A few years later, the parent unexpectedly requires nursing home care. Instead of qualifying for Medicaid immediately, the transfer may trigger a penalty period that delays eligibility. During that time, the family may be responsible for paying privately for care. According to Pennsylvanias updated 2026 Medicaid figures, the current penalty divisor used to calculate gifting penalties is $12,811.50 per month. That means an improperly timed gift could result in a substantial period during which the family must privately pay for care. Good intentions do not always produce good results. Before making major gifts or transferring valuable assets, it is essential to understand how those decisions may affect future Medicaid eligibility. Myth #3: Medicare Will Pay for Long-Term Nursing Home CareMany people mistakenly use the terms Medicare and Medicaid interchangeably. They are two very different programs. Medicare primarily provides health insurance for older adults and certain individuals with disabilities. While it may cover limited short-term skilled nursing care after a qualifying hospital stay, it generally does not pay for ongoing long-term nursing home care. Medicaid, however, is often the primary public program that helps eligible individuals pay for extended long-term care services. Confusing these programs can delay important planning because families assume long-term care expenses are already covered when they often are not. Myth #4: Its Too Late to Plan Once Someone Needs CareMany families do not begin thinking about Medicaid until a loved one has already entered assisted living or a nursing home. At that point, it is easy to believe every planning opportunity has disappeared. Fortunately, that is not always the case. Planning before a health crisis usually provides the greatest flexibility, but legal planning strategies may still be available depending on your familys circumstances. The important thing is not to assume it is too late. Seeking guidance promptly may reveal options your family did not know still existed. Myth #5: The Government Will Automatically Take Our HouseFew Medicaid myths create more anxiety than this one. The truth is far more complicated than a simple yes or no. Whether a home is affected by Medicaid depends on several factors, including ownership, who lives in the home, family circumstances, and the applicable Medicaid rules. The updated 2026 Pennsylvania Medicaid fact sheet also reflects an increased home equity limit, another reminder that these rules involve detailed legal standards rather than simple assumptions. Rather than making decisions based on fear, families benefit most from understanding how the law applies to their specific situation. Knowledge almost always leads to better decisions than assumptions. Myth #6: Medicaid Means Youll Have to Go to a Bad Nursing HomeAnother common misconception is that Medicaid recipients receive lower-quality care. In reality, many nursing homes accept both private-pay residents and Medicaid beneficiaries. Licensed nursing facilities must meet the same regulatory standards regardless of how residents pay for their care. The quality of a nursing home depends on factors such as staffing, management, inspections, and the services provided, not whether someone pays privately or through Medicaid. Families are far better served by researching available facilities than by assuming Medicaid determines the level of care. The Real Cost of Believing Medicaid MythsThe financial consequences of misinformation can be significant. Some families spend savings they may have been able to protect through proper planning. Others transfer assets without understanding the legal consequences and unintentionally create Medicaid penalties. Still others wait so long to begin planning that valuable opportunities are no longer available. The emotional cost can be just as high. Adult children suddenly find themselves making complex financial decisions during a medical crisis. Spouses worry about preserving enough resources for their own future. Families feel overwhelmed because they are trying to separate facts from misinformation while also caring for someone they love. Many of these stressful situations can be reduced with proactive planning and accurate legal guidance. The Best Time to Plan Is Before You Need CareOne of the greatest advantages of early Medicaid planning is having choices. When planning begins before a crisis, families have time to understand their options, organize financial information, evaluate legal strategies, and make thoughtful decisions without the pressure of an immediate medical emergency. Even if long-term care is never needed, having a plan provides confidence and peace of mind. If care does become necessary, your family will not be forced to make important financial decisions under tremendous emotional stress. Planning ahead is not about expecting the worst. It is about preparing for lifes uncertainties while preserving as many options as possible. At Bellomo & Associates, we help families understand todays rules while planning for tomorrows possibilities. Because Medicaid laws and financial thresholds continue to change, reviewing your plan regularly is just as important as creating one in the first place. Thoughtful planning can provide greater flexibility, protect important assets, and help your loved ones make informed decisions when they matter most. Replace Rumors With a PlanWhen families begin discussing Medicaid, the conversation often starts with, Someone told us Unfortunately, Medicaid planning is too important to rely on rumors, outdated advice, or internet myths. The release of the 2026 Medicaid eligibility figures is a perfect reminder that the rules do change, and planning based on last years information or someone elses experience may not serve your family well. The best decisions come from understanding how the law applies to your familys unique circumstances. The sooner you replace assumptions with accurate information, the more opportunities you may have to protect your financial future and prepare for the possibility of long-term care. Medicaid planning is not about hiding assets or finding loopholes. It is about making informed, legal decisions that help preserve your choices, protect the people you love, and provide greater peace of mind for the future.
Sep 04, 2026

Why Estate Recovery Sounds Worse Than It Is
We recently received a distressed call from a husband that we represented about a year ago on a long-term Medicaid application for his wife who was a local nursing facility resident. We had done an asset protection plan for the husband, preserving approximately $300,000 more than he had expected, plus the house, the couples car, and his retirement account. He was tickled pink about the result that we received. Unfortunately, his wife recently died, and he received a letter in the mail, coming into my office extremely upset. The letter was from the Estate Recovery Department office in Harrisburg, requesting information about the deceased, including the cause of death, how much money she had, and how the assets were titled. The husband had made comments throughout the original planning process that it all seemed too good to be true. He was extremely pleased but remained cautious. When he entered my office with the letter in hand, he commented, See, I knew it. Were in big trouble. I looked at him and asked why he felt that way. I reviewed the form and explained that it was nothing more than an information/fact gathering sheet and did not mean that the answers should be interpreted as negative. Estate recovery in the Commonwealth of Pennsylvania only pursues the probate estate of a Medicaid recipient if their assets are over $2400. In a situation where we qualify someone for Medicaid, we make sure there is no more than $2400 in assets for the client so that we know the individual is always below the amount the Commonwealth will go after in estate recovery. Furthermore, we always make sure that the couples house is in the community spouses name alone so that there is no situation wherein if the spouse predeceases the Medicaid recipient, the house ends up back in their name and at risk for estate recovery. It sounds complicated, but for a firm that understands the rules, our team makes sure that everything is done appropriatelythat all the is are dotted, and all the ts are crossed. I assisted the gentleman with the form, which he submitted that afternoon. He couldnt thank us enough for our advice and assistance.One comment that I would like to make is that when you are working with a professional, please do not talk to outside people who are not involved in the situation. This even means other professionals, because it is very difficult to understand everything that is going on unless you are involved in it. Oftentimes, people think that theyre helping by providing advice, but because they dont know the context, sometimes they mislead an individual and it causes a lot of stress. In this case, the gentleman had received bad advice from a friend, but once we were able to clear it up and explain to him why there was nothing that they could go after, everything was taken care of, and all was right in the world. If done properly, estate recovery is never an issue and only becomes a problem when people do not know how to properly plan.Please give us a call at 717-844-9639 and well set you up with a free consultation or register for a free workshop by clicking here.
Jan 25, 2024
Anticipating the Fate of Your Digital Assets
The fate of your digital assets is a query that has rapidly gained traction over the past few years and is poised to surge even further as we journey into the future. The realm of digital assets and estates, once an obscure concept, has now become a staple of modern existence. It is paramount that the Power of Attorney you employ meticulously outlines the powers bestowed upon the agent, encompassing provisions for digital assets. Furthermore, these provisions must seamlessly integrate into your Last Will and Testament, guaranteeing that explicit directives concerning your digital assets are established. This strategic approach empowers the executor with the authority to execute your desires. In the realm of estate planning, as with all matters, precision yields the best results. Presently, while its not commonplace for individuals to expressly address the management of digital assets, this is expected to evolve into the standard practice in the foreseeable future. As of now, its imperative to ensure that your legal documentation incorporates provisions that account for these assets. Additionally, one must consciously recognize these assets as integral components of the estate, and deliberate on whether they should follow the conventional trajectory to residuary beneficiaries or be assigned a distinct path.Indeed, your digital estate is a facet that warrants consideration, necessitating its inclusion in all documentation pertaining to estate planning. This proactive approach ensures that the digital realm, which has seamlessly woven itself into our lives, is seamlessly interwoven into the fabric of your comprehensive estate strategy.
Jun 21, 2024
Community Health Choices in Pennsylvania
As an estate planning attorney, its important to be aware of programs like the Community HealthChoices (CHC) Waiver that can help your clients as they age. The CHC Waiver is a program in Pennsylvania that was established in 2018 to provide choices for individuals to stay in their homes as they age and not be forced to enter a skilled nursing facility (SNF). This is great news for most people as they age because most folks prefer to remain in their homes as long as possible. With family support and programs such as this one, doing just that is often possible.If you have clients in the Commonwealth of Pennsylvania (including Adams, Lancaster, and York Counties), they are fortunate that the state has a very robust program. The program often allows individuals who require care at the SNF level to remain in their homes and not have to move to an SNF. The program is funded through Federal and State Medicaid dollars, such that if the individual meets the financial eligibility guidelines, services are provided at no cost to the participant.We have clients who receive anywhere from 2-3 hours up to 22 hours a day of care. The amount of care a participant receives depends on how much hands-on care is required. The approved hours are determined by Waiver program representatives. To be eligible for the Medicaid program, an applicant must apply for Medicaid and must be both medically and financially qualified for skilled nursing facility level of careessentially, the same guidelines used to determine eligibility for placement in an SNF with Medicaid funding. The key difference is that a CHC Waiver participant receives their skilled nursing facility-type care in a setting of their choosing, most often, in their own home.If you would like to learn more about the Community HealthChoices Waiver in Pennsylvania, visit https://www.dhs.pa.gov/HealthChoices/HC-Services/Pages/CHC-Main.aspx or call PA Enrollment Services at 1-800-440-3989 and ask about the CHC Waiver program. For information specific to aging services in York County, visit the Area Agency on Aging (AAA) in their new location at 2401 Pleasant Valley Road in York, PA, or call the AAA Information & Referral line at 717-771-9610 or 1-800-632-9073 and tell them that you would like to explore the CHC Waiver and any local services that might help you age in place in your home.
Feb 09, 2024
What Does a Client Care Advocate Do? A Guide for Navigating Elder Care
Caring for an aging parent or loved one often raises difficult questions. How do you know when they need additional support? What happens if their health changes? And where can you turn when youre unsure which care options are best?A client care advocate helps you navigate these decisions by identifying resources, coordinating care, and providing guidance as your loved ones needs change. Whether they want to remain at home or require additional assistance, professional support can help you make informed choices that protect their independence and quality of life.What Is a Client Care Advocate?A client care advocate is a professional who helps older adults and their families navigate healthcare services, long-term care options, and the challenges of aging. They help you understand your loved ones needs, explore available resources, and make informed care decisions.While healthcare providers address medical needs, a client care advocate focuses on practical concerns such as living arrangements, daily activities, personal preferences, and family support. For example, your mother may be able to live independently but struggle with transportation or household responsibilities. An advocate can help you explore services that address these challenges without immediately considering assisted living.When a client care advocate works alongside an elder law attorney, your family can address practical care needs and legal considerations through a coordinated approach. This can be especially helpful when changing care needs affect important financial or long-term planning decisions.What Does a Client Care Advocate Do for Your Family?A client care advocate provides guidance based on your loved ones circumstances. Their primary responsibilities include assessing needs, connecting families with services, and assisting during care transitions.Assess Your Loved Ones Care NeedsUnderstanding your loved ones situation is the foundation of effective care planning. An advocate considers their living arrangements, daily activities, support system, personal preferences, and potential safety concerns.If your father recently experienced a fall, for example, an advocate can help you identify concerns, explore available assistance, and prepare questions for healthcare professionals. This gives you a clearer understanding of the factors that may affect his ability to continue living independently.Coordinate Elder Care Services and ResourcesFinding appropriate elder care services can be challenging when youre unfamiliar with local programs and providers. Your advocate can help you identify resources based on your loved ones circumstances and the level of assistance they need.Depending on those needs, an advocate may help you explore: In-home care and personal assistance Meal delivery and transportation Adult day programs Assisted living and skilled nursing facilities Caregiver support and respite services Having guidance about available services can make it easier to compare options and determine which arrangements may be appropriate. Its particularly helpful when your loved one requires assistance from multiple providers.Support Healthcare and Living TransitionsA hospitalization, new diagnosis, or decline in mobility may require changes to your loved ones care arrangements. Your advocate can help you understand available options, communicate with providers, and prepare for transitions between care settings.For example, if your father is leaving a rehabilitation facility, you may need to determine whether he can safely return home. An advocate can help you evaluate his assistance needs and identify services that could support his recovery.How a Client Care Advocate Supports Aging in PlaceMany older adults prefer remaining at home rather than moving into assisted living or another care facility. However, aging in place requires balancing independence with safety and appropriate support. A client care advocate helps you evaluate whether your loved ones home environment can continue meeting their needs.Recognize Potential Safety ConcernsChanges in health or mobility can make everyday activities more challenging. Stairs, bathrooms, and household tasks may create safety concerns that werent previously present.Your advocate can help identify potential risks and explore resources such as home safety assessments, accessibility improvements, or additional in-home assistance. These adjustments may help your loved one maintain independence while addressing concerns about their living environment.Prepare for Changing Care NeedsA care arrangement that works today may need adjustments as your loved one ages. Someone who currently lives independently might eventually require assistance with personal care or supervision.For example, a parent living with dementia may initially need occasional help but require more consistent support as their condition progresses. An advocate can help you recognize when existing arrangements may no longer be sufficient and explore alternatives that reflect your loved ones changing needs.How Client Care Advocates Help Family CaregiversSupporting an aging loved one can be demanding when youre balancing employment, household responsibilities, and other commitments. You may spend considerable time coordinating appointments, researching services, and communicating with providers. A client care advocate offers guidance that can make these responsibilities more manageable.Simplify Care DecisionsWhen several concerns arise at once, knowing what to address first can be difficult. You might be worried about your parents safety while also trying to arrange transportation or additional assistance.Your advocate can help clarify priorities and identify practical next steps, allowing you to approach decisions with greater confidence. Instead of navigating unfamiliar care options alone, you have a knowledgeable professional who can help you understand the choices available.Navigate Family DisagreementsFamily members dont always agree about an aging parents care. One sibling may believe assisted living is necessary, while another prefers additional home support.A client care advocate can help your family evaluate available options while keeping your loved ones preferences and care needs central to the discussion. Having a professional perspective can make difficult conversations more productive, even when family members have different opinions.Client Care Advocate vs. Elder Law Attorney: Whats the Difference?A client care advocate and an elder law attorney serve different but complementary roles. Understanding the distinction can help you recognize how each professional supports your familys planning needs.An elder law attorney addresses legal matters affecting older adults, including estate planning, powers of attorney, Medicaid planning, asset protection, and long-term care considerations. A client care advocate focuses on practical care needs, resource coordination, and guidance through changing health or living circumstances.For example, if your mother needs skilled nursing care, an elder law attorney can explain relevant legal and financial planning options. Meanwhile, a client care advocate can help you explore care arrangements and communicate with providers.Working with both professionals allows you to consider immediate care concerns alongside long-term legal planning. This approach can help you make decisions that reflect your loved ones needs and your familys broader circumstances.The Role of a Client Care Advocate in Life Care PlanningLife care planning brings together legal guidance and care coordination to help families prepare for challenges associated with aging, long-term illness, or incapacity. While traditional estate planning generally focuses on legal documents and the distribution of assets, life care planning also considers your loved ones needs during their lifetime.Bellomo & Associates offers life care planning services that combine the experience of our elder law attorneys with the guidance of our client care advocates. This approach helps you address practical care decisions while considering legal and financial planning needs.Support as Circumstances ChangeYour loved ones care requirements may change following a diagnosis, hospitalization, or move to a different living environment. These developments can also affect your familys legal and financial planning needs.Through life care planning, our team helps you evaluate changing circumstances and consider appropriate next steps. By bringing care advocacy and elder law guidance together, we help you make decisions that reflect both current needs and long-term goals.When Should You Contact a Client Care Advocate?You dont need to wait for a medical emergency to seek guidance. Recognizing changes early gives your family more time to discuss preferences and consider appropriate care arrangements.Common signs that you may benefit from a client care advocate include: Difficulty with daily activities: Your loved one struggles with bathing, cooking, or household tasks. A new diagnosis: Youre uncertain how an illness may affect future care needs. Recent falls or hospitalizations: Youre concerned about safety or recovery at home. Increasing caregiver demands: Youre struggling to manage caregiving responsibilities. Long-term care questions: Youre considering assisted living or skilled nursing care. Family disagreements: You need guidance evaluating different care options. Even if your loved one is currently independent, discussing future needs can help your family prepare before circumstances become urgent. An early conversation may also help you understand which resources could become useful as their needs change.How to Prepare for Your First Meeting With a Client Care AdvocateYour first meeting is an opportunity to discuss concerns, understand available resources, and identify your loved ones care priorities. You dont need every answer beforehand, but gathering basic information can help make the conversation productive.Gather Relevant InformationReview your loved ones living arrangements, health concerns, daily routines, and current support services. Consider which activities have become more difficult and whether recent changes have raised safety concerns.You should also identify family members involved in caregiving and any immediate issues requiring attention. Having this information available helps your advocate better understand your loved ones situation and the support your family may need.Prepare Your QuestionsBefore your meeting, consider what youd most like to understand about your loved ones care. Think about their current needs, potential changes, and any decisions your family may be struggling to make.Helpful questions include: Which care options fit their current needs? What resources could help them remain at home? How can we prepare for changing health conditions? When should we consider a higher level of care? How will care coordination work as needs change? These questions can help you establish priorities and understand what to expect from the planning process. They also give you an opportunity to discuss your concerns before making significant care decisions.Find Client Care Advocate Services in York and Lancaster, PAWorking with professionals familiar with your community can help you locate appropriate services and navigate local care options. Having access to knowledgeable guidance is especially valuable when your loved ones needs change or youre considering unfamiliar care arrangements.Bellomo & Associates serves families throughout York, Lancaster, and surrounding Pennsylvania communities. Our elder law and life care planning services help families address legal considerations alongside the practical challenges of aging.Our client care advocates help you understand available care arrangements, identify resources, and respond to changing needs. Whether your loved one lives independently or requires additional assistance, were here to help you evaluate your options and make informed decisions.Get Trusted Elder Care Guidance From Bellomo & AssociatesUnderstanding what a client care advocate does can help you make informed decisions about your loved ones care. With professional guidance, you can explore appropriate services, navigate transitions, and prepare for changing needs without managing every responsibility alone.Bellomo & Associates combines elder law guidance with personalized care advocacy through our life care planning services. Were here to help you address todays concerns while planning for the future. Contact Bellomo & Associates to learn how our client care advocates can support you and your family.
Nov 06, 2026
.png)
How Much Does Estate Planning Cost?
If I had a quarter for every time Ive been asked this question, I would be extremely wealthy! What always bugs me about the question is that no one ever asks what the value of estate planning is. Or, by getting it done right, how much will I save my family in the long run? In the workshops that we host regularly, we often talk about what to be wary of when looking at costs. Yes, there are certain costs associated with having documents drafted, but there are different models that attorneys will use in terms of cost on the back end that will often make the cost much more affordable in the long run versus in the short run. Estate planning documents can range from $200 to several thousand dollars. In certain circumstances, if we are doing high-end planning for individuals with more than approximately 12 million dollars for a single person or approximately 24 million dollars for a couple, the cost can be upwards of $10,000. If an individual does not have that type of wealth, they would certainly not do that type of planning and would not need that type of plan. However, each plan that we offer in our office is priced not only based on the document itself but also on the knowledge that goes into the planning and the software that is used to generate the planning, as well as the value to the family. I could go on, giving at least 25 to 50 examples of people who tried to save a few dollars and ended up getting hurt to the tune of hundreds of thousands and in one case, millions of dollars, simply because they wanted to save a few dollars on the front end. Estate planning is very reasonable and is worth every penny. If you attend one of our estate planning workshops, you will learn the prices up front and will then be allowed to receive more education and move forward with the firm.
Jul 19, 2024
.png)
Effective Revocation of a Will: Ensuring a Smooth Transition
The question of how to properly revoke a Will necessitates careful consideration to ensure a seamless process. While the straightforward response is to shred both the original Will and all its copies, its crucial to bear in mind that the revocation should be accompanied by a replacement. Its unwise to assume that an outdated version of the document will remain accessible or that the original copy persists.My recommendation strongly leans toward promptly replacing the old Will with a new one and subsequently disposing of the original. Swiftly implementing the replacement will safeguard against potential complications. If you die without possessing the original Will to present to the Orphans Court, the Pennsylvania Intestate Law will come into play. This law essentially functions as the governments set of regulations dictating the distribution of your estate. While this blog post refrains from delving into the related intricacies, which we have covered extensively previously, it should serve to remind you of the existence of a governmental framework that will become involved, if necessary. In the absence of a valid Will, this framework gains authority, underscoring the necessity of having a well-structured Will in place at the time of your death. Upon confirming the preparation of a new Will to supplant the old one, you can confidently destroy the originals of the outdated document, secure in the knowledge that the new documents provisions will take precedence. We advise refraining from annotating documents with handwritten notes. It is advisable to preserve the new original that you intend to present to the Court in its pristine, unaltered state, mirroring its condition when initially drafted. This practice ensures the documents authenticity and reinforces its legitimacy in legal proceedings.
Jul 05, 2024
Considerations For Trust Type
Trusts are a major tool in estate planning. Trusts can be used for disability planning, probate avoidance, asset protection, and/or tax planning. Given the high thresholds for federal estate tax planning few individuals are concerned about tax planning. In this article we want to focus primarily on grantor vs. non-grantor trusts.When we are educating on trusts and the use of trusts in estate planning, people often get a concept confused. There is a difference between a grantor trust and a non-grantor trust. Simply stated, the assets in a grantor trust remain in the grantors Social Security number and are reported on the grantors personal income tax return. For a non-grantor trust a separate tax ID number will be obtained to hold the assets and you will file separate trust tax returns, this return is separate and apart from your personal income tax return. We will typically use grantor trusts for asset protection trusts and revocable living trusts. However, we often use a non-grantor trust for VA purposes as well as for estates that have a federal estate tax concern. Currently, a person has a federal estate tax issue if their estate is greater than $12.06 million and for a married couple $24.12 million. It is very rare in our practice to use non-grantor trusts, which require separate tax ID numbers and pay at higher trust tax rates, because not a lot of veterans are doing planning where they have to or want to give up complete control of their assets, and not a lot of estates are big enough to need federal estate tax planning. In those situations where we use grantor trusts, we intentionally put language in the trust so that is included in the persons estate, as well as subject to income tax. We include this language because we want to get a step-up in basis at the death of the decedent, and we also want the parent or client to pay the income taxes, because generally retired clients have a lower income tax burden than their children who are still working. There are a lot of other factors that go into what type of trust should be used and under what circumstances, but this provides a basic understanding of the difference between grantor and non-grantor trusts. If you would like to learn more about these and other trust concepts, I invite you to come to one of our free in-house workshops to learn more. We would be more than happy to assist. Just call our office or go to our website to enroll in a workshop at a date and time which is convenient for you.
Jan 20, 2023
My Spouse Has Been Diagnosed with Dementia. Are We Going To Lose Everything?
Has your spouse been diagnosed with dementia? You may wonder if you're at risk of losing everything, but the short answer is no. However, it's crucial to take the time to gather resources and learn about the diagnosis. Seek advice from healthcare professionals, organizations like the Alzheimer's Association, and other experts who can provide guidance. Once you feel comfortable with this information, it's wise to consult an elder law attorney to understand asset protection and the differences between care in assisted living facilities and long-term care facilities, as this can significantly impact how you'll pay for care. Planning for dementia can be challenging due to the variable progression of the disease. Some individuals may experience a slow decline while others deteriorate rapidly, and in certain cases, the journey could span 15 to 20 years or even longer. It's essential to seek advice early and regularly, allowing you to create a comprehensive plan and maintain a sense of control over the situation. In our office, our elder care coordinator, Meg Motter, assists families in developing a life care plan. This plan provides detailed instructions from start to finish and is continually adjusted as needed. It serves as a lifeline, empowering our clients' families to feel in control of the situation rather than being controlled by it.Considering the high costs of care, it's essential not to leave things to chance. Take action now and consult an estate planning and elder law attorney if you find yourself in this situation.To further support and equip you with valuable information, we invite you to register for our free educational workshop. Join us and gain valuable insights into dealing with dementia and securing your family's future. Don't miss out on this opportunity secure your spot today!
Jun 07, 2024
Understanding Deeds and Tenancy-Related Lingo
There are three main types of legal ownership of property. The first, Tenancy by the Entireties is reserved for married couples. If the property is deeded in both husbands and wifes names, it is presumed that upon the death of a spouse, the surviving spouse retains ownership. The law assumes that married couples share the property; however, clarifying language such as husband and wife tenancy by the entireties is good practice.The second type, Tenants in Common is reserved for folks who wish to transfer their individual property interests under their will. In other words, each property owner is treated under the law as having interest in their name alone, such that upon death, their specific interest transfers under their will and in turn, goes through probate. A married couple can own property with another individual (person outside the marriage) in this type of deed.The third type of ownership is Rights of Survivorship. It is reserved for persons who want to be able to transfer the property to the other owner upon their death. For example, if siblings own a joint property and the brother wants his share to go to his sister upon his death (and vice-versa), the deed will specify, David Dole and Debbie Dole, siblings with rights of survivorship. Such verbiage signifies that the two parties are siblings, but also that each wants to transfer to the other upon their deaths. In a slightly different scenario, wherein siblings want to each own 50% interest and be able to transfer it to their own children (or elsewhere), the deed would specify, David Dole and Debbie Dole, siblings, as tenants in common. In this scenario, David gets to transfer his 50% to whomever he wishes, and Debbie gets to transfer her 50% to whomever she wishes. A caution herebe sure to secure legal counsel about the potential for future family disputes before choosing this option: What if, down the road, one party wants to sell and the other wants to keep the property? Candid dialogue with an attorney is key to identifying the best arrangements for your unique situation and mitigating the risk of future family turmoil.In summary, clear, specific language is paramount in crafting deeds. The goal is to ensure that if we were to fast-forward 30+ years and imagine a title surveyor reviewing the deed, we would be certain that the surveyor would fully understand the original intent of the document and know without a doubt exactly what transpired many years before.Please give us a call so you can attend our free workshop by registering here or call schedule 717-844-9639 and well set you up with a free consultation.
Mar 07, 2023
My Loved One Wants To Stay Home, But We Are Open To The Possibility Of Other Arrangements
We often make recommendations to local handymen to be able to make changes or adaptations to the home, and we certainly have numerous referral sources for medical and non-medical care in York, Lancaster, and surrounding areas. We are very lucky to have as many wonderful resources as we do, and we certainly like to take advantage of each and every one of them to allow people to remain in their homes.One thing that has definitely become more of the norm recently is people moving into independent living communities such as 55-plus communities or personal care and assisted living facilities that have independent care options as well as continuing care communities.One thing that we often hear from our clients after they move is that they wish they wouldve moved much sooner. We often hear them explain that they believe that they wanted to remain home at all costs because they believed that that was the right thing for them but once they moved into a community, they realized the social aspects of living with others and being able to participate in community activities, bus trips, and other engaging and meaningful opportunities. I have honestly never had a client come into my office who moved and said I shouldnt have done that. Typically it is I wish I wouldve done it sooner so that I couldve enjoyed those opportunities much more.My advice to clients is that they should start looking at the options and opportunities while they are healthy and could enjoy them. Start taking tours and talking to people who live in the communities to learn about the socialization opportunities that they offer.We believe in educating early and often so that people know what options are available and hope that this article sheds some light on the opportunities and possibilities that a community can offer you. Not only will there be caregivers and the ability to grow and to age in place, but also socialization aspects can oftentimes make people live longer and have them live a happy, healthy life towards the end.Both remaining at home and moving into a community offer different opportunities and fulfill different needs. We encourage you to explore both options and to have an open mind about the possibilities of how both can provide you with opportunities and maybe your first reaction wont be how you feel later in life. If you would like to learn more about estate planning and elder law and how you can help your loved one's age in place or have them move to a community, please give our office a call at 717-844-9218.
Jul 07, 2023
.png)
I reside in a different state but wish to participate in my parents estate planning. Is this a feasible option?
Certainly, one significant factor that has altered the landscape of meetings is the impact of COVID-19. This has led to a noticeable increase in peoples comfort with conducting meetings via platforms like Zoom. For at least a year, the majority of our meetings were conducted exclusively through video conferencing. During this time, we have encountered few issues, and even our octogenarians and nonagenarians have been able to successfully connect and navigate the process.Incorporating a family member residing out of town into a telephone or Zoom video conference is easily achievable. We strongly encourage the involvement of family members in all meetings and have the capability to easily include participants who are not physically present in our office.When scheduling an appointment, kindly inform us if there will be a mix of in-person and virtual attendees, and we will seamlessly accommodate this arrangement within our planning process. We eagerly anticipate collaborating with you and your family.
Jun 28, 2024
Estate Planning for the Sandwich Generation: Protecting Your Parents a
You are scheduling your childs dentist appointment while coordinating your dads cardiology visit. You are reviewing college savings plans while quietly wondering how long your moms retirement savings will last. If that sounds familiar, you are part of what many call the sandwich generation. You are caring for aging parents while raising children or supporting adult kids. You are the steady one. The organizer. The problem solver. And amid all that responsibility, one important question is often set aside. What happens if something happens to you? At Bellomo & Associates, we regularly work with families who are stretched in two directions at once. Estate planning for the sandwich generation is not optional. When two generations depend on you emotionally and financially, your estate plan must protect both at the same time. Why the Sandwich Generation Needs a Different StrategyWhen you care for children and support aging parents, you are the bridge between two generations. If that bridge weakens unexpectedly due to illness, injury, or worse, everyone feels it. If you become incapacitated: Your children may lose their primary caregiver and financial organizer Your parents may lose the person managing appointments, medications, or bills Your household finances may stall Important medical decisions may be delayed Estate planning for the sandwich generation must address: Your own death or incapacity Your parents declining health Guardianship and financial protection for your children Without planning, one unexpected event can create legal confusion and financial instability for everyone who depends on you. Part One: Protecting Your Own Household FirstBefore you can effectively support your parents, you must secure your own home base. 1. Name Guardians for Minor ChildrenIf you have minor children, your estate plan must clearly state who would care for them if you and your spouse cannot. A properly drafted will allows you to: Name guardians for minor children Appoint an executor Direct how your assets are distributed Without a will, state law decides who inherits your property. Even more importantly, a court decides guardianship. Families often assume a grandparent or sibling would step in, but assumptions do not carry legal authority. Naming guardians is not just paperwork. It is one of the most loving decisions you can make for your childrens stability. 2. Consider Trust PlanningDepending on your financial situation, a revocable living trust may help avoid probate and give you control over how your children receive assets. Instead of distributing everything outright at age 18, you can structure distributions for: Education Housing Milestone ages Health and support needs This adds a layer of maturity-based protection and thoughtful guidance. 3. Plan for Your Own IncapacityMany families focus only on what happens after death. For the sandwich generation, incapacity planning is equally important. If you are hospitalized or temporarily unable to manage finances, who pays the mortgage? Who signs school forms? Who handles your parents care coordination? Your plan should include:Durable Financial Power of Attorney Allows someone you trust to manage: Bills Bank accounts Investments Real estate Without it, your family may need court involvement to gain authority. Health Care Power of Attorney Name someone to make medical decisions if you cannot. Living Will or Advance Directive Outlines your preferences for life-sustaining treatment and reduces the emotional burden on loved ones. Incapacity planning ensures your responsibilities do not unravel simply because you cannot act temporarily. Part Two: Planning for Aging ParentsSupporting aging parents adds another layer of complexity. Many adult children assume their parents have something in place. Unfortunately, outdated or incomplete documents are very common. 4. Confirm Your Parents Documents Are CurrentEncourage your parents to review and update: Financial Power of Attorney Health Care Power of Attorney Living Will Will or Revocable Living Trust Timing matters. If cognitive decline begins before documents are signed, options become limited. We have seen situations where no valid power of attorney exists. Banks refuse access to accounts. Medical providers cannot share information. Families are forced into court proceedings that could have been avoided. Proper authority allows you to help your parents without unnecessary obstacles. 5. Address Long-Term Care PlanningLong-term care is one of the most overlooked issues for families in this stage of life. Many older adults will require some level of assistance. Without a funding strategy, care costs can quickly deplete savings and create stress for everyone involved. Planning may include: Reviewing long-term care insurance Understanding Medicaid planning strategies Protecting assets for a surviving spouse Creating caregiver agreements when a child is providing paid care Failing to address care funding often leads to family tension. Clear planning preserves dignity and relationships. Part Three: Protecting Yourself from Financial BurnoutMembers of the sandwich generation often feel financial pressure from all sides. You may be helping your children with education expenses while assisting your parents with medical or housing costs. Meanwhile, your own retirement savings may quietly take a back seat. Estate planning is not just about documents. It is about coordination. Consider: Reviewing and updating beneficiary designations Ensuring financial support to parents does not unintentionally reduce your childrens inheritance Aligning your estate plan with your long-term retirement goals Clearly documenting financial arrangements to prevent misunderstandings among siblings A coordinated strategy protects your generosity without sacrificing your own future. Common Mistakes to AvoidEven well-meaning families make avoidable errors: Waiting until a medical crisis forces action Avoiding uncomfortable conversations with parents Assuming siblings agree on caregiving roles Failing to update documents after life changes Believing estate planning only matters after death Proactive planning reduces stress and prevents disputes during already emotional times. A Simple Self-CheckIf you are part of the sandwich generation, ask yourself: Have I named guardians for my minor children? Do I have financial and medical powers of attorney in place? Do my parents have updated legal documents? Is there a long-term care funding strategy? Would my family avoid court involvement if I were incapacitated tomorrow? If you are unsure about any of these answers, your plan may need attention. You Are the Bridge Between Two GenerationsEstate planning for the sandwich generation is about more than legal paperwork. It is about stability. It is about preserving dignity for your parents and security for your children. You are carrying responsibility upward and downward at the same time. Your planning should reflect that reality. This is about protecting your children. It is about honoring your parents. It is about reducing confusion and preventing unnecessary court involvement. If something happened tomorrow, would the people who depend on you have a clear direction and legal authority? At Bellomo & Associates, we help families create coordinated estate plans that protect every generation involved. Register for a Workshop to learn how to build a plan that supports your children, your parents, and your future with clarity and confidence.
Mar 20, 2026
Why Young Individuals Need Planning as Much as Older Adults
There is definitely a false belief that estate planning and elder law are only for individuals who are elderly and who have amassed a ton of wealth. Certainly, individuals in that category absolutely need to plan, but that does not mean that younger individuals should not also put a plan in place ahead of time.When an individual reaches the age of majority, which is 18 in the Commonwealth of Pennsylvania, they are presumed to be able to make decisions for themselves and not need the assistance of anyone at that point. Oftentimes, young adults don't realize that once they turn 18, getting a financial power of attorney, medical power of attorney, and Last Will and Testament can be absolutely necessary.Many of our clients are college students, going away without mom or dad for the first time, and somewhere within the first couple of years, they either end up at the hospital or they end up asking mom and dad to call the school to ask questions about billing or something else. To their surprise, their parents are no longer able to just make decisions because they are over 18 and are expected to be adults.We recommend that all college students going off to school enter into a power of attorney providing the authority for the parents to be able to make their healthcare and financial decisions if need be. If nothing else, allowing the parents to be able to call the school or other institutions and ask questions. This is often overlooked by many parents and can cause a lot of heartbreak and stress if their child is injured or in need of assistance.Although most college students and young individuals have not amassed a ton of wealth, having the document in place specifying who is going to receive the assets and who will be the individual responsible for carrying out those wishes (executor) can often save lots of heartbreak. Yes, it is true that the Commonwealth of Pennsylvania has a statute called intestate succession which does provide what would happen to assets if an individual dies, but oftentimes it is not what a person would want.The intestate succession rules are archaic and old and do not necessarily follow the wishes of a current situation. For example, we recently had a problem where the parents who are estranged had to administer the estate of their daughter who passed away. The emotional toll that it took on the parents and the family for them having to put up with each other was undoubtedly probably not what the daughter wanted and had she had her wishes in place it would have eliminated not only the heartache of losing a child but them having to fight and remind each other every day of why they were divorced in the first place.We also recommend that young adults have documents that are properly put in place (so that others can get access to digital assets). Digital assets often include photos and videos, electronic media, stored data, apps, etc. Young adults are typically ones who have proportionately more of these than others, and if the power of attorney or the Last Will and Testament does not provide for that, it can cause lots of time delays and issues.Hopefully, this article was able to express the need for individuals to have planning in place, particularly young adults who often don't think that it is necessary. If you would like further information or would like to learn more about the content in this blog, please contact our office at (717) 845-5390
Sep 22, 2023
How to Help Your Loved One Avoid Isolation: A Guide for Families and Caregivers
As an elder law attorney, I often see how social isolation can deeply affect the lives of seniors. While life care planning ensures that older adults are protected financially and medically, addressing emotional well-being is just as critical. Seniors who feel isolated are at a higher risk for depression, anxiety, cognitive decline, and even physical health complications. With the COVID-19 pandemic amplifying feelings of loneliness, families must take proactive steps to support their loved ones and keep them engaged. This article will provide practical, compassionate strategies to help your loved one avoid isolation. While every family situation is different, the key is to foster meaningful connections and create opportunities for seniors to stay active, both socially and mentally.Understanding the Impact of Isolation on SeniorsIsolation is more than simply being alone. Many seniors live by themselves, and while some enjoy independence, others experience deep loneliness when social connections are limited. Studies show that chronic loneliness can: Increase the risk of dementia by nearly 50%.Raise the likelihood of heart disease and stroke.Weaken the immune system.Lead to higher rates of depression and anxiety. As an elder law attorney, I encourage families to view isolation not just as an emotional issue, but as a serious health risk. Just as you would schedule a medical check-up or review an estate plan, it is important to make time to check in on your loved ones social and emotional needs.Step 1: Use Technology to Stay ConnectedOne of the simplest yet most effective ways to reduce isolation is through technology. Video conferencing platforms such as Zoom, FaceTime, or Skype allow families to see each other even when distance or health concerns make in-person visits difficult. Here are a few ways to make technology part of your loved ones routine: Weekly check-ins: Schedule a recurring time each week to call. A consistent routine gives your loved one something to look forward to.Virtual meals together: Share dinner or coffee over a video call. Even though you may be in different locations, enjoying a meal together fosters connection.Celebrations and events: Invite your loved one to virtual birthday parties, holiday gatherings, or grandkids school performances streamed online. These small steps provide comfort, help maintain strong family ties, and allow you to observe any changes in your loved ones health, such as hearing or vision problems. Step 2: Encourage Social Engagement Through Clubs and ActivitiesMany seniors find joy and purpose when they are part of a community. Encourage your loved one to join clubs, hobby groups, or organizations designed for older adults. With the shift to online platforms, many opportunities are now available virtually, making it easier for seniors to participate from the safety of home. Examples include:Book clubs virtual or in-person, depending on comfort level.Community center classes exercise, art, or cooking.Senior support groups especially helpful for those coping with grief, illness, or caregiving responsibilities. These groups not only provide social interaction but also give your loved one new stories and experiences to share with you during visits or calls. There may even be opportunities for you to join in on one of their activities, further strengthening your bond.Step 3: Promote Physical Activity and Outdoor TimePhysical activity is beneficial for both body and mind. Encouraging your loved one to get outside, even for short walks, can help boost mood, improve sleep, and provide opportunities for casual social interactions. Consider these activities with your loved one:Walking together in a local park.Gardening as a shared hobby.Attending low-impact exercise classes designed for seniors. When seniors feel stronger physically, they are more likely to engage socially and maintain independence. Physical activity also directly supports their well-being and decreases the risk of premature physical deterioration.Step 4: Create a Regular Visiting ScheduleIn-person interaction is still one of the most effective ways to combat isolation. Even short visits can make a big difference in your loved ones day. If you live nearby, try to establish a regular visiting routine. Consistency builds anticipation and helps your loved one feel valued and cared for. These visits dont need to be elaboratesometimes just sharing a cup of coffee, watching a favorite show together, or going for a short walk is enough to lift their spirits. If distance is a challenge, coordinate with other family members, friends, or neighbors who can stop by. Sometimes, having multiple people share the responsibility ensures that your loved one sees someone regularly. This also creates a wider circle of support, giving your loved one opportunities to connect with different people and personalities. You might even consider creating a shared calendar to keep everyone organized and committed, which helps avoid long gaps between visits.Step 5: Explore Senior Transportation and Community ResourcesMany seniors stop engaging socially because they no longer drive. Loss of transportation can quickly lead to isolation, making it harder to attend events, medical appointments, or even simple outings like grocery shopping or visiting friends. To help overcome this challenge, look into local senior transportation programs or community shuttle buses that are specifically designed with older adults in mind. Some areas also offer volunteer driver programs, where trusted community members provide safe, reliable rides at little to no cost. By arranging dependable transportation, you give your loved one the freedom to remain active and involved in the world around them. Faith-based communities, senior centers, and local nonprofits often have programs designed to keep older adults engaged and connected. These organizations may not only provide transportation but also host social activities, group outings, and support services that encourage seniors to build new friendships. Encouraging your loved one to explore these resources helps them maintain a sense of independence while also opening doors to meaningful community involvement. Even small outings, like attending a weekly class or a local church service, can make a tremendous difference in their emotional well-being and help prevent feelings of loneliness.Step 6: Encourage Pet CompanionshipIf your loved one can care for an animal, having a pet can significantly reduce loneliness. Dogs and cats provide unconditional companionship and encourage routines such as walking, feeding, and grooming. These daily responsibilities can create a sense of purpose, helping seniors feel needed and engaged. Studies have also shown that interacting with pets can lower stress, reduce blood pressure, and even improve heart health, making them a source of both emotional and physical benefits. Pets also spark opportunities for social interaction, whether its chatting with neighbors during a walk or sharing pet stories with friends and family. For seniors who may not be able to care for a pet full-time, there are still many wonderful alternatives. Pet therapy programs, where trained animals visit homes, senior centers, or nursing facilities, can provide comfort and joy without the long-term responsibility. Another option is fostering pets through local shelters, which gives seniors temporary companionship while helping animals in need. Even spending time with a family members or neighbors pet can bring many of the same uplifting effects. These options allow older adults to experience the benefits of animal companionship while ensuring their lifestyle and health needs are respected.Step 7: Watch for Warning Signs of Severe IsolationWhile occasional loneliness is normal, prolonged isolation can lead to serious health problems. Be mindful of signs such as: Withdrawal from activities they once enjoyed.Changes in eating or sleeping habits.Increased forgetfulness or confusion.Expressions of hopelessness.If you notice these warning signs, it may be time to seek additional support. Consider talking with a doctor, counselor, or elder care professional to explore solutions. Early intervention can make a significant difference, helping to prevent more serious mental or physical health complications. Its also important to keep communication open, gently encouraging your loved one to share their feelings without judgment. By staying observant and proactive, families can ensure their loved one receives the care and attention they need to maintain both emotional and physical well-being.Legal and Care Planning ConsiderationsAs an elder law attorney, I often remind families that emotional well-being is directly tied to overall quality of life. When planning for the future, consider including care provisions that address social needs. For example: Powers of attorney should designate someone who will not only handle finances and healthcare but also advocate for the individuals daily needs.Long-term care planning should factor in opportunities for social engagement, whether through in-home caregivers, adult day programs, or assisted living facilities.Estate planning conversations can also be an opportunity to discuss the importance of staying socially connected and supported.Bellomo & Associates Can HelpIsolation is a common issue among seniors, but it is not something families have to accept as part of aging. With the right support, older adults can continue to build meaningful connections, stay active, and enjoy a sense of purpose in their daily lives. Even small, consistent gestureslike a video call, a shared meal, or a friendly visitcan provide comfort and significantly improve emotional well-being. When families take the time to recognize and address the social needs of their loved ones, they help protect not only mental health but also overall quality of life. At the same time, planning ahead with an elder law attorney ensures that these emotional needs are supported within a broader care strategy. Legal tools such as powers of attorney, long-term care planning, and estate planning can be tailored to account for both medical and social considerations, ensuring seniors are not only protected but also meaningfully engaged. At Bellomo & Associates, we believe that true elder care planning goes beyond financesits about preserving dignity, independence, and connection. If you have questions about how to safeguard your loved ones future, please schedule a consultation with us today. Together, we can create a comprehensive plan that supports their legal, medical, and emotional well-being for years to come.
Oct 03, 2025
When are My Powers of Attorney Active?
Powers of attorney are often drafted differently by different professionals. In our office, we draft our powers of attorney to be effective immediately so that the principal is authorizing the power to be used by their agent now. However, we do not have the agent sign the acknowledgment pages, acknowledging that they are going to act in the best interest of the principal and not steal from the principal and not comingle assets of the principal, and only have them do that at the time when they need to act.At Bellomo & Associates, we have a document signed by the principal, telling our firm only to give out the originals and to only have the agent sign the acknowledgment when and if the agent actually needs to use them, which would only occur if the principal instructs our firm to give the documents to the agent, or the principal is incapacitated. Yes, we do potentially take on liability because it is up to us to ensure that the agent has not received the documents before they are supposed to, but this is the mechanism that protects the principle that the agent will not have the documents prior to when they actually need them.Over 20 years of practice I have found that agents always want to do the right thing for the principal and always want to be there for the person that they are acting for. In the cases that I have found that an agent has taken advantage of their power, it almost is always a situation of the agent becoming desperate for one reason or another, and I have always said Desperate people do desperate things. It is mainly for this reason that we keep the originals of the documents protected in our office so that the agents do not have them to be subjected to the whims of a desperate situation.In the event that the agents need or want to use the documents, they will have to sign the acknowledgment pagers prior to using the document. We often receive calls from agents wanting to know why they did not sign the acknowledgments yet, and our answer is that you do not need to act on behalf of the principal yet because he or she is still able and willing to do it themselves.While there is certainly no perfect answer to the best way to handle this situation, we believe that our solution provides the most effective way to get the document in place, but in such a way that its still protected as much as possible until it needs to be used.It is important that you receive advice from a professional about the best way for you and your family to execute a power of attorney and whether or not the agent should sign the acknowledgments now or only when and if they need to use them.If you are looking for advice in regard to powers of attorney, please call our office at 717-844-9639 or click the link here and we will contact you.
Apr 28, 2023
Now is a Good Time to Review Your Estate Plan.
It has certainly been a strange year and it feels as though we are finally heading out of it and things are getting back to normal. It makes me very happy to hear everybody talking about all of their upcoming plans for travel and trips to visit family because they missed out on a lot of planned events this past year.Let me tell you what has really hit home for me, is how painful lack of planning can be and how it can affect your family in many ways. There are far too many lessons that we have learned from the past year, but one, in particular, is how a lack of planning can devastate a family.Before you head out on all of your great adventures and trips, please take a moment for yourself and put your own oxygen mask on. Please pull out your estate planning and take a quick look at it. Make sure that the documents read the way that you want them to read and that you understand them.Furthermore, make sure that all of your beneficiary designations on your life insurance and retirement accounts match what you intend for them to do and do not incorrectly believe that your Will controls how those assets are distributed.As we have stated in many other blogs and articles, the beneficiary designations on these items are the most important thing and will trump what you have in your Will. Just confirm that your plan is the way that you intend it to be and that there are no unintended consequences.If you have not had it reviewed by a professional in the last three or four years, take the time now to bring it to someone to review to ensure that everything is the way that it needs to be.We also encourage you to take the time, once your documents are review and updated as necessary, to talk to your family about your planning when you are on your adventures and at family gatherings to make sure that everybody knows what your wishes are and what your planning is for the future.These simple steps will save heartache and avoid hurt feelings. The time is now to review prior to heading out. Enjoy your travels and please be safe.If you are looking for advice in regards to estate planning, please call our office at 717-844-9639 or click the link here and we will contact you.
Apr 19, 2023
Factors to Consider When Selecting a Guardian for Your Children
When I ask my clients what is driving them to come to see me for estate planning, I usually get the same answer; we want to make sure that our family is taken care of if something ever goes wrong. Its a simple enough objective, but all too often clients are only thinking in terms of financial help for their family. One of the most important things a parent should include in a Will has nothing to do with money, it is deciding who would be their preferred choice of guardian for their minor child(ren) in the event of the parents death.A guardian is a Court appointed person who can legally care for a child who has lost both of their biological or adopted parents. A guardian is appointed only by a Judge after judicial proceedings. During that proceeding, the Judge will consider evidence to decide who is the best person to care for that child now that the parents are deceased. An overwhelming piece of evidence in that decision would be the deceased parents choice of guardian, which is commonly listed in their Will. Here are some factors to consider when trying to decide who would be a good choice of guardian for your child(ren):Have that discussion. No matter who you ultimately decide would be a good choice of guardian for your child(ren), be sure to have a talk with that person to make sure this is a responsibility they are prepared to take on. Serving as a guardian for a child is an awesome responsibility, make sure your guardian is willing to assume this responsibility before making your choice.Plan for the immediate future, not forever. Remember, you can always revise your Will in order to change your list of preferred guardians over time. Therefore, choose guardians who would best serve your child(ren) now, and in the next few years. The right choice for a toddler may not be the right choice for a teenager.Have a backup plan. Never just list one choice for the guardian of your child(ren). It is important to always list at least one backup choice. Your first choice may not be able to serve for many reasons, so always be sure to include a second or third choice.What if I dont think anyone in my family is the right fit? Your preferred choice of guardian for your children does not have to be a family member. You can choose anyone who you feel would be best suited to serve in that capacity. When making the decision as to who should serve as a guardian the Court simply makes that decision based upon what is in the best interest of the child. The Court is not restricted to only considering family members.Remember, dont get caught up in just focusing on financial oversight. Engage in a thoughtful analysis of what the real-world implications would look like if your guardian were doing your parenting. From daily life to finances, and everything in between. By doing so, you will ensure your children are best cared for if the unimaginable would ever occurs.
Jun 08, 2023
Why Didnt the Nursing Facility Tell Us?
I recently met with a client whose husband was placed in the nursing facility about four years ago due to dementia. She did everything she could to keep him at home, but ultimately the behaviors (unfortunately in his case, including violence and aggression) became too much, and she was no longer able to care for him at home. Overall, she has been very pleased with the care that he has been receiving and had no complaints. I asked why she was coming into my office and what she was hoping that I could help her with, and her response was, All I have left is a couple thousand dollars and a cabin that means the world to the family. I was able to give her great newswe were able to preserve the couple thousand dollars and the cabin, and she did not lose anything. She was ecstatic and could not thank us enough for our advice and assistance.As she was getting ready to leave my office, I could tell that she was thinking about something and that something was bothering her.Before I opened the door to the lobby, I asked her, Is there anything else that you would like to discuss? Do you have more questions? She said, Yes, I have oneIf I had come to you four years ago, would there have been anything else that you could have done to help me? My response was, Yes. I would have been able to protect 100% of the assets. Her demeanor immediately changed and she looked me in the eye and asked, Why didnt the nursing facility tell me?My response was, Maam, the nursing facility is not your lawyerthey do not have a duty to you. Their job is to provide the best possible care that they can for your husband and get paid for their services. They did absolutely nothing wrong.I totally understood her frustration, but at the same time the nursing facility is in the business of caring for people, not the business of advising families on the nuances of asset protection laws. Facility employees provided advice and help with the Medicaid application process(instructing her to spend down the couples assets for monthly care costs), believing that what they were telling her was correct. They likely believed that their advice was the best, not only for them, but also for her.Unfortunately, most billing departments in nursing facilities dont fully understand asset protection laws and how they can work. It is imperative that families seek professional help from an elder law attorney as soon as a loved one enters a nursing facility, so that you and yours are not left wondering, Why didnt someone tell me?
Mar 20, 2023
Getting Access to Assets and Benefits After a Death
Oftentimes, the death of a loved one is the hardest thing that any of us will endure. Not only did we lose the individual physically and emotionally, but in certain instances the financial impact can also be great. We are often asked in our firm what needs to occur after death, and we have provided other blogs and articles specific to that situation. This blog generically gives direction on how you can get access to the benefits and assets of your loved one. Jointly owned assets: These are the easiest assets to gain access to because the spouse or child is already a joint owner and simply needs to notify the financial institution or company that they are the surviving spouse or joint owner. You may need to provide a death certificate to take the deceased loved ones name off of the account. Also, be sure to check the taxpayer identification number associated with the account, which may need to be changed to that of the surviving joint owner. Assets that name a beneficiary:These are also fairly straightforward assets for a beneficiary to be able to obtain because they merely need to contact the company if they were named as a beneficiary on an account such as life insurance, an annuity, or other product that has a beneficiary listed. These also include accounts that have individuals named as an in-trust-for-beneficiary, a transfer-on-death beneficiary, or a payable-on-death beneficiary. They are all fancy terms, but ultimately if the beneficiary is named, they will be able to fill out some paperwork and will receive those assets fairly promptly with not a lot of problems or delays. Veterans benefits:If the individual who passed away was a veteran, there may be additional monies and funds that may be payable to the spouse. In some cases, benefits can even transfer to children. The benefits themselves are not difficult to receive, but the Veterans Administration has very particular and specific requirements that must be met for eligibility. An experienced attorney can assist with and provide guidance in this area. Social Security benefits: Social security benefits, including death and monthly survivor benefits, can also be claimed after the death of a loved one and will go to a surviving spouse or potentially to dependent children. The benefits themselves are not difficult to obtain, but it is essential that you meet the strict eligibility requirements. Survivor benefits must be immediately requested because they are not retroactive if they are claimed after a certain amount of time. The Social Security death benefit is only payable to a spouse and not to children. These are simple steps that you can take to be able to receive assets and benefits that are available to you upon the death of a loved one. If none of these above apply because the asset was in the individual's name alone without a beneficiary, it will be essential for you to seek the advice of a qualified attorney who will be able to help you through the probate process. We hope that this blog has assisted in understanding different benefits and how a spouse can obtain them easily. If you have any further questions or would like to get additional information, please reach out to our office at 717-220-8312 or check us out on the web at www.bellomoassociates.com.
Oct 25, 2023
.jpg)
Elder Law Without Care is an Incomplete Solution
Throughout my twenty-year career in Estate Planning and Elder Law, I have always found pride in our team here at Bellomo & Associates. While we strive to do the very best for our clients, and although my pride in our firm has remained strong, I continued to feel as though we needed a key component. For a long time, I could not put my finger on exactly what this missing component may be until I met a friend who had begun to incorporate Life Care Planning into his firm. He explained how they had hired a Client Care Advocate to serve his clients better and after several conversations, I knew that this was exactly what we were missing. Providing our clients and families with clear answers that help them feel confident and knowledgeable about their decisions is a priority. There were few things more frustrating than being unable to provide the answers and support they needed when we got questions such as, How do I make sure that Mom is safe at home, or Is assisted living the right choice, or When should we consider a skilled nursing facility? We would refer to outside organizations to get families the help they needed, but I knew that ultimately, I wanted our firm internally equipped to help in this area. For nearly three years, our firm has been a member of the Life Care Planning Law Firms Association. Meg Motter, a licensed social worker, and our Client Care Advocate, brings thirty-five years of experience to the table. She helps families assess their current needs, answer any questions, help to provide the right course of action for their individual needs and wants, and so much more. Being able to add this piece to our firm has served to benefit both our clients and our staff. We are now able to support and advise in ways we could not have before. It is a gift to be able to care for our community in this way. If you are interested in learning more about Life Care Planning and specifically about how our Client Care Advocate can assist you and your family in putting together a plan, please call our office at (717) 208-2899, where we would love to help you.
Jan 17, 2025

The Value of Living Wills
When I ask our younger clients if they would like to complete a Health Care Directive, they often say no, stating that they are too young to need such a thing. My response is always, What does age have to do with end-of-life decisions? I can think of at least fifty examples of a young person ending up in the end stage of life and a family member having to make difficult decisions on their behalf. Please, do not get lulled into complacency by thinking that age is protection. I was in my doctors office recently when I noticed a large collage talking about the importance of having a Living Will or Health care Directive. It emphasized the importance of having such a document, regardless of how old you are, reinforcing to me what our office always stresses to our clients and the community. A Health care Directive is a document in which each of us tells our loved ones how we want the end of our life to be handled. When we are in a permanent vegetative state, a permanent state of unconsciousness, or in the end-stage of a medical condition, all with no reasonable likelihood of any significant recovery, it provides answers such as Do you or do you not want to be resuscitated, to you want tube feeding, and appoints an agent that can serve to make decisions for you once you are unable to do so yourself. One of the quotes on the doctors display said, End-of-life decisions should not be made at the end of life. Another said, For human beings, life is meaningful because it is a story, and in stories, endings matter. Another said, I have an Advanced Directive, not because I have a serious illness, but because I have a family. Most of us know what medical decisions we want at the end of our lives, but have we communicated that to our family and loved ones? When we meet with clients to help them create estate planning documents, we always point out to them that they have the option in their Health Care Directive of deciding what, if any, extraordinary measures they want to be taken at the end of their lives. Once they select those options, we then come to perhaps the most difficult question of all: Should these instructions be binding on their families and providers, or do they want their loved ones to be able to override their decisions? Many opt for binding instructions so their loved ones do not have to make any of those difficult decisions in the heat of a devastating crisis. Either way, they have expressed their desire to guide their loved ones. Age is not a factor in creating a Health Care Directive; tragedy can strike unexpectedly at any age. The expense is low, but the peace of mind comes from knowing that when our time comes, we have already made those decisions for ourselves and our loved ones. So, start the conversation with your family. Communicate your wishes to them and urge them to communicate theirs to you. Then, go to a qualified estate attorney and put those wishes on paper so that when your time comes, all involved, including your medical providers, know how you want the end of your life to be managed. We offer FREE Workshops each week. You can also call our office at (717) 208-2899.
Feb 28, 2025
My Loved One is in a Nursing Home, is it too Late?
My loved one is in a nursing home, is it too late? The simple answer is no, it is not too late! The only time it is too late is when there are no assets available or when all of the assets were previously gifted. If the family member in the nursing home still has assets, it is not too late.The confusion in many of these cases arises because most individuals believe that because the nursing home didnt mention that anything could be done, that means that nothing can be done. Unfortunately, it is not the nursing homes business offices job to tell a family how to protect assets. It is their job to make sure that they provide great care for their residents and get paid for their services. To be completely honest, most of them do not even realize that anything can be done because when you look at the law on its face, it doesnt really mention anything about it. You have to dig a bit deeper!If you have a loved one that has entered a nursing home, please contact our office immediately so that you can watch our educational workshop and have a free consultation where we explain your options to you before you make any decisions. It is our job to protect you and your family and to protect as much as we possibly can for our clients. Allow us to do our job and allow the nursing homes to continue to do their job to provide care and get paid for their services.Remember, it is not too late. If a loved one is already in a nursing home, please give us a call so you can attend our free workshop by registering here or call schedule 717-845-5390 and well set you up with a free consultation.
Dec 16, 2022
Why You Should look at LTC Insurance
The bottom line is that LTC (long term care) insurance has come a long way. There are new types of LTC insurance and even a PA Partnership Care Plan. We encourage our clients to talk to an agent to determine if it is right for them. Specifically, we like the riders that keep our clients in their home and in an assisting living facility as long as possible.I am not a financial advisor, nor am I licensed to sell insurance, nor can I receive any commission from anyone who does. Thus, I have no incentive to say that I think long-term care policies are important; the reasons may be different than what you might expect. I always hear the push-back that long-term care insurance is very expensive, and that, in many cases, if you dont use it, you lose it. Since approximately 2009 Pennsylvania has become a part of something called a partnership care plan.Essentially, for example, if you have $200,000 of long-term care insurance that pays out, the state will allow you to exempt an additional $200,000 of assets at the time that you enter a nursing home, and still qualify for Medicaid. When the plan first came out, the concern was that the state would take over long-term care insurance, but so far that has not occurred.I believe the reason is because these are still traditional long-term care policies that, if you dont use it during your lifetime, you lose its value at your death.However, more recently long-term care insurance companies have come out with what is called a hybrid policy, which is a life insurance policy that has a rider for long-term care insurance. The main reason that I like long-term care policies, specifically the ones that have riders to provide for care in the home or in the personal care home, is because more and more, people want to live at home as they age and until they die. In all of my years of practice, no one has ever told me that they want to go into a nursing home. I often hear that they want to stay home, or they want to stay in a personal care home, but unfortunately, it is too expensive, or the assets will become completely depleted.Although I understand that long-term care insurance or a long-term care hybrid policy may seem expensive now, trust me, the peace of mind that it will provide later when you or a loved one wants, and is able, to stay home or go to a personal care home, the money spent on the policy which allows you to do so is small compared to the out-of-pocket cost of that care, and, at least as importantly, your peace of mind. Although we are fortunate in the state of Pennsylvania to be able to assist people in crisis, we are not as easily able to help people to stay in their homes or in a personal care home. Do yourself and your family a favor, and if at all possible secure your long-term care insurance now for peace of mind later; the earlier the better. If you want to talk about this or any other estate planning matter your wanting more information about, contact us!
Jan 20, 2023
Happy National Caregiver Day
One of the most overlooked and underappreciated groups are caregivers. Whether the caregivers are professionals or family members trying to help informally, caregivers are the unsung heroes who rarely get credit for all that they are doing. Today, we challenge you to thank the caregivers in your life for their services!If you know a caregiver who has chosen caregiving as their profession, they are certainly underpaid and underappreciated on a regular basis. The last three years have been especially tough for them. Your words of gratitude and thanks will go far in encouraging weary paid caregivers. If you know a family member who is providing in-kind service as a loved ones caregiver, please take time to thank them for sacrificing their own priorities and time with their nuclear families to provide care for a loved one.At Bellomo & Associates, our team is honored to serve our community and work daily with these types of caregivers. Whether paid or volunteering, caregivers make our community strong and amazing. Thank you to every caregiver out there. Happy National Caregiver Day! Contact us at 717-844-9639.
Mar 20, 2023
How Soon is Soon Enough to get a Life Care Plan?
A life care plan is a living, breathing, document that provides for you as you age. It is a tool that helps you plan for your future. In my opinion, it is never too early to have a Life Care Plan because it can always be changed and updated as time passes. Such plans are not a one-time, static document, but rather provide an opportunity to be shaped and changed as your health, life situation and circumstances change. We dont believe that waiting until you are in crisis and absolutely need a Life Care Plan is a good idea.Creating your Life Care Plan in a season of calm is best, so that your true wishes, desires, and goals can be incorporated into the plan. Lifes crisis moments and difficult seasons will come and go and it will be helpful to have your big picture goals and wishes fully outlined and clearly understood by your family, your Life Care Planning advocate and law firm team. Your team will work hard to ensure that your wishes and goals remain at the forefront of planning, even in those crisis seasons.Our Bellomo & Associates team members have become huge believers in the Life Care Planning model and what the program offers to our clients and their families. There is no question that these plans go beyond the legal technical documents that a lawyer creates for you and that is exactly the point! Our lives and our health are not about documents. Our best lives and stable health dont happen by accident, but rather through the process of creating goals and planning for our care and our familys needs. A Life Care Plan can mean the difference between living independently with assistance in your home versus somewhere that you dont want to live simply because you did not plan ahead. Its never too early, but its also never too late. Although we dont recommend the latter for the reasons mentioned above, late is better than never!If you would like to learn more about our Life Care Planning program and our Client Care Advocate, Meg Motter, LCSW please reach out to our office at (717) 844-9639 or visit our website for more information, including dates for upcoming Life Care Planning Workshops.
Mar 20, 2023
.png)
Dealing with Deed Spam Mail
Have you recently purchased a home or made any changes to your propertys deed? Have you received an unexpected letter offering a copy of your deed for a fee? If so, youve likely encountered spam mail.Theres a company known as Land Solutions based in California that sends out Recorder of Deed Notices to individuals with newly recorded deeds. These notices claim that you can obtain a copy of your deed for a service fee of $109.00. Since the transfer of a deed is a matter of public record, they can easily access your name, address, and property information. While what theyre doing may not be a scam, we prefer to refer to it as spam. The truth is, the party responsible for transferring the deed, or even your local recorder of deeds, can provide you with a copy for a small fee or sometimes even for free. Theres no need to pay a separate company for this service.At Bellomo & Associates, many of our clients have received this type of letter, and we are delighted that they reached out to us before paying an unnecessary fee for a document we already possess on their behalf.When you receive such correspondence after making any changes, its crucial to research the company that sent it, reach out to the parties you were working with, and carefully read the fine print. In the case of these specific notices, the fine print typically states that it is not a bill but a solicitation, and you are not legally obligated to pay the amount requested.Together, we can minimize the impact of spam by working collectively and staying informed.
Apr 19, 2024
Estate Planning Keeps Changing. Heres What Families Need to Know
Most families do not need to follow every new court decision, Medicaid rule, tax election, or change to federal retirement law. That is our job. What families do need to know is when one of those changes could affect a decision they are making right now. After reviewing materials from the 2026 Elder Law Institute and additional training on post-death tax and estate planning, our team identified several developments that deserve attention. Some affect people planning for a loved one with special needs. Others may matter to families navigating Medicaid, administering an estate, or ensuring an existing estate plan still works as intended. Here are five groups of people who should be paying particular attention. 1. If You Have a Loved One With a DisabilityOne of the biggest developments involves ABLE accounts. Beginning in 2026, eligibility expands so that an individuals disability must have begun before age 46 rather than before age 26. That may sound like a small change, but it could open the door for individuals and families who previously did not qualify. ABLE accounts can be an important part of special needs planning because they may allow an individual with a disability to save and use money for qualified expenses while preserving access to certain public benefits. For families who were previously told that an ABLE account was not an option because of the individuals age when the disability began, it may be time to revisit that conversation. The important question is not simply, Can we open an ABLE account now? It is, How should an ABLE account fit into the rest of our planning? That may include a Special Needs Trust, beneficiary designations, public benefits, housing assistance, family support, and the long-term financial needs of the person you love. 2. If a Retirement Account Will Eventually Benefit Someone With Special NeedsThis is an area where families can have excellent intentions and still create an unintended problem. You may have spent years carefully creating a Special Needs Trust to protect a child or loved one with a disability. But then there is the IRA. Or the 401(k). Or another retirement account with its own beneficiary designation. Those beneficiary forms matter. Retirement accounts are governed by their beneficiary designations, and coordinating those designations with a Special Needs Trust can involve additional rules involving inherited retirement accounts. That means creating the trust is only part of the job. The beneficiary designation needs to work with the trust and with the rest of the estate plan. This is one reason we place so much emphasis on follow-through. A beautifully drafted estate plan cannot accomplish what you intended if the assets never make it to the right place. If your estate plan includes a loved one with special needs and you have significant retirement assets, this is worth reviewing. 3. If You Are Helping an Aging ParentFamilies helping aging parents already have enough to manage. There may be medical appointments, medications, housing decisions, caregiving, finances, insurance, and questions about whether additional care will eventually be needed. Medicaid adds another layer of complexity. There are upcoming changes involving Medicaid eligibility and administration that could affect how families prepare, when applications should be submitted, what documentation will be needed, and how much room families have to correct problems after the fact. Pennsylvania is also continuing to develop options involving Medicaid-funded assisted living, which raises another set of practical questions. Which facilities are actually participating? Is there availability? What level of care is being provided? How does the program work in the real world, not simply on paper? Those are the questions families need answered. There are also Medicaid programs beyond traditional nursing home Medicaid that may help certain individuals, including programs connected to disability, employment, Medicare costs, and other circumstances. The difficulty is that most families do not know which questions to ask. That is why waiting until a parent is already in crisis can make everything harder. If you are starting to notice that Mom or Dad needs more help than they used to, that is often the right time to begin learning about the options available. 4. If Your Spouse or Parent Recently DiedFamilies understandably want to get things handled after someone dies. Close the accounts. Transfer the assets. Distribute the inheritance. Sell what needs to be sold. Finish the estate. But moving too quickly can sometimes eliminate options that should have been considered first. There may be decisions involving inherited retirement accounts, tax elections, disclaimers, portability between spouses, cost basis, business interests, trusts, and other assets. Some of those decisions have deadlines. Others can be affected by whether an asset has already been distributed or accepted by a beneficiary. That is why we believe one of the most important parts of probate and trust administration happens before significant distributions are made. A family may be asking, How quickly can we get this money distributed? Our first question may need to be, Is there anything we should review before we do that? Estate planning does not necessarily end when someone dies. In some situations, there are still important planning decisions available to the family afterward. 5. If You Are Serving as an Executor or TrusteeBeing named executor or trustee can feel like an honor. Then the work begins. Suddenly you are responsible for property that is not yours, money that belongs to an estate or trust, deadlines you may never have heard of, beneficiaries who want answers, and legal duties that can create personal consequences if handled incorrectly. Executors and trustees may need to address issues involving distributions, taxes, creditors, conflicts of interest, business interests, retirement accounts, notices to interested parties, and the eventual closing of the estate or trust. And one of the biggest mistakes a fiduciary can make is assuming that every reasonable-looking decision is automatically a legally appropriate one. You do not have to become an estate administration expert overnight. You do need to understand your role before making major decisions. That is especially important before distributing money, selling property, transferring business interests, or taking actions that may be difficult to reverse. You Do Not Have to Keep Track of Every ChangeEstate planning and elder law continue to evolve. Some developments require immediate action. Others deserve a closer look. Still others simply need to be monitored until the law becomes clearer. Our responsibility is to know the difference. When our team attends continuing education programs or reviews new developments, we do not want that information sitting in a binder on a shelf. We ask a much more practical question: Does this change anything we should be doing for the families we serve? Sometimes the answer means updating a checklist. Sometimes it means reviewing a beneficiary designation. Sometimes it means slowing down before an estate distribution. And sometimes it means reaching out to a family because an option that did not exist for them several years ago may be available today. You do not need to understand every new development in estate planning, Medicaid, special needs planning, or estate administration. You need to know whether the changes affect your family, your plan, or the decisions you are about to make. If any of the situations above sound familiar, the next step is to learn what applies to your circumstances before making a decision that may be difficult to undo.
Oct 02, 2026
.png)
Legacy Planning: Leaving a Lasting Impact
I hope this message finds you in good health and high spirits. As your trusted elder law and estate planning advocate here at Bellomo & Associates, I am excited to share some insights into a topic close to my heart legacy planning. Life is a beautiful journey filled with moments that shape, define, and create the unique tapestry of our existence. For many of us, legacy planning can be both contemplative and uplifting. Its about weaving the threads of your life into a story that not only withstands the test of time but also serves as a guiding light for generations to come. Legacy isnt just about the assets you accumulate; its about the values you hold dear, the wisdom youve gained, and the love youve shared. As an elder law and estate planning attorney, my goal is to help you craft a legacy that echoes your unique narrative. Its about ensuring that your journey, struggles, and triumphs become a source of inspiration for those you cherish the most. Just as our lives evolve through different seasons, so should our estate plans. Whether you are an income-generating couple, a wise senior considering the next steps, or a young family dreaming of a secure future, your legacy plan should be a reflection of your current reality and your aspirations for the future. For those approaching the golden years, the prospect of skilled nursing facility care can be a daunting one. Our team is here to guide you through the intricacies of elder law with warmth and compassion. Its not just about protecting your assets; its about ensuring that you receive the care and respect you deserve. To the young families reading this, I understand the joy and responsibility that comes with building a family. Legacy planning is not just a matter of paperwork; its a promise to provide and protect. Lets work together to create a plan that safeguards your loved ones, ensuring their future is as bright as the love you share. I invite you to join me and our team at our next estate planning workshop. Its a space where like-minded individuals come together to learn, share, and ask questions. Estate planning is not just a legal process; its a collaborative journey, and were here to guide you every step of the way. Remember, your legacy is not just about what you leave behind; its about the impact you make today. Lets embark on this journey together, creating a legacy that stands as a testament to a life well-lived.To a future filled with purpose and legacy,Jeff Bellomo
Oct 11, 2024
The Best Time to Make an Estate Plan Is Before You Need One
Estate planning is easy to put off. Work is busy. The kids need something. The house needs attention. Everyone is healthy, and there is always something that feels more urgent. So you tell yourself, Ill get to it later. I understand that. Most people are not avoiding estate planning because they do not care about their families. They are busy taking care of those families right now. But that is also why I encourage people to begin before there is an emergency. When life is calm, you have time to ask questions, talk with the people you love, and make choices that feel right to you. At Bellomo & Associates, we want families to have that opportunity, instead of trying to figure everything out beside a hospital bed. Why Do So Many People Put Estate Planning Off?Sometimes people think they are too young. Sometimes they assume they do not own enough to need a plan. And sometimes they believe their spouse or children already know what they would want. Those thoughts are understandable. If you are feeling well and handling your own affairs, documents such as powers of attorney and healthcare directives may seem like something you will need years from now. The trouble is that we do not get to choose when life changes. Estate planning is easier when you can approach it with a clear head and enough time to consider your options. You can talk about what matters to you without asking your family to make every decision in the middle of a crisis. Estate Planning Is About More Than What Happens After DeathWhen people hear estate plan, they often think of a will and who will inherit the house. Those are important questions, but a plan can also help your family while you are living. What if an accident leaves you temporarily unable to manage your bills? What if an illness makes it difficult to speak with your doctors? Who would step in, and would that person have the authority they need? A financial power of attorney can address who may handle financial matters for you. A healthcare power of attorney can name someone to make healthcare decisions when you cannot. A living will can give direction about certain treatment choices. Pennsylvania recognizes these as distinct planning documents, each with its own requirements. These are deeply personal choices. Making them ahead of time gives your loved ones something far more useful than a guess. The Best Time to Choose Someone Is Before You Need ThemThink about the person you would trust to help if you could not manage your finances for a while. You probably have someone in mind. But have you asked whether they would be willing to take on that role? Do they know where to find your important information? Planning gives you time to have that conversation. You can choose someone who understands you, explain what matters most, and name a backup in case your first choice cannot serve. Without appropriate documents, a family may know exactly whom you would have chosen and still have trouble acting on your behalf. Depending on the circumstances, they may need to seek court involvement. That can be stressful for a spouse or child who is already worried about you. My Family Knows What I Want May Not Be EnoughI hear this often: Jeff, my family knows what I want. They might know a great deal about you. They know how you take your coffee, what you think about the holidays, and which stories you will tell whenever everyone is together. Still, a serious medical decision can be different from any conversation you have had before. Picture three adult children trying to decide what Mom would want. One remembers her saying she never wanted to be kept alive by machines. Another remembers her talking about doing everything possible to have more time with her grandchildren. Each believes they are honoring her wishes. A conversation and the right documents can help your family understand your preferences and know who should make decisions if you cannot. That guidance is a gift to the people who love you. Waiting for a Crisis Can Make Planning HarderEstate planning works best when you can take your time. You can ask what a document means, think about whom to name, and decide how the pieces of your plan should fit together. A sudden illness or a change in memory can make those conversations more difficult. A diagnosis alone does not necessarily mean someone can no longer make legal decisions, but capacity questions can arise, and options may become more limited as circumstances change. This is why I encourage people to plan while the choices are clearly theirs to make. There is comfort in knowing you had the chance to think them through. You Do Not Have to Be Wealthy to Need an Estate PlanEstate planning is about people as much as property. A young parent may want to name someone to care for their children. A single adult may want a trusted friend or relative to speak with doctors if needed. A grandparent may want to make sure an inheritance is handled thoughtfully for the next generation. You may also need to consider your home, personal belongings, pets, online accounts, or who would be responsible for settling your affairs. None of those questions depends on having a certain amount of money. If there are people you care about and decisions you would want to make for yourself, there is a reason to think about a plan. Your Will Is Only One Part of the PlanA will matters, but it may not control every asset you own. Retirement accounts and life insurance policies often have beneficiary designations. The way a home or account is owned may also affect what happens to it. That is why an old beneficiary form deserves attention. Perhaps it names someone who has since died. Perhaps your family has grown, but the form has not changed. A plan works better when you review how its parts fit together, rather than assuming the will answers every question. Your Plan Can Change as Your Life ChangesSome people wait because they want to get every decision perfect the first time. You do not need to predict the rest of your life. A plan should reflect your life now. Then, when life changes, you can review it. Marriage, divorce, a new child or grandchild, retirement, a move, or a change in a trusted relationship may all be reasons to take another look. Beginning today does not mean you can never make a different choice. It means your family has guidance based on what you want today. Give Your Family Instructions Instead of QuestionsWhen someone needs help unexpectedly, loved ones often want to do the right thing. They may simply be unsure what that is. Who can speak with the bank? Where are the documents? Who should make a medical decision? What did Dad want to happen to the house? An estate plan cannot spare a family every hard moment. It can give them direction through some of those moments, and it can let you choose the people you trust to help. When things are going well, estate planning may feel easy to postpone. That is also when you may have the most room to think, talk, and decide. Bellomo & Associates welcomes families who want to start that conversation before a crisis makes it urgent.
Oct 23, 2026
Reverse Mortgages Explained: A Powerful Tool Most Families Overlook
This blog is inspired by a recent episode of The Red Wagon Estate Planning & Elder Law Show, where Jeff Bellomo sat down with Ken Pittz of Advisors Mortgage Services to discuss reverse mortgages, his book Kinetic Wealth, and how this often-misunderstood financial tool can play a meaningful role in retirement and long-term care planning. For many families, the phrase reverse mortgage immediately brings hesitation. There is confusion, skepticism, and often fear. As Ken pointed out in the conversation, confusion leads people to shut down and say no before they fully understand the opportunity in front of them. The reality is that reverse mortgages, when used correctly, can be a powerful planning tool that helps seniors maintain independence, improve cash flow, and protect other assets. What Is a Reverse Mortgage At its core, a reverse mortgage allows homeowners to access the equity they have built in their home without having to make monthly mortgage payments. Instead of paying the bank each month, the homeowner receives access to funds that can be used for a variety of purposes. These funds can help with: supplementing retirement income covering unexpected expenses paying for in-home care reducing financial stress in later years Qualification is often easier than a traditional mortgage because the focus is not on the borrowers ability to make payments. Instead, the lender evaluates whether the homeowner can maintain the property, pay taxes, and cover insurance. Clearing Up Common Misconceptions One of the biggest takeaways from the podcast is how misunderstood reverse mortgages truly are. Many people believe that the bank takes ownership of the home or that the family loses all equity. That is not how it works. A reverse mortgage is still a loan. The homeowner retains ownership of the property. When the loan becomes due, typically after the homeowner passes away or leaves the home permanently, the house is sold and the loan is repaid. Any remaining equity belongs to the estate and is passed on to heirs. This structure is no different than a traditional mortgage in terms of how the estate is handled at the end. Why Timing Matters One of the most important insights from the episode is that reverse mortgages are often used at the wrong time. Many people wait until they are financially strained before considering this option. According to Ken, that is actually the least effective time to use it. When used earlier in retirement, a reverse mortgage can: extend the life of retirement savings provide flexibility during market downturns reduce the need to withdraw from investment accounts create a buffer for unexpected expenses In other words, it can reshape the entire financial outlook of retirement rather than simply acting as a last resort. A Tool for Aging in Place From an elder law perspective, one of the most valuable uses of a reverse mortgage is helping seniors remain in their homes. Many families want to avoid nursing homes if possible and instead receive care at home. The challenge is cost. In-home care can be expensive, and not every family has liquid assets available to cover those expenses. A reverse mortgage can unlock equity to help pay for care while allowing the individual to stay in a familiar and comfortable environment. As Jeff noted in the discussion, certain states treat reverse mortgages very favorably when it comes to Medicaid eligibility, particularly for home and community-based services. How Reverse Mortgages Fit Into Estate Planning Reverse mortgages are not just a financial product. They are part of a larger planning conversation. When integrated properly into an estate and elder law plan, they can support: long-term care planning Medicaid qualification strategies preservation of other assets reducing financial burden on family members maintaining independence and quality of life Without planning, families often face crisis decisions. With planning, they have options. The Bigger Picture One of the most important points raised in the podcast is that the internet is not a reliable place to make decisions about complex financial tools. It can be helpful for gathering information, but true understanding comes from working with experienced professionals who can apply these strategies to your specific situation. Every familys circumstances are different. The right approach depends on health, finances, goals, and long-term care needs. Take the Next Step If you or a loved one is approaching retirement, concerned about long-term care, or simply unsure how to make the most of your assets, now is the time to start learning. Reverse mortgages may not be right for everyone, but for many families, they can be a valuable piece of the puzzle.
May 19, 2026
Do You Need a Probate Attorney, or Can You Handle Probate Yourself?
Being named executor can feel like an honor. Someone you love trusted you to carry out their wishes. At first, you may think, They left a will. I know what they wanted. I can take care of this. Then you open the first envelope. A bank needs documents. A bill arrives. Someone asks what will happen to the house. Another family member wants to know when they will receive their inheritance. You are grieving too, and suddenly everyone is looking to you for answers. That is when many executors ask me: Do I need a probate attorney, or can I handle this myself? For some estates, handling the process without ongoing legal help may be manageable. For others, one unanswered question can affect the whole family. The decision depends on what the estate involves, how comfortable you are with the responsibilities, and whether you know when to ask for help. What Does Probate Actually Involve?Probate is the legal process for administering assets that must pass through an estate after someone dies. In Pennsylvania, the process generally begins with the county Register of Wills, which handles probate and the appointment of estate representatives. Pennsylvanias courts provide a directory of county Registers of Wills. The executors work can include locating assets, protecting property, gathering account information, addressing bills and creditor claims, handling tax matters, keeping records, communicating with beneficiaries, and distributing property when it is appropriate to do so. That is a great deal to take on, especially while mourning someone you love. Probate is about more than filing a will. It is the careful work of settling a persons financial affairs and carrying out their wishes. Can You Handle Probate Without a Lawyer?Sometimes, yes. An executor who is organized and has a straightforward estate may feel comfortable handling much of the work. A clear will, easy-to-identify assets, manageable debts, and family members who agree about what should happen can make the process easier. But straightforward does not mean effortless. You may still need to follow procedures, keep accurate records, respond to requests from financial institutions, and decide when the estate is ready to make distributions. I encourage executors to be honest with themselves about the time and attention this will require. There is no prize for figuring out every step alone. Asking a question early can bring welcome clarity before you make a decision on the estates behalf. First, Find Out What Actually Goes Through ProbateNot everything a person owned necessarily passes through their probate estate. An account with a valid beneficiary designation, property owned jointly with survivorship rights, or an asset properly held in a trust may pass another way. Imagine finding a folder containing a will, a life insurance policy, a bank statement, and a deed. It would be easy to assume the will controls all four. In reality, you need to look at how each asset is owned and whether a beneficiary has been named. Sorting that out at the beginning helps the executor understand what they are responsible for administering. It can also prevent confusion when a family member asks why one asset is being handled differently from another. A Simple Estate Can Become Complicated QuicklyConsider two families whose parents leave behind a home, a few accounts, and a vehicle. In the first family, the children agree that the house should be sold, the accounts are easy to locate, and everyone understands the will. In the second, one child wants to keep the house. Another remembers being told it would be sold. A third believes money was taken from an account before their parents died. The estates may look similar on paper, but the executors face very different jobs. Estate value alone does not tell you whether legal guidance would help. Family relationships, unclear documents, creditor claims, and the types of assets involved can change the experience considerably. When Does Working With a Probate Attorney Make Sense?I would pay particular attention to disagreements. If beneficiaries question the will, dispute a decision, or cannot agree about property, the executor may find themselves trying to manage a conflict they did not create. A missing original will, confusing language, questions about changes to a document, or concerns that someone was pressured can also call for legal guidance. The same is true when the estate includes a business, real estate in another state, complicated accounts, or more debts than the estate may be able to pay. At Bellomo & Associates, we want executors to understand what their role requires before a difficult choice becomes a bigger problem. Getting guidance does not mean you have failed at the job your loved one gave you. It means you are taking that responsibility seriously. Probate Mistakes Can Go Beyond PaperworkPeople often worry about filling out the wrong form. I understand that. Forms can be frustrating. But some of the decisions behind those forms deserve even more care. For example, an executor may be eager to give beneficiaries their share, particularly if a family member needs the money. What if a valid debt or tax obligation has not yet been addressed? What if property needs to be maintained, insured, or sold before anyone knows what is available to distribute? An executor is handling property for the estate and its beneficiaries. Keeping good records and understanding your authority before you act can protect both the family and you. Do Not Forget About TaxesFamilies sometimes hear that an estate is too small for federal estate tax and conclude that taxes are off the table. Pennsylvania has an inheritance tax, and an executor may also need to address the deceased persons final income tax return. If the estate earns income after death, that may raise another filing question. The Pennsylvania Department of Revenue explains the state inheritance tax. You do not have to know every tax answer the day you are named executor. You do need to recognize when a question belongs on your list and get the right help with it. Getting Help Does Not Have to Be All or NothingMany executors imagine only two choices: do everything themselves or hand over the entire process. Depending on the estate, you may be able to seek guidance on the parts that concern you most. Perhaps you are comfortable gathering statements and keeping family members informed, but you want help understanding creditor claims. Perhaps most assets are simple, but the house or tax filings raise questions. You can begin by identifying where you feel confident and where you need a clearer path. So, Can You Handle Probate Yourself?You may be able to, particularly if the documents are clear, the assets are straightforward, debts are manageable, and the family is working together. But you do not have to make that decision based on the size of the estate or on what someone else says they managed to do. Take a careful look at what needs to be done and what could happen if a decision is made too soon. The goal is to honor your loved ones wishes, meet the estates obligations, and help the right property reach the right people.
Oct 16, 2026
7 Estate Planning Mistakes That Can Undermine Your Familys Legacy
Mom and Dad worked hard. They paid off the house, built their savings, and made responsible choices over the years. They reassured the family that everything was handled. There was comfort in hearing that. Everyone believed that when the time came, there would be a clear plan and an easy path forward.But when the moment arrived, things began to unravel.The will had not been updated in years. One account is still named an ex-spouse as beneficiary. No one had the legal authority to step in when a health crisis made financial decisions impossible. What should have been a time for grieving and supporting one another became a season of confusion, court involvement, and mounting tension.This is how family legacies are often damaged. Not because people failed to care, but because important details were left unattended.Estate planning mistakes are more common than most families realize. Even those who have documents in place may not have a plan that still works for their lives today. And when a plan is incomplete, outdated, or unclear, the people left behind are often the ones who pay the price.Mistake #1: Having No Estate Plan at AllWhen there is no estate plan in place, the state decides how assets will be distributed. That process, called intestate succession, follows legal rules, not family dynamics, personal values, or promises made around the kitchen table.For loved ones, this can create delays, expenses, and court involvement at the exact moment they are least prepared for it. It can also lead to misunderstandings among family members who thought they knew what their loved one wanted.Without a plan, your family is left reacting to a system instead of being guided by your wishes.Mistake #2: Failing to Update Your Plan After Life ChangesLife changes, and your estate plan should change with it.Marriage, divorce, remarriage, children, grandchildren, a move to another state, or even a major shift in finances can affect how your documents should work. A plan that made perfect sense ten years ago may no longer reflect your family today.This is one of the quietest ways a legacy can be thrown off course. A document may still be legally valid, but that does not mean it still says what you need it to say. Families are often shocked to discover that outdated documents can create very real problems, especially when the people listed in them no longer match the relationships in real life.Mistake #3: Ignoring Beneficiary DesignationsMany people assume their will or trust controls everything. In reality, some of the most important assets pass according to beneficiary designations.Retirement accounts, life insurance policies, and certain bank accounts often transfer directly to the named beneficiary, regardless of what your will says. That means an outdated designation can override the rest of your planning.This is where families are often caught off guard. Someone may have taken the time to create thoughtful estate planning documents, yet an old beneficiary form can quietly send an asset somewhere entirely different. Missing backup beneficiaries can also create avoidable complications and, in some cases, push assets into probate.A small oversight on paper can create a very large problem later.Mistake #4: Not Planning Carefully for a Blended FamilyBlended families deserve thoughtful planning, because the default rules rarely reflect the real relationships involved.Second marriages, stepchildren, and children from prior relationships can create competing priorities if the plan is not clear. A spouse may need security and support. Children may expect certain assets to stay within one side of the family. Everyone may assume things will work out fairly, but assumptions are not a plan.When the documents do not clearly address those concerns, misunderstandings can grow quickly. In some situations, stepchildren may not inherit anything unless they are specifically included. In others, one side of the family may feel unintentionally left out.Clear planning can protect both relationships and intentions.Mistake #5: Choosing the Wrong Person for the JobEstate planning is not just about the documents. It is also about the people you place in charge.An executor, trustee, or agent under power of attorney may one day need to make decisions under stress, stay organized, communicate clearly, and follow through responsibly. Those are meaningful duties, and they should not be assigned lightly.Many people choose someone out of habit, family pressure, or a desire to avoid hurt feelings. But the right person is not always the most obvious. Naming someone who is disorganized, overwhelmed, or uncomfortable with conflict can create delays and tension when your family needs steadiness the most.The people you choose matter just as much as the words on the page.Mistake #6: Failing to Plan for IncapacityEstate planning is not only about what happens after death. It is also about what happens if you are still here but unable to manage your own affairs.Without a durable power of attorney or healthcare directive, the people closest to you may not have the legal authority to help when it matters most. That can mean court involvement, unnecessary delay, and added stress during an already difficult time.A solid incapacity plan gives your loved ones a way to step in smoothly if needed. It provides continuity, clarity, and peace of mind at a moment when uncertainty can feel overwhelming.Mistake #7: Keeping the Plan Too Secret or Too VagueEven a well-drafted estate plan can create confusion if no one understands the basics of how it works.Your family does not need every detail, but they should know who is responsible for what, where important documents are located, and what kind of plan is in place. When there is no communication, people tend to fill in the blanks on their own.That can be especially painful when decisions are unexpected or distributions are unequal. Without context, even thoughtful choices can feel hurtful or suspicious. A little clarity now can prevent a great deal of conflict later.A Legacy Is About More Than What You Leave BehindA strong estate plan does more than transfer assets. It creates order in a difficult moment. It reduces stress. It helps preserve relationships. It gives your loved ones something deeply valuable: clarity.At Bellomo & Associates, we often meet families after problems have already begun. The pattern is rarely a lack of love or intention. More often, it is a plan that was never completed, never updated, or never fully coordinated. The encouraging news is that these mistakes are preventable.The families who experience the smoothest transitions are not always the ones with the most wealth. They are often the ones who planned with care, reviewed their documents regularly, and made sure their wishes were clearly supported.That is why thoughtful planning matters so much. It is not just about protecting assets. It is about protecting the people connected to them.If you are wondering whether your current plan would truly work for your family in real life, Bellomo & Associates invites you to register for a workshop and learn how to create a plan that brings more clarity, confidence, and peace of mind for the people you love.
May 29, 2026

10 Things You Should Leave Out of Your Will
Over the years, weve seen just how much thought and love people pour into their wills. It makes sense because a will is one of the most personal documents youll ever create. Its your chance to provide for the people you care about and to leave behind a lasting legacy. But heres the tricky part: sometimes, the very things people include in their wills can end up creating more problems than solutions. Families have faced probate delays, unexpected tax issues, and even painful disputes simply because of how a will was written. The good news is that these situations can be avoided with a little guidance. To help, here are 10 things you should leave out of your will and what you can do instead. 1. Gifts to individuals with special needsLeaving money directly to someone with special needs can unintentionally disqualify them from vital government benefits. A better option is creating a Supplemental Needs Trust, which allows them to receive support while keeping their eligibility intact. 2. Pets and money for their careLegally, pets are considered property, which means they cant inherit money. Instead, you can create a pet trust that sets aside funds and instructions for their lifelong care. 3. Non-probate assetsRetirement accounts, life insurance policies, and bank accounts with designated beneficiaries dont pass through your will. Those beneficiary designations override your will, so keeping them updated is key. 4. Fixed, unrealistic dollar amountsIf your estate doesnt have enough to cover a large fixed gift, other heirs may be left with little or nothing. Using percentages is usually a fairer and more flexible approach. 5. Conditional giftsWills that say things like, Only if she gets married or As long as he never remarries tend to cause delays and conflict. Simple, unconditional gifts are much easier for everyone involved. 6. Sensitive personal informationBecause a will becomes public once its filed with the court, private details like Social Security numbers, account numbers, or passwords should never be included. Keep this information in a separate, secure document. 7. Funeral instructionsBy the time your will is read, your funeral may already have taken place. Share your wishes with loved ones ahead of time or create a separate document for end-of-life arrangements. 8. Firearms and other restricted propertyGuns and similar items can only be transferred under specific state and federal rules. A gun trust or other legal tool ensures everything is handled properly. 9. Explanations or criticisms of disinherited heirsIts natural to want to explain your decisions, but including detailed reasons in your will often causes more harm and additional challenges. A simple, neutral statement is usually best. 10. Business interestsPassing a business through a will can lead to complications and delays. A trust or a formal succession plan provides a smoother, more private way to ensure your business continues. Creating a will isnt just about writing down your wishes. Its about ensuring that those wishes can be carried out without confusion, disputes, or heartache for the people you love. Knowing what not to include is just as important as deciding what to put in. If youre ready to take the guesswork out of your estate plan, we would love to guide you every step of the way. Register for a Workshop
Oct 10, 2025
Whats Not to Love?
Whats not to love? You may think you know, but peek into my world as a Bellomo employee and lead of the firms Life Care Planning (LCP) program for a moment.An LCP client cant remember how to play 500 Rummy? Amber and Meg spend the morning playing cards with him. The wife of a hospitalized client is distraught because the only nursing home bed is 2 hours away? Sharee alerts Meg, who provides education, emotional support, and advocates with the discharge planner.A clients bride is struggling? Jennah gets a heads up and sends flowers to brighten her day. A clients financial planner needs clarification on next steps? Jeff immediately reaches out to him. A long-time Bellomo client is hospitalized and dying? Two team members visit to love on him and sit with the familyand our whole team grieves.Another LCP client is dying? Meg is at the bedside for hours, hugging on his bride and helping to navigate decisions. The wife isnt sure what to do now that hes died? Michelle calls to ease her worries and begin her probate education. I had lunch with the bride yesterday. We talked about her journey, the tough decisions made along the way, her gratitude to the facility and hospice teams for their exceptional care. Weeks ago, the wife insisted that I thank Jeff for hershe called our team cracker jacks. Yesterday, she talked about how thankful she is to have found our firm, citing above all else, the peace of mind she has knowing that our team is in her life, protecting her.When I returned to the office, a teammate stopped me to ask how she was doingAndi was sincerely interested and relieved to hear that she was doing well. Today I find myself thankful that this mans bride is still going to be in my life, as despite her husband having died, she has signed on for another year of maintenance and another year of LCP for herself and her disabled adult son. You knew that you loved Bellomo & Associates, right?Trust me, the Bellomo employeesyep, all of us cracker jackslove this incredible law firm just as much!
Mar 22, 2023
.png)
A $29 Million Estate, a Forgotten Will, and One Messy Legal BattleHeres What You Can Learn
It sounds like something out of a movie: A wealthy man passes away, leaving behind a historic manor, a million-dollar estate, and two women claiming to be his rightful heir.But this isnt fictionits a real case thats making headlines. And while most of us dont have castles and wine collections to pass on, the lessons from this case apply to everyone.At Bellomo & Associates, we believe estate planning isnt just about moneyits about love, legacy, and protecting the people you care about.The Real-Life Drama UnfoldsJustin Bodle was a successful British TV producer. When he died in 2019, he left behind a fortune worth $29 million. But heres where it gets messy His most recent will, written in 2013, left everything to his estranged wife. Since then, he had a new partner and two additional children but never updated his documents. Now, his partner is fighting for what she believes is fair under inheritance laws, while the wife (also the executor) claims the estate is drained by debts and taxes. Its ugly. And preventable. What Went Wrong?His will didnt reflect his current family life.There was no plan to care for the partner or new children.There wasnt enough liquidity to handle taxes and expenses.The result? A bitter court battle, expensive legal fees, and uncertainty for everyone left behind.What Does This Have to Do with You?Even if you dont own a manor in the English countryside, heres what you can learn:Update your plan after life changes. Divorce, remarriage, new kidsit all matters.Be specific. If you want to provide for a partner or child, spell it out clearly.Dont rely on good intentions. Executors have legal duties, not emotional ones.Think about cash flow. Your loved ones will need money to settle your affairs.Get help from a pro. Estate planning is not a DIY project, especially in blended families.Your Legacy Should Be Love, Not LitigationStories like this make headlines because theyre dramatic, but behind every court battle is a family thats hurting. You can avoid that. Lets build a plan that reflects your real life, real values, and real wishesso your loved ones are taken care of and stay out of court.
Jun 20, 2025

Seniors BlueBook Senior Care Spotlight Presents "How do you take the fear out of dying?" with Jeff B
We visited with Jeff Bellomo of Bellomo & Associates and explored how to take the fear out of dying? Jeff explains that much of the fear connected with dying has to do with not having your affairs in order and your family taken care of. How do you protect your home and yet be prepared? What does taking care of your family look like? Jeff Bellomo, Bellomo & Associates, 717-845-5390, www.bellomoassociates.com. More questions? Ask Chris Gartman, Publisher, Seniors Blue Book of South Central PA - [email protected] #Money #Savings #NursingHomes #Homes #Finances #ElderLaw #BellomoAssociates #SeniorsBlueBook
Feb 16, 2021
My LTC Insurance is getting very expensive; What should I do?
If I had a quarter for every time, I was asked this question I would have a lot of quarters for sure. Many LTC (long term care) companies made significant errors in their original underwriting of LTC policies. As a result, many companies are no longer in business. The ones that are in business have greatly changed their practices. However, the biggest issue that has come out of the miscalculation of LTC is that people who still have policies are losing their benefits and their premiums are going through the roof. The question now is what do we do?This is a question that I receive on a regular basis in my estate planning and elder law practice. By way of full disclosure, I am not a licensed insurance agent, and I am not licensed to be able to sell long-term care insurance or any other insurance product. I am an attorney with approximately 20 years of experience in estate planning and elder law and I happen to be a Certified Elder Law Attorney under authorization of the Pennsylvania Supreme Court. While I am not the person who will sell the products, I am certainly an individual who has been advising numerous clients over the years and believe in the benefits of a long-term care policy and what they can provide. We have done numerous other blogs about long-term care insurance and the benefits of said policies.When long-term care insurance first gained popularity, many companies completely missed out on the actuarial tables and in predicting what people were going to need. Because of this drastic miscalculation, most of the companies who originally were in the markets for long-term care insurance are no longer there. The few standing companies that are left are trying to figure out ways to make up for the mistakes of the past. Because of that, they are often forced to increase premiums and decrease benefits. Although these companies do have to get permission from the insurance board, it is not a very difficult proposition and, in most cases, they will almost always be able to receive permission. The most difficult part is that individuals have been paying into a plan for a number of years and now are learning that theyre going to have to decrease their benefits and even then, they may have to increase the premiums that they are paying. It is heart wrenching to have to provide guidance in these situations and ultimately, I always encourage them to bring in their financial professionals to try to make the decisions. It is as much about the numbers and the common sense as it is about the emotion involved. It is very easy for us to get disgusted and upset about what is occurring, but it is a cold, harsh reality of the miscalculations that were made in the past. In some instances, increasing premiums and decreasing benefits is the only way some of these companies will survive.My best advice to any and all people who are faced with this dilemma is to write out the pros and cons and to try to make the evaluation and determination about numbers and as little as possible about emotion of the situation. It is too easy to get hung up on the principle of the manner, but the truth is principals are expensive and cause wars. Make the best decision for you and your family based upon the information that you have in front of you. Long-term care is not going away and dropping the policy out of spite is not going to help anyone.If you are looking for advice in regards to estate planning, please call our office at 717-844-9639 or click the link here and we will contact you.